Tag Archives: investing

Aman Raina’s 5-year Robo advisor review — and how Robos are holding up in the bear market

By Aman Raina, SageInvestors.ca

Special to the Financial Independence Hub

NOTE: This review was initially undertaken using data compiled as of January 30, 2020, which marked the 5-year anniversary during which the portfolio was active but prior to the severe market turbulence that occurred in February and March 2020.  As it became apparent that the market pullback was becoming an epic meltdown, additional data was compiled and included into the review.

Five years ago I embarked on a personal experiment. I was having a hard time getting any insights on the effectiveness of a new investment services that was shaking the ground at the time in 2015.

Known or labeled as Robo Advisors, these new wealth management companies offered services to invest on behalf of others using an online platform and a combination of algorithms and computer coding to buy and sell specific investments and manage portfolios. Five years ago these firms were just stepping into the investing consciousness, but since then they have mushroomed and even traditional investment companies are now offering some flavor of online investment management services.

It all seemed quite appealing; however, there was one thing that many marketing materials, blogs, and mainstream media were avoiding … do these types of services make money for investors? Is this the type of service that would successfully bring more people, who naturally feel intimidated and frustrated by the whole investing concept into the investing domain?

Since no robo advisor company back then was interested in disclosing their performance (they still avoid it) other than citing research that their low cost/passive oriented strategy is superior, I decided five years ago to try an experiment to get some more insights that did not involve boilerplate marketing speak. I set up an account with one of the “large” Robo Adviser firms and invested $5000 of my own money into it.

My goal was to go through the process and blog about my experience using the service, how the ROBO went about making decisions and how it managed my portfolio, and more importantly, the results. I’ve always said that we need a good five years to really get a handle on how effective these services are compared to traditional wealth management services. Well, I just crossed the five-year mark of my ROBO journey, so let’s check back in and take a look at how it’s been doing. I’ve also said that I would reserve my opinions about this service until we reached that five-year threshold. Well here we are and I’m ready to unload my takes.


2019 was an epic year for stocks. US major stock indexes were up just over 30 per cent on the year. Fantastic returns. Hopefully my ROBO got a good piece of that action.

Performance

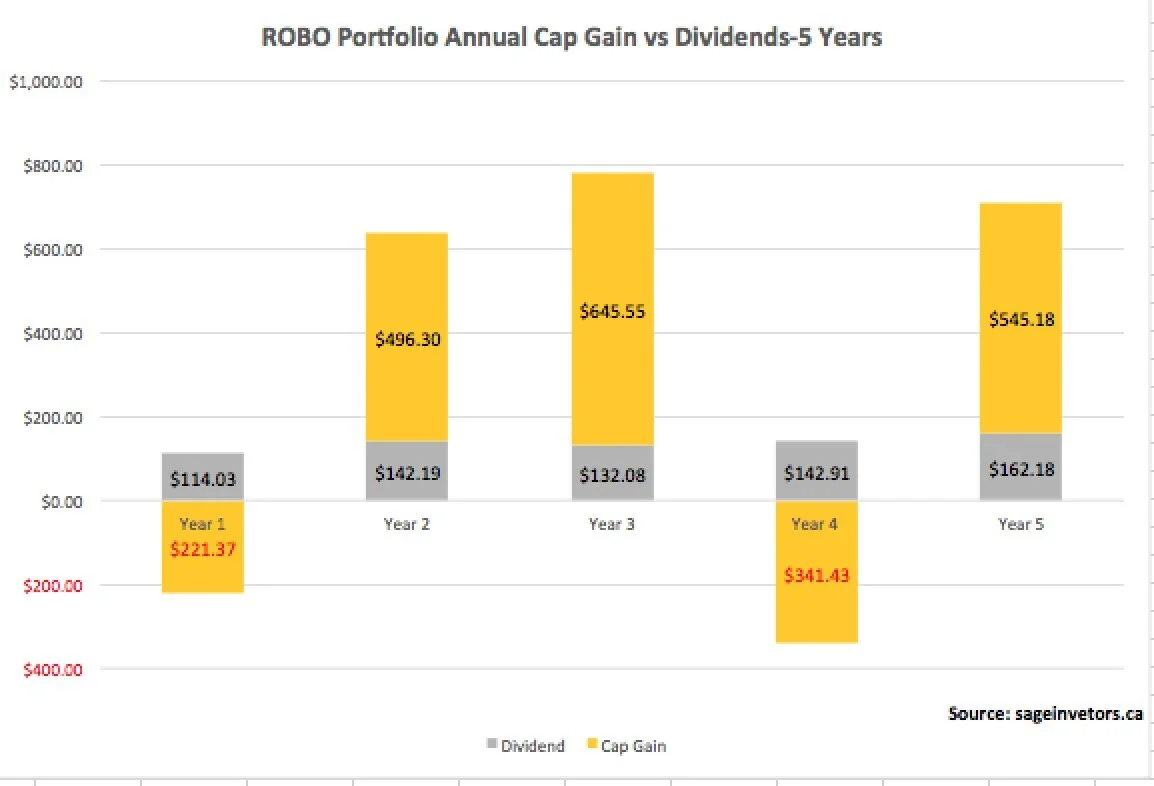
Overall, my ROBO portfolio posted a solid year. The portfolio was up 11.6 per cent year over year, a nice rebound from the previous year where it lost 2.1 per cent. Over the 5 years, the portfolio generated positive returns in three of the 5 years, and posted double-digit returns in those three years. The portfolio increased by $707, of which $162 came from dividend income while the remaining $545 came from capital gains. Over the year period, the ROBO portfolio increased from my initial $5000 to $6817, a cumulative return of 36 per cent. Of the $1817 increase, 1/3 was from dividends while the remainders was from capital gains. The portfolio continued to benefit from higher concentration of US and Canadian equities, which again hit it out of the park the past year.

ROBO Annual Return Chart.jpg
ROBO Cap Gain vs Dividend Chart.jpg

Below is the breakdown of the portfolio. Five years ago when I set up the account I answered a series of questions about my financial literacy and risk tolerance. ROBO took my responses and crafted a portfolio that it felt was compatible with my profile. Continue Reading…

Americans extremely worried about job security, finances and Retirement due to Coronavirus

By Mike Brown

Special to the Financial Independence Hub

Due to COVID-19, 57% of adult Americans are worried about their job security, while 63% are concerned about both their retirement savings and ability to make monthly student loan payments. Plus, many other insights from LendEDU’s newest survey.

At the time of this writing, Johns Hopkins’ Coronavirus Resource Center has reported 353,692 cases of Coronavirus around the world and 15,430 deaths. In the United States, there have been 35,345, while the total number of deaths is 473 by most estimates.

Then there’s the economic fallout in the U.S. as the stock market has gone into a tailspin, and a recession, or worse, seems likely. With the nation necessarily self-quarantining itself, countless small businesses are shuddering their doors and laying people off.

In the wake of this global pandemic, LendEDU has surveyed 1,000 adult Americans to better gauge the micro-level economic impact that COVID-19 will have on our country.

We found that a substantial proportion of people are worried about their job security, retirement savings, mortgage or student loan payments, and taking on too much credit card debt.

Click here to jump to the full survey results

If you would like to see a specific breakdown of the data other than those provided (ex. state-by-state, gender, age), please email me at brown@lendedu.com.

Observations & Analysis: How is Coronavirus Impacting the Finances & Employment of Americans?

All data is based on a survey of 1,000 adult Americans commissioned by LendEDU and conducted by research firm Pollfish. The survey was conducted on March 18, 2020. For some questions, the answer percentages may not add up to 100% exactly due to rounding.

Job Security

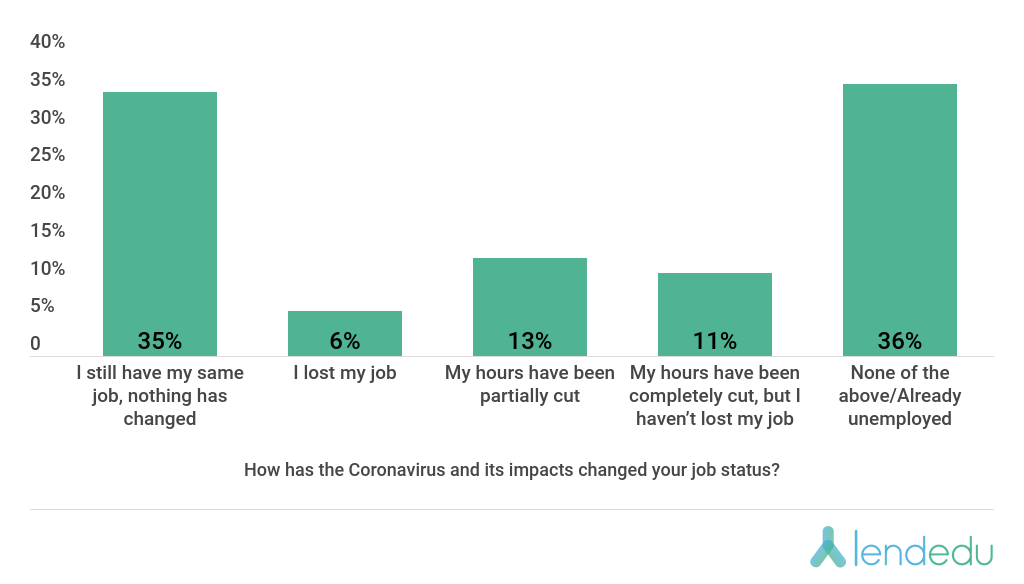
We first asked respondents how Coronavirus has already impacted their job since the virus’ impacts started being felt by the U.S.

35% of adult Americans have been fortunate enough to see no changes to their job due to COVID-19, while a combined 24% have not lost their job, but have seen their hours either reduced or eliminated. Unfortunately, 6% of respondents have lost their job in the Coronavirus fallout.

But, just because the majority of respondents have kept their job in some manner does not mean they aren’t still concerned about losing it. This rings especially true amongst those who have seen hour reductions.
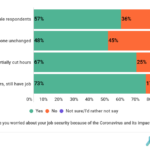
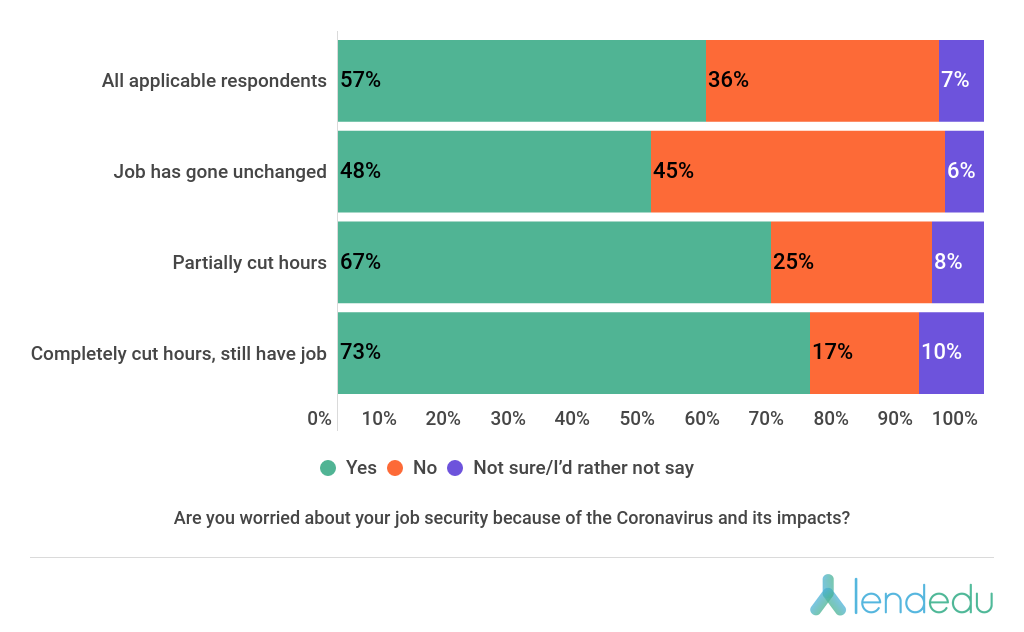
Amongst those that maintained their job in some manner, the majority, 57%, were still concerned about job security moving forward as the impact of Coronavirus widens.

67% of those who have seen reduced hours are worried about keeping their job, while 73% of respondents who had their hours completely cut but kept their job are concerned over job security.

Compare these numbers to the 48% of those who have seen no change in their job, but are still worried about their losing it.

No matter the position employees find themselves in as COVID-19 takes hold, it is clear that stressing over job security will almost be impossible to avoid during this time. Maintaining morale will be a challenge for employees, employers, and the economy as a whole.

General Finances

Before Coronavirus and its impacts hit home here in the U.S., how many Americans were living paycheck to paycheck?
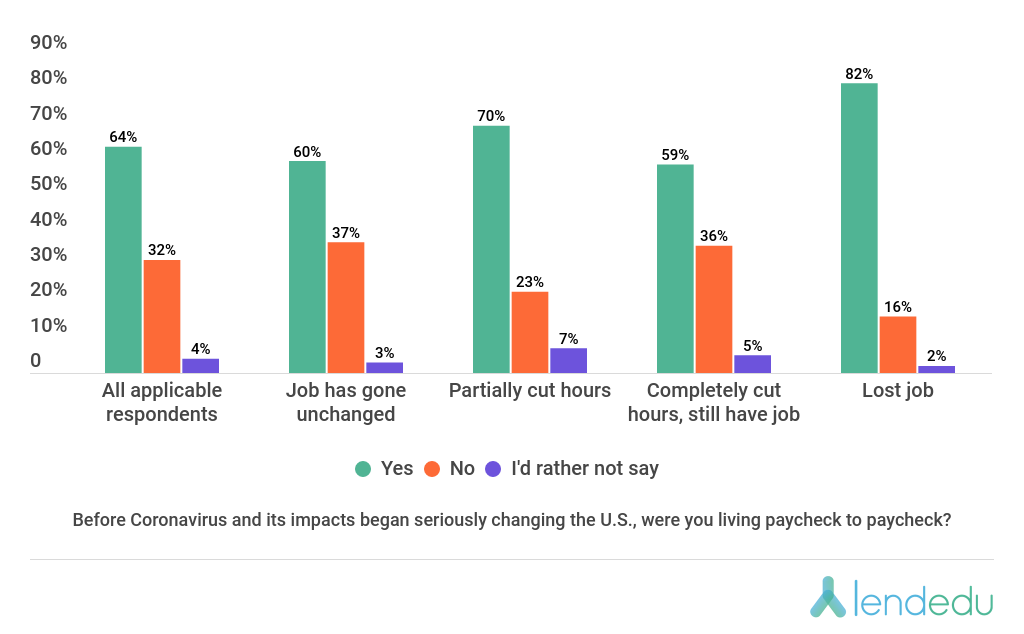
No matter how the data is broken down, the majority of respondents were living paycheck to paycheck before COVID-19 became a large-scale issue in the U.S. This has been reported in other studies as well.

So, while the Coronavirus outbreak in the U.S. may not drastically change the financial lives of those who have seen no changes to their jobs, it could cause severe trouble for those who have seen reduced hours or lost their jobs completely.

For example, 70% of those who have seen their hours partially cut due to COVID-19 were already living paycheck to paycheck, while 82% who have lost their jobs because of the pandemic were doing the same.

Over the next few weeks or even months, these folks will be stretched thin like never before when it comes to their finances. This is why a plan to send Americans checks due to COVID-19 is being discussed in Washington D.C.

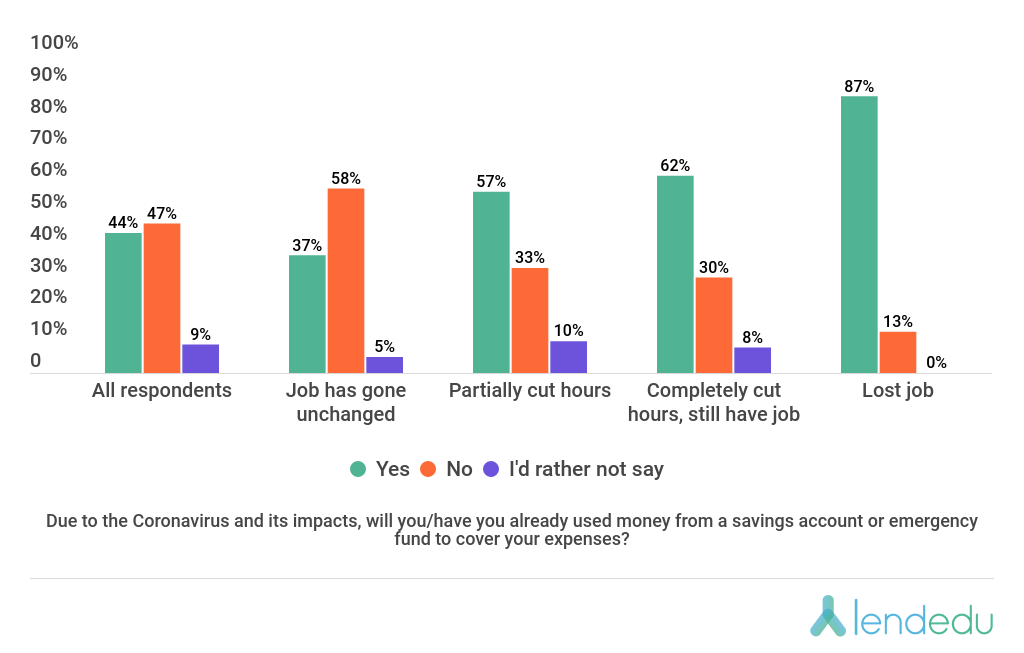
With financial woes forthcoming or already here for many Americans, some will be drawing from an emergency fund or savings account to cover expenses.
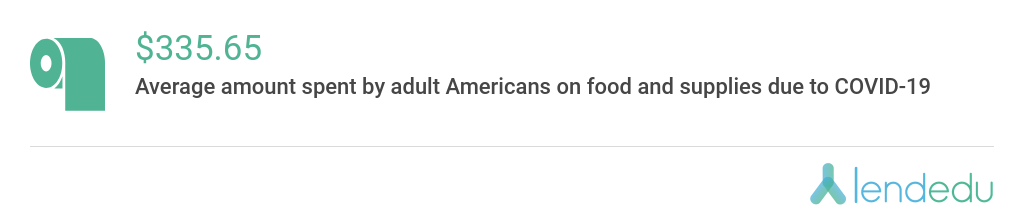
And when it came to the expenses that Coronavirus has brought on, whether it be toilet paper or T-bone steaks, we found that our respondents have spent an average of $335.65 on COVID-19-related expenses since the pandemic began to seriously impact the U.S.
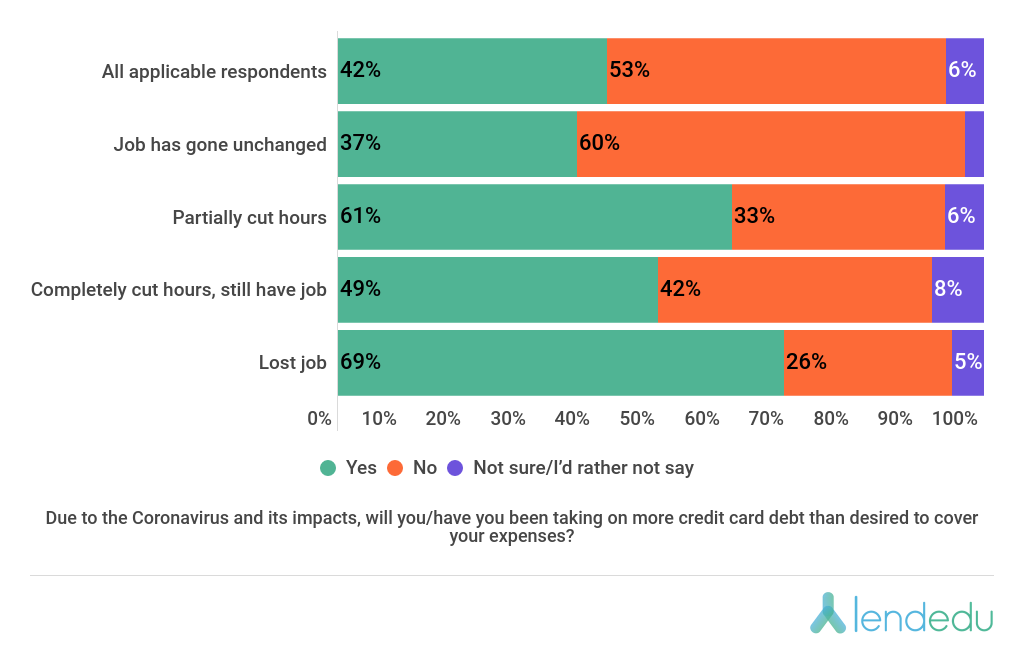
When expenses run high, many consumers need to access debt, typically via credit card, to finance their purchases. We asked poll participants with at least one credit card if they will be taking on more credit card debt than they would like due to Coronavirus.
Retirement Savings

Coronavirus has already had a crippling impact on the stock market, and it’s likely to get worse. For older Americans especially, there’s a pervasive fear that retirement nest eggs might get completely decimated as a result.

38% of our respondents indicated they are currently saving for retirement through something like a 401(k), Roth IRA, or high-yield savings account. We asked these folks about their concerns over their retirement savings due to COVID-19.
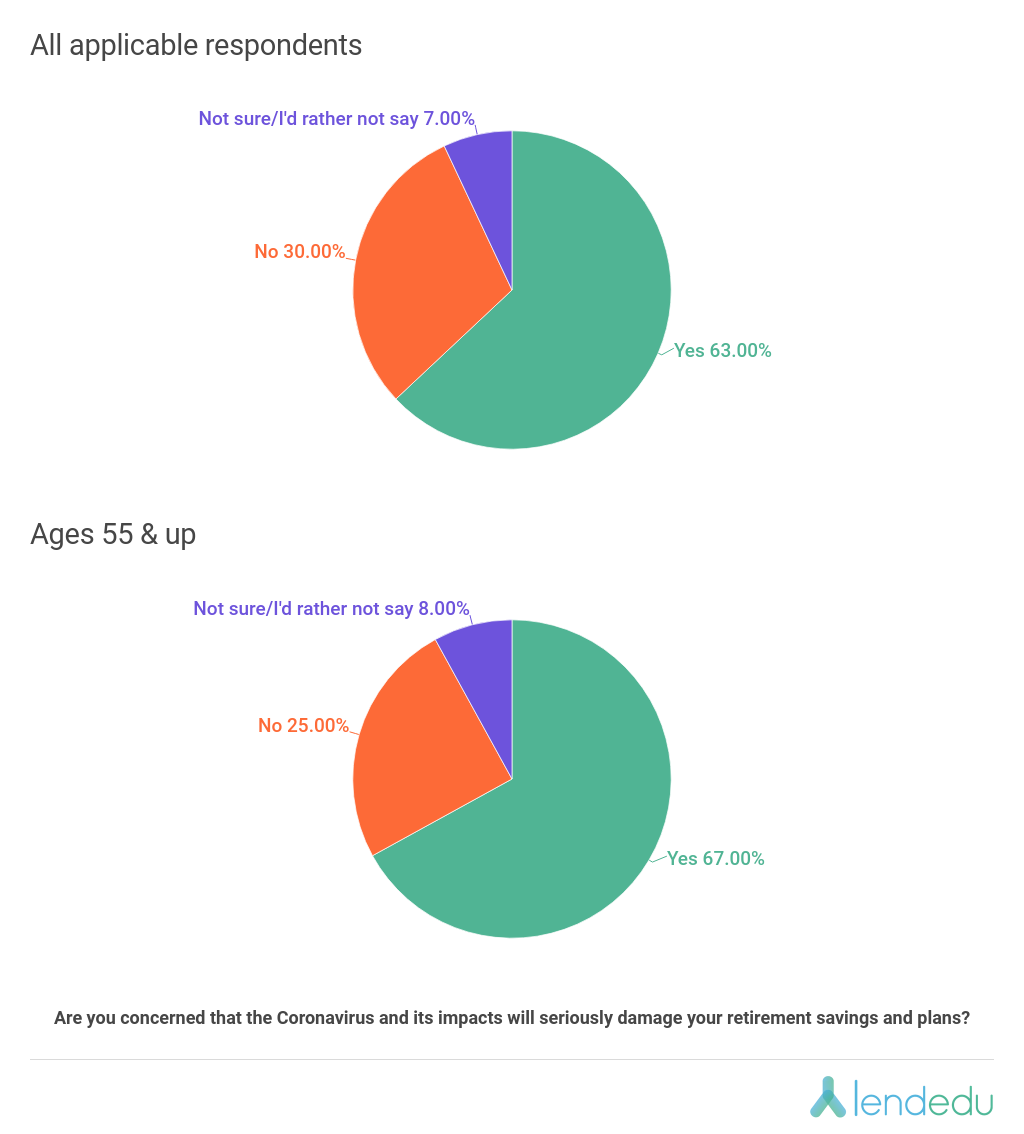
Within each age breakdown, the majority of Americans indicated that they are worried about their retirement savings due to COVID-19 and the ramifications it will have on the market.

Not surprisingly, this is especially true for older Americans ages 55 and up who are in the retirement red zone. 67% of this cohort are concerned about their retirement nest eggs.

Monthly Finance Payments (Mortgages, Student Loans, & Credit Cards)

With financial worries widespread and budgets tightening, we wanted to ask a few questions related to common financial obligations that Americans have, like payments for student loans, credit cards, or a mortgage.

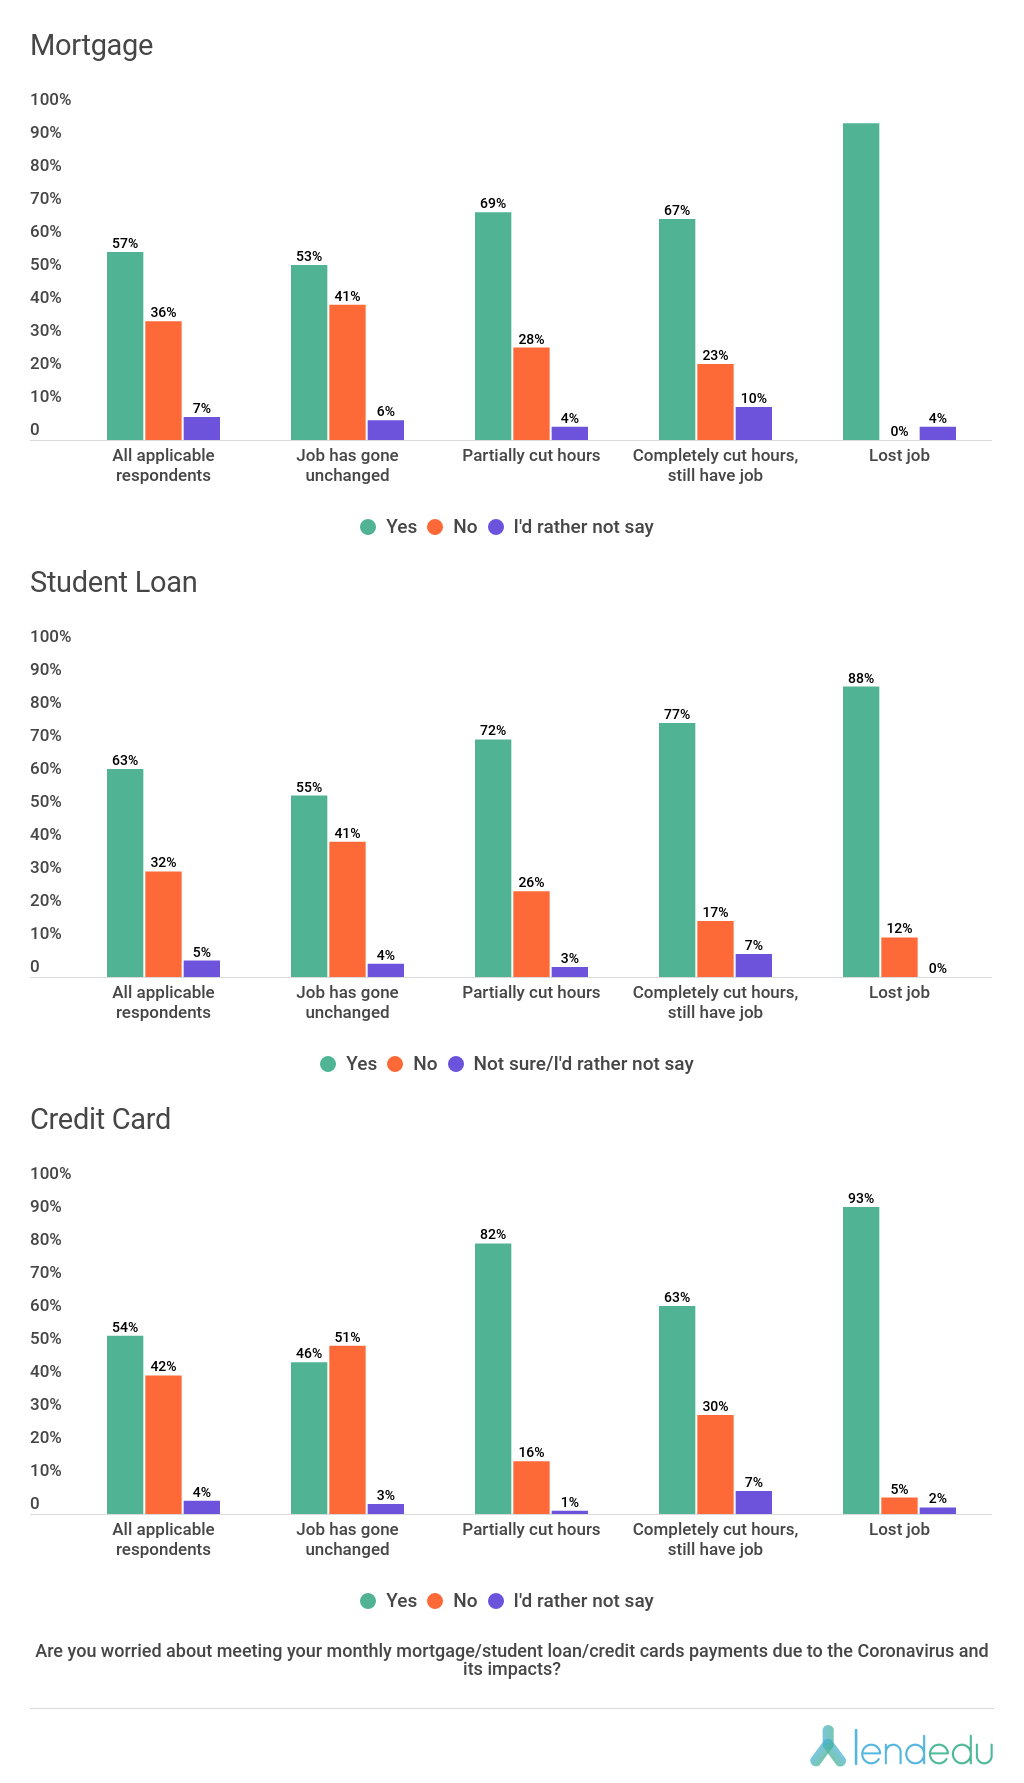
The following graphics are based on questions only asked to those respondents that stated they had a mortgage (35%), outstanding student loan debt (23%), and/or at least one open credit card account (63%).
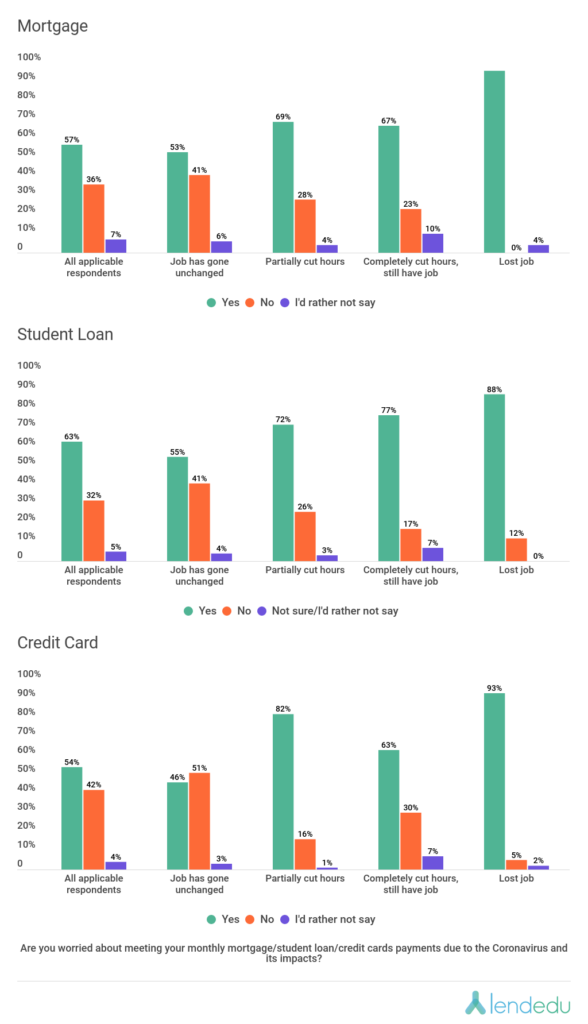
Many respondents are quite concerned about meeting their monthly financial obligations, whether they be related to a mortgage, student loans, credit cards, or all three.

Most alarming was how those adult Americans that lost their jobs due to Coronavirus answered these few questions. 96% of this group was worried about meeting mortgage payments, 88% about student loan payments, and 93% about credit card payments.

Widespread delinquency or default would have severe implications on the economy at large. In an attempt to combat this, we have seen the Trump Administration waive further accruing interest on student loans and suspend all evictions and foreclosures until April for FHA-insured mortgages.

Investments

While we did touch on investments as they pertained to retirement savings earlier, we wanted to dedicate a section to more active, personal investments that consumers make through personal brokerage accounts.

To describe the stock market in the last couple of weeks as turbulent would be an understatement. There have been sharp rises and drops (mostly the latter), and trading has actually been halted a few times in recent weeks on both the New York Stock Exchange and Nasdaq. The 15-minute halts happen when an initial steep drop in the market triggers “circuit breakers” that shut down trading.

27% of our poll participants indicated that they were actively invested in the market through a personal brokerage account when COVID-19 started impacting the U.S.

We asked this group a couple of questions in regards to playing the market.
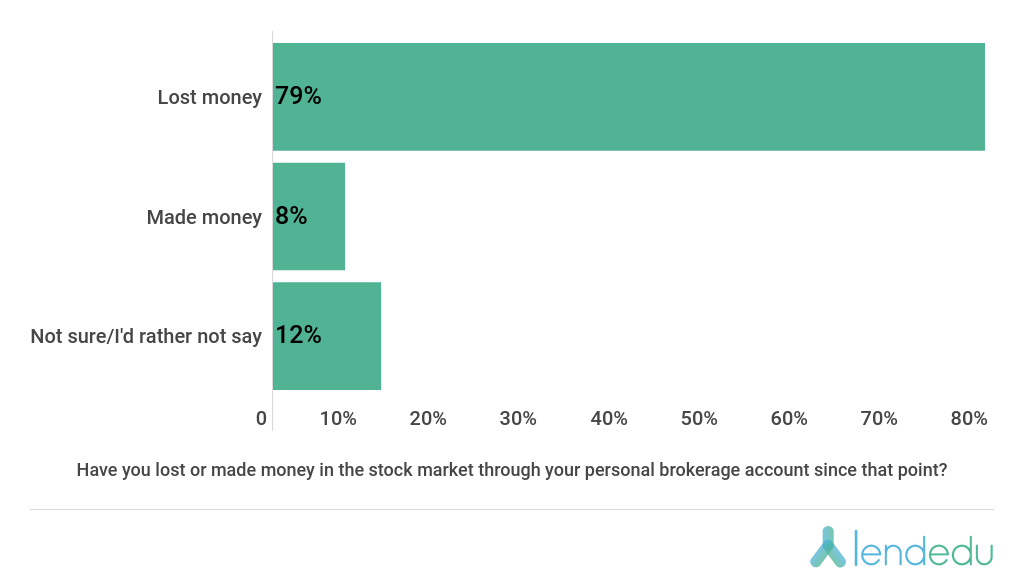
As expected, the vast majority of Americans who were making personal investments in the market when Coronavirus escalated got clobbered. 79% of respondents indicated they lost money, while just 8% made a profit.

And, how will these respondents invest moving forward as the pandemic continues to disrupt daily life?
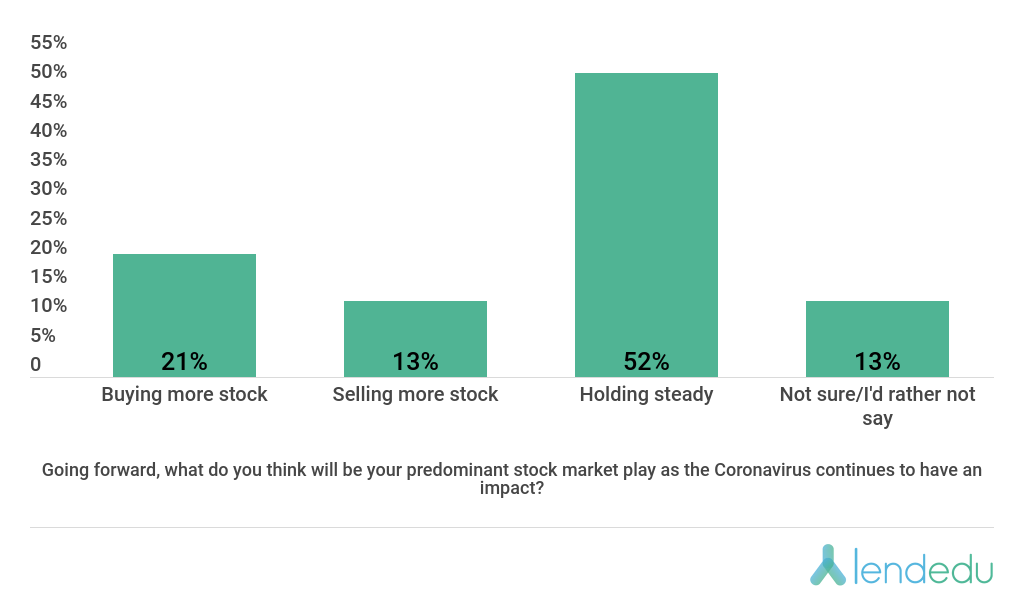
As it turns out, the majority of investors plan on riding out the storm and holding steady on their stock plays. Meanwhile, 21% plan on buying more during this crisis, while 13% will be looking to dump shares.

Full Survey Results

Continue Reading…

It’s too late to ‘re-evaluate’ your Risk Tolerance

By Michael J. Wiener

Special to the Financial Independence Hub

It’s not easy to know your true investment risk tolerance. Fred Schwed explained this problem wonderfully in his book Where are the Customers’ Yachts?:

“There are certain things that cannot be adequately explained to a virgin either by words or pictures. Nor can any description that I might offer here even approximate what it feels like to lose a real chunk of money that you used to own.”

Now that the stock market has tanked and investors are learning what it feels like to lose money, experts like financial planner Jonathan Bednar are saying “This is a great time to re-evaluate your true risk tolerance,” and “If you are nervous then you may be taking on more risk than you are really comfortable with and should rebalance into a more conservative portfolio.”

This advice amounts to “sell stocks while they are low.” The best time to figure out that you don’t have the stomach for a stock market crash is while prices are still high. It’s now too late to reduce your stock allocation without permanently locking in losses.

Easy to think you have high risk tolerance in a bull market

Unfortunately, when stocks are soaring it’s far too easy to convince yourself that your risk tolerance is high. So maybe we need a different strategy. Perhaps we should record videos of ourselves saying how we feel after stocks crashed, and set a calendar reminder to watch this video annually. The next time stocks are soaring again, maybe the video will help us lighten up on stocks while prices are still high. Continue Reading…

How to get through a stock market crash – and benefit from it

By Mark Seed

Special to the Financial Independence Hub

Unless you’ve been living under a rock, the stock markets have been a terrible mess.

On our Canadian side, we triggered market circuit breakers to halt trading in recent days.

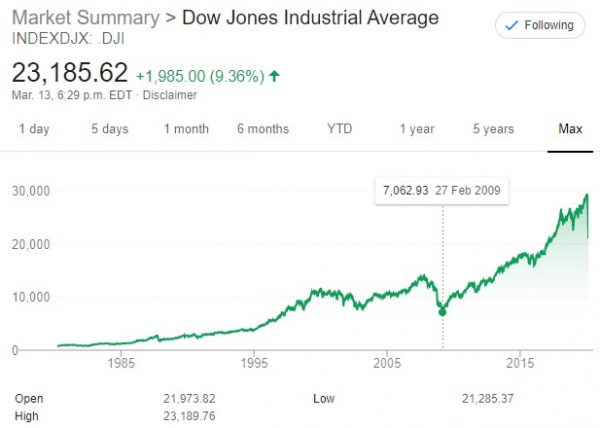
In the U.S., the stock market dropped thousands of points in rapid successive trading days and remains well into bear-market territory within just a matter of weeks. It’s as almost if the market jumped out of a plane with a faulty parachute and spiraled out of control to earth; only some mild turbulence kept it from a total free fall.

Dow March 14, 2020

All havoc, no sanity

These market dives in very short order made me reflect on my own investing journey and how I might be able to survive this stock market crash. For today’s post, here are my ideas on how to get through a stock market crash – and benefit from it.

1.) Learn from history – reset your expectations

A sudden stock market crash is quite unnerving, but I don’t think it’s a sign of imminent full-on financial collapse. At least history tells us so. You’ll see from the chart above, recent weeks have been very messy to say the least. But over many years of investing in equities, the chart actually looks like this:

I’ve highlighted near the bottom of the 2008-2009 Great Recession for reference.

Although it’s very difficult to wrap your head around this fact and behave accordingly, stock market history consistently tells us the financial markets do eventually recover. And, after they recover, looking back through time, they continue to deliver rather predictable long-term returns. Here is what the U.S. stock market has returned by the decade and from what:

A Wealth of Common Sense - Returns by Decade

Source: https://awealthofcommonsense.com/2019/12/where-have-all-the-stock-market-returns-come-from-this-decade/

Even near-term, our Canadian and U.S. stock markets have been a very good place to be to build wealth:

Index Proxy Fund 5-year return 10-year return Since inception
S&P/TSX (Canada) XIC 6.27% 6.77% 6.53% (2001)
S&P 500 (U.S.) IVV 11.65% 13.50% 6.15% (2000)

Source: iShares site, up to December 2019.

I firmly believe this is why you need to stay invested throughout a stock market crash.

What goes down will (eventually) go back up in time.

2.) Learn from history – buy when stocks are on sale

The fact that equity markets have done well over the last decade, let alone generations (despite the occasional very scary bump) should be a reminder that stocks remain a great long-term investment to build wealth. But as we all know by now, scary bumps can and do happen. As in now.

Dow since 1985 to March 14, 2020

This means selling stocks in a panic (also as in now) is probably not a wise move. Ideally, successful investing is about buying something at a low to modest price and watching that asset accumulate in value. That means staying investing like I mentioned above but that also means buying low, selling high (if you need to sell at all). When you sell after a market crash or a major correction you do just the opposite.

You and I both know by now we cannot control market swings. We can control our investing behaviour. We have no idea of when the market will swing nor by how much. We only know that it will.

The best time to buy stocks is when you were going to buy them anyway.

So, I believe, you should consider stock market crashes as a buying opportunity. I mean, a market correction or crash simply signifies stocks are on sale per se. Consider the following and your behaviours associated with these statements:

  • Would you panic sell your house if it dropped 20% in value in a few days or weeks?
  • Would you buy more gas for your car if it dropped 20% at the pumps?
  • Would you buy more groceries and toilet paper if it was on sale during the impending viral apocalypse?

You know your answer and I know yours too.

So why is the stock market different? 

Much has been written about buying in lump sums being somewhat more favourable than any dollar-cost averaging (i.e., buying-in slowly) during a market correction. To be honest, I don’t care what you pick. Just invest. 

As Jonathan Clements, a former Wall Street Journal columnist once said:

“If you want to see the greatest threat to your financial future, go home and take a look in the mirror.”

This implies that successful long-term investing is directed tied to your emotional fortitude and behavioural discipline. While poor investing decisions can and may very well occur from time to time, it’s important to learn from them. It is therefore imperative that investors recognize their behavioural pitfalls before committing to any decisions which can affect their investment goals.

One of my favourite, easy-to-read books on the subject of building wealth is targeted to millennial investors but applies equally to investors of all ages is If You Can. This book is designed for modern attention spans. It’s only 15-minutes of reading and gives you information you need to be a successful investor in a few pages.

You can read an overview of this book and download a FREE copy of it (yes FREE) here. 

3.) Learn from history – continue to improve

How high your returns could be (for a long-term stock market investor) over the next 30+ years is not really up for too much debate – based on market history. A 100% equity portfolio in the broad U.S. stock market is probably going to deliver close to 7% annualized (plus or minus a bit) and likely 3-4% in real returns (after inflation is factored in) in the coming decades.

I can say with more confidence that I will not find myself wealthier if I do not learn from my own investing history and continue to improve upon it over time.

I got a few reader emails over the last few weeks and I thought I would share them before I share my next steps in this current market correction for context – what I’m doing to improve. Emails adapted only slightly for posting. Continue Reading…

Sixth Sense or Nonsense? Removing intuition from the investment process

By Noah Solomon

Special to the Financial Independence Hub

In a recent newspaper article, a Canadian investment executive described why he chose not to incorporate artificial intelligence (AI) into his firm’s portfolio management process. His reasoning was based on the distinctively human ability to “read a room” and gauge the sincerity of corporate management teams, which cannot be replicated by a machine or algorithm.

Even if you believe that investment professionals possess this “sixth sense,” the simple fact is that it has not enabled them to produce superior results. According to the latest SPIVA (S&P Index vs. Active) Canada report card, over the past 10 years:

  • 91% of Canadian equity funds underperformed the TSX Composite Index
  • 97% of U.S. equity funds underperformed the S&P 500 Index
  • 100% of Canadian dividend-focused funds underperformed the TSX Dividend Aristocrats Index

Aside from the alleged ability to gauge the truthfulness of a person’s statements, there is another human characteristic that AI lacks. Unlike their human counterparts, AI algorithms do not have emotions or cognitive biases, which often lead to poor investment decisions.

We have met the enemy – and the Enemy is Us

The field of behavioural economics studies the effects of psychological, cognitive and emotional factors on the economic decisions of individuals and institutions. This field has produced countless studies that have conclusively demonstrated that when it comes to investment decisions, people harbour subconscious biases that result in suboptimal results. Moreover, these biases are not restricted to individual investors, but also permeate the decisions of professional managers and institutions. Continue Reading…