Tag Archives: investing

Starting is Hard, Doing it is Easy: 9 ideas to get you started

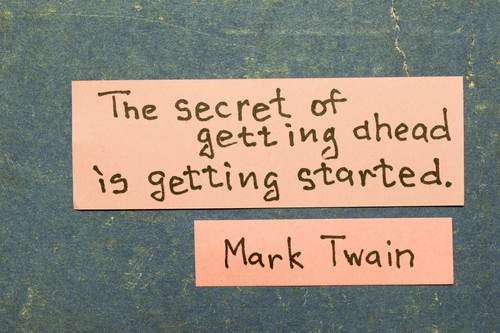
The secret of getting ahead is getting started - famous American writer Mark Twain quote interpretation with pink notes on vintage carton board

Starting is hard.  Doing is easy.  Even when it comes to the hardest things, starting is harder than actually doing the hard thing.

For the most important things, or the things where we have the most to gain, starting is the hardest thing.

If things are really easy to do, if they’re important, starting is hard.

Why is that?  Maybe we’re afraid of the consequences if we fail.  Maybe we’re afraid of the consequences if we succeed. After all, what would we fret about all day if all our “to do’s” were done?  Who knows where or why but as the proverb goes, “there is an enemy within.”

And if this enemy shows itself in areas which are important or where we have the most to gain or lose – it probably manifests itself as often as ever when it comes to the following:

  • relationships
  • personal fulfillment
  • exercise
  • diet
  • finances

These are all big areas where we could stand to gain a lot if we get things right!  And the longer we delay starting, the more it stresses us out – we sit in a paralytic trance, waiting for inspiration to hit us and it just never happens.

Perhaps breaking larger goals into smaller, more tangible steps might help, or at least it might trick you into doing something that sends you in the direction of progress.  While we don’t proffer advice in many of the above areas and in fact struggle as much as anyone,  we think the following smaller steps might help get you on the road to sorting out your financial house.  We’re sure there are more but here’s 9 to start:

9 smaller ideas to move you towards getting your finances in order

1.) Make sure you have an up-to-date Will, Power of Attorney designation and Health Directive.

2.) If you have people that depend on you, get insurance to make sure they’re taken care of if something happens to you – term life insurance is relatively cheap and pricing is fairly standardized.

3.) Pledge allegiance to the following mantra: “By far the most important thing I can do to ensure long term financial success is to live within my means.”

4.) If you have children, be sure to open a Registered Education Savings Plan (RESP) and invest enough to get the maximum Canadian Education Savings Grant (CESG)….free money from the government (need we say more?).

5.) If your company has a retirement savings program with matching contributions, it’s usually a good idea to contribute enough to get the maximum match.

6. ) Open a Tax Free Savings Account (TFSA).

7.) If you have investments, grab a pen and piece of paper and write down what you’re invested in, why and how much you pay annually in fees.

8.) If you can’t do number 7 without turning on your computer, educate yourself – we recommend the following Sensible & Concise Investment Books

9.) If these steps still seem overwhelming, find someone qualified and independent to help you.

Postscript –  if you’re interested in digging a little further into the enemy within, please read Steven Pressfield’s The War of Art.  He calls the enemy Resistance and it’s very real and very, very scary…..
graham-bodelGraham Bodel is the founder and director of a new fee-only financial planning and portfolio management firm based in Vancouver, BC., Chalten Fee-Only Advisors Ltd. This blog is republished with permission: the original ran late September here. 
 

Robb Engen’s 4 biggest Investing Mistakes

Learn from your mistakes - motivational words on a slate blackboard against red barn woodI was 19 years old when I first started investing. I diligently set aside money every paycheque, starting with $50 every two weeks and eventually increasing that to $200 per month, to save for retirement inside my RRSP. Sounds like I was off to a great start, right? Wrong!


Even though my intentions were in the right place, my first attempt at investing was a complete disaster. Here’s why: I didn’t have a plan

It’s good practice to save a portion of your income for the future, even at a young age. The problem for me was that I was still in school and didn’t have a plan – I had no clue what I was saving for.

I had read The Wealthy Barber and The Millionaire Next Door and so I knew the earlier I started putting away money for retirement, the longer I’d have compound interest working on my side, and the bigger my nest egg would be.

Unfortunately, I was saving for retirement at the expense of any other short-term goals, like paying off my student loans, buying a used car, or saving for a down payment on a house.

I didn’t have any short-term savings

Speaking of RRSPs, what was a 19-year-old kid doing opening up an RRSP when he’s only making $15,000 per year?

There were no real tax advantages for me to save within an RRSP when I was in such a low tax bracket. I’m sure I blew my tax refunds anyway, so what was the point?

Granted, the tax free savings account hadn’t been introduced yet, but I would have been better off using a high interest savings account for my savings rather than putting money in my RRSP.

I didn’t have a clue about fees and tracking performance

Like a typical young investor I used mutual funds to build my investment portfolio. I was encouraged by a bank advisor to select global equity mutual funds because, as I was told, they would deliver the highest returns over the long term.

What the bank advisor didn’t tell me was that the management expense ratio (MER) on some of those mutual funds can be 2.5 per cent or more, and high fees will have a negative impact on your investment returns over the long run.

Bank advisors also don’t tell you which benchmark these funds are supposed to track (and attempt to beat) so when you get your statements in the mail it’s impossible to determine how well your investments are doing compared to the rest of the market.

I drained my RRSP early

I didn’t have a good handle on my finances in my 20s and often resorted to using credit cards to get by. Without a proper budget in place, and no short-term savings to fall back on in case of emergency, I had no choice but to raid my RRSPs to pay off my credit-card debt and get my finances back on track.

Taking money out of my RRSP early meant paying taxes up front. Withdrawals up to $5,000 are subject to 10 per cent withholding tax, while taking between $5,000 and $15,000 will cost you 20 per cent, and withdrawals over $15,000 will cost you 30 per cent.

Your financial institution withholds tax on the money you take out and pays it directly to the government. So when I took out $10,000 from my RRSP, the bank withheld $2,000 and I was left with $8,000. In addition to the withholding tax, I also had to report the full $10,000 withdrawal as taxable income that year.

While I can’t argue with my reasons for selling, my dumb decisions beforehand cost me a lot of money and left me starting over from scratch.

Final thoughts

We all make investing mistakes – some bigger than others. If I had to do things over again today I would have done the following:

  1. Create a budget – A budget is the foundation for responsible money management. Had I used a budget and tracked my expenses properly from an early age I would have lived within my means and kept my spending under control.
  2. Open a tax free savings account – Yes, the TFSA wasn’t around back then but for today’s youth it makes much more sense to save inside your TFSA instead of your RRSP like I did. You can put up to $5,500 per year inside your TFSA and withdraw the money tax free. You contribute with after-tax dollars, so you won’t get a tax refund, but you’ll likely be in a low tax bracket anyway, so contributing to an RRSP won’t give you much of a refund either.
  3. Make a financial plan – We all have financial goals and even at a young age I should have identified some short-and-long term priorities to save toward. I’d take a three-pronged approach where I’d use a high interest savings account to fund my short term goals, my TFSA to fund mid-to-long term goals, and eventually open an RRSP to save for retirement. No doubt I’d be much further ahead today if I took this approach earlier in life.
  4. Use index funds or ETFs – Now that I understand how destructive fees can be to your portfolio, I’d look into building up my investments using low cost index funds or ETFs. The advantage to using index funds is that you can make regular contributions at no cost while achieving the same returns as the market, minus a small management. Some brokers also offer free commissions when you purchase ETFs.

Did you make similar mistakes when you first started investing? How did you overcome them?

 RobbEngenIn addition to running the Boomer & Echo website, Robb Engen is a fee-only financial planner. This article originally ran on his site on August 7th and is republished here with his permission.


Capital gains tax is one of the lowest you’ll ever pay

Hand with pen pointing to GAIN word on the paper - financial and investment conceptsThere are three forms of Investment Income in Canada: Interest, Dividends and Capital Gains. Each Is taxed differently. Here’s a reminder of how smart investors use their knowledge to taxation rates, especially tax on Capital Gains, to protect their returns.

With stocks, you only pay capital gains tax when you sell or “realize” the increase in the value of the stock over and above what you paid for it. (Although mutual funds generally pass on their realized capital gains each year.)

Several years ago, the Canadian government cut the capital gains inclusion rate (the percentage of gains you need to “take into income”) from 75% to 50%. For example, if an investor purchases stock for $1,000 and then sells that stock for $2,000, then they have a $1,000 capital gain. Investors pay Canadian capital gains tax on 50% of the capital gain amount. This means that if you earn $1,000 in capital gains, and you are in the highest tax bracket in, say, Ontario (49.53%), you will pay $247.65 in Canadian capital gains tax on the $1,000 in gains.

The other forms of investment income are interest and dividends. Interest income is 100% taxable in Canada, while dividend income is eligible for a dividend tax credit in Canada. In the 49.53% tax bracket, you’ll pay $495.30 in taxes on $1,000 in interest income, and you will pay $295.20 on $1,000 in dividend income.

Three capital-gains strategies

Continue Reading…

Investing isn’t about hitting home runs but staying out of trouble

MESA, AZ - OCTOBER 18: Ryan Lavarnway, a top prospect for the Boston Red Sox, hits for the Peoria Javelinas in an Arizona Fall League game Oct. 18, 2010 at HoHoKam Stadium. Lavarnway went 1-for-4.People are often surprised when we say that successful investing does not mean you have to “beat the market.” Instead, successful investing is simply that which allows you to meet your financial goals.

Trying to hit “home runs” by picking hot stocks before they jump or timing market swings are activities more aligned with speculating than investing and may actually decrease your chances of meeting your goals. Ultimately, success is less about swinging for the fences and more about staying out of trouble.

Unfortunately, trouble can manifest itself in many ways. The most common troubles that can trip investors up are:

High and hidden fees

Canadian mutual funds have among the highest fees in the world – high fees detract from investment performance and over a long period of time can significantly erode your savings nest egg.

Lack of diversification

Continue Reading…

Stop believing real estate has magical investment powers

Beautiful view of Vancouver, British Columbia, Canada
Expensive Vancouver, BC

By Steve Lowrie, Lowrie Financial

Special to the Financial Independence Hub

If you found yourself on the high seas, and the captain and crew were battening down the hatches, what would you do? Depending on how fast they were scrambling, you might at least make sure your life preserver was within reach.

If the Canadian real estate market were an ocean liner, recent government words and deeds have sent some pretty solid warning shots across the bow – especially for properties in the Greater Toronto and Vancouver regions. Real estate investors who may have forgotten the essential rules of self-preservation would be wise to consider the following:

In a June announcement, Bank of Canada Governor Stephen Poloz warned: “The pace of house price increases in Toronto, and especially Vancouver, is unlikely to be sustained, given the underlying fundamentals.”

Several provincial governments have been looking for ways to manage their real estate markets. For example, this July Globe and Mail article noted that British Columbia was trying to “cool the Vancouver market” by adding a 15 per cent transfer tax on property purchases made by international buyers. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.