You can also find some of the factoids from the survey here.
In case you missed the kickoff on Sunday, we’re now well into the seventh annual Financial Planning Week, which started on November 15th and runs until November 21st. As the link reveals, there’s something every day on the program.
On Thursday night, the Canadian ETF Association (CETFA) celebrated the 25th anniversary of exchange-traded funds, the first of which began trading in Toronto before trading anywhere else in the world: the TIPs or Toronto 35 Index Participation Units were later merged into the iUnits S&P/TSE 60 Index ETF.
As this link observes, the actual launch date was March 9, 1990. That was almost a full three years before the first ETF was listed in the United States: the SPDR S&P 500 ETF (SPY) on January 29, 1993.
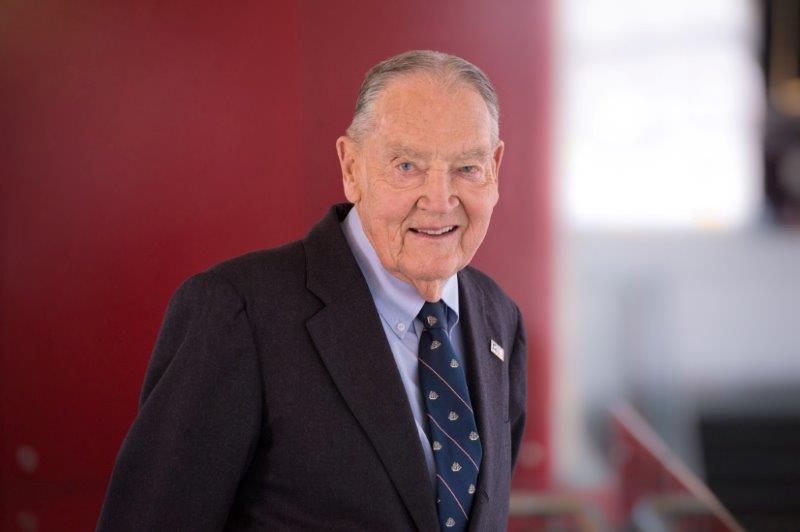
At the gala event in Toronto commemorating this milestone, CETFA’s new chair –Vanguard Investments Canada Inc. managing director Atul Tiwari, who recently replaced outgoing chair Howard Atkinson — passed along the following remarks by Vanguard founder, the legendary John Bogle:
John Bogle (courtesy of Vanguard)
“Next week marks the 40th anniversary of the first retailindex mutual fund. At first it was a flop. Only $11 million received. It was nine years before a competitor created one. At the time indexing was only 1% of equity fund assets. They have grown since then. Today indexing is fully 34% of equity fund assets… broad market ETFs remain sound investments just as long as investors do not trade them. Staying the course with less exciting low-cost, broad-market index funds may not be the greatest investment strategy ever devised but the number of strategies that are worse is infinite.”
In it, Emeritus Retirement Solutions’ Doug Dahmer — a frequent Hub contributor in the “Decumulation” section — points out that the strategies used in Wealth Accumulation are quite different than those needed once you reach the De-Accumulation or “Decumulation” stage. One of his colourful phrases is “dollar cost ravaging,” which is the opposite of “dollar cost averaging.”
The blog ends with links to the four earlier instalments this week.
As indicated in this space on Monday, MoneySense.ca is running a week-long special series of blogs, including daily ones by Yours Truly, recounting the most common mistakes we all make in saving, paying down debt, investing, retiring and in selling our homes.
Or click on the enigmatically titled “Millions of dollars lost in bike spokes as children.” That’s a reference to children using baseball or hockey cards a noise-makers on their bicycle wheels, oblivious to the possible future value of their Wayne Gretzky or Mickey Mantle rookie cards.
This video, featuring Emeritus Professor of Finance Elroy Dimson of the London Business School, is a little more off the beaten track than the earlier ones focused on stocks and bonds. It looks at how “emotional assets” or “collectibles” (like art or stamp collecting)can generate some “psychic income” from the sheer pleasure of enjoying art on your walls or fine wines.
But surprisingly, historically the investment returns from collectives have also been more than decent. Going back between 1900 and 2012, collectibles have generated nominal annual returns of 6.4% and real (net of inflation) returns of 2.4%. That means they’ve actually beaten treasury bills and even such alleged inflation hedges as gold, silver or diamonds. However, they have not performed as well as equities.
The conclusion? If you enjoy the “psychic income” and pleasure of collectibles, that should be return enough but if you also make money from collecting things you’re interested, that should be considered a bonus.


 Posted By
 Here’s my latest Financial Post blog, titled More than two thirds of Canadians worry ‘a lot’ about money, but 69% still don’t have a plan.