Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

Real Estate Investing: The good and bad of investing in real estate

By David Miller, CFP, RFP

Special to the Financial Independence Hub

Real estate can be a differentiator in a diversified investment portfolio. But when you watch the pundits in the media and certain TV network shows, as seen on HGTV, buying, flipping or renting a property seems like a sure way to increase your income or get rich quick. As glamourous as it seems when you take a sledgehammer to a useless wall to ‘open up the space’, the reality of making it a marketable investment is often much more daunting. What really is daunting is the sheer number of options you have when it comes to investing in real estate, and the obvious question is:

Does it make financial sense to add real estate to your portfolio?

The Positives

Real Estate does make sense in most investment portfolios but let us back up a little bit here and provide some context:

What are the primary reasons people choose real estate as an investment?

There is something reassuring about investing in real estate, as in the case of owning a rental property. You own a tangible asset and you may feel like you can see the value and the risks just by walking through the property. You may own your home, and assuming you are mortgage free, brings an incredible feeling of security and freedom.

Real estate investing can offer a stable, reoccurring income; after all, ‘who doesn’t pay their mortgage or rent?’ It also carries a fairly high certainty of a higher value over the long term; after all, “they are not making more land” (unless you’re in the South China Sea or Dubai). These are two common positive arguments.

If you look specifically at Canada, there can be times when your rate of return can be incredibly high. We experienced this with Calgary’s real estate boom from 2005-2007. The Greater Toronto Area and Greater Vancouver area from 2015-2018 have seen incredibly high growth and price increases that have been covered extensively through the media.

Real estate investing provides an interesting option that is not directly tied to overall stock market risk, which can provide you with increased diversification. Whether the stock market goes up or down, your real estate price may move independently.

The wealthy endowment funds, private pensions, institutional money and the Canada Pension Plan invest heavily in real estate, private equity and infrastructure projects that average Canadian investors either don’t know about, can’t invest or don’t invest into.

To summarize, the benefits of a real estate investment are that it is a tangible, generally stable income producing, ‘always goes up’ investment and offers other benefits not seen in the stock market. Ready to jump in with both feet? Not so fast. There are some serious pitfalls to understand and multiple options to choose from.

How can I invest into real estate?

  • Buy a rental property (putting at least 20% down)
  • Buy a commercial building
  • Real Estate Investment Trusts (REITs)
  • Exchange Traded Funds (ETFs) of REITs
  • Mutual funds specializing in real estate
  • Private equity or debt (Mortgage pools/investment corps)

Primary Issues

Price Risk

Can real estate values fluctuate? The real answer is yes. Nationally, Canadian housing prices reduced by 4.9% on average in 2018, the worst performance since the 2008 financial crisis. Toronto and Vancouver skew the average price to high side, but even they are starting to fall off their 2017/18 highs and there are obvious concerns of a bubble bursting.

Prices for real estate are difficult to gauge as every property is different and value is in the eye of the beholder. To sell your property, you likely need to employ a realtor to get a starting price and you need to find someone else who agrees on the price to buy. Real estate negotiations can go awry quickly, which causes further delays regarding the liquidity. For this service, there is a sales cost paid to the realtor, usually 7% of the first 100,000 and 3% after, although this can be sometimes negotiated.

In an example of how poor the Calgary commercial real estate market is; this*is an article that explains how the city of Calgary is losing over $300 million in tax revenue every year as downtown core commercial property values have decreased by a collective $12 billion. This is an example of how real estate values can fluctuate to the downside and how unstable a source of income a real estate investment could be.

See the chart below for the relative volatility of the selected Calgary, Toronto and Vancouver markets when compared with the US Equity and Canadian Equity markets. While the annual volatility in the S&P 500 and TSX has been much higher relatively, this chart shows that you could lose out if you sell your real estate holding at the wrong time or pick the wrong city or neighbourhood to invest in.
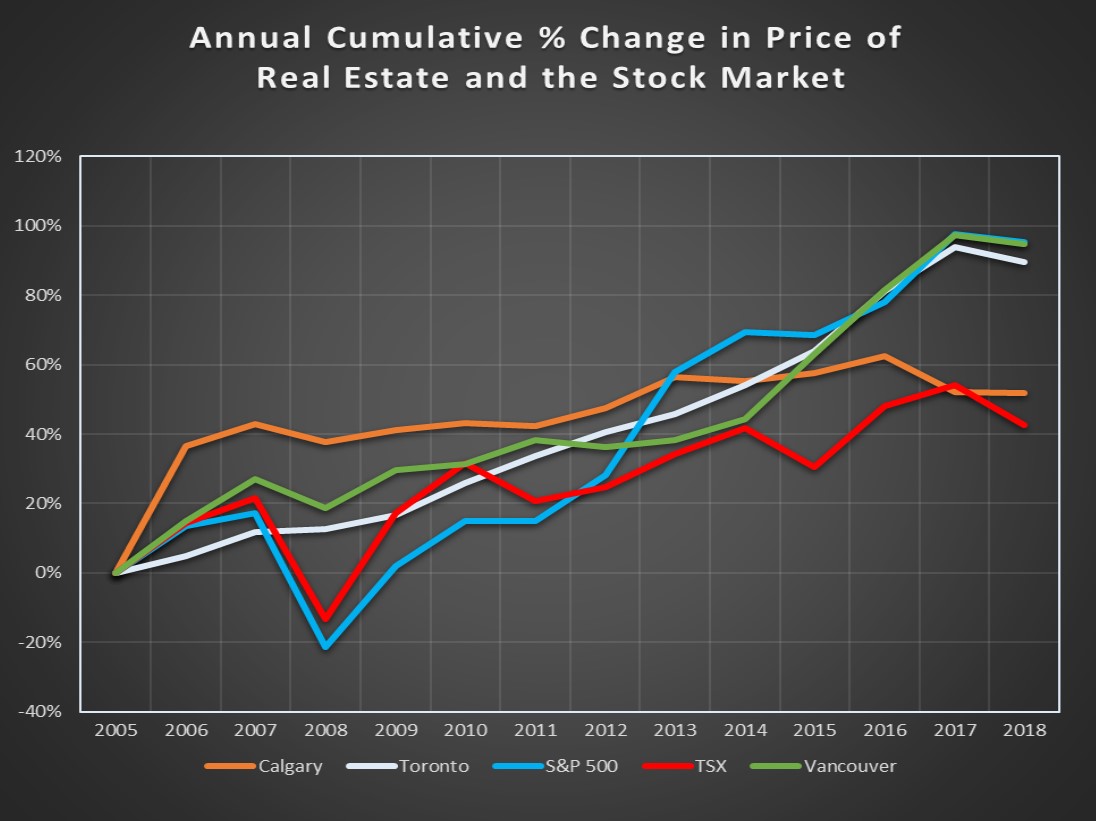
 

Calgary data via CREB Monthly Average Sale Price “Attached, Detached, Apartment”, Jan 2005 to Dec 2018. Vancouver Data via CREA.ca HPI Tool Greater Vancouver Composite historical price data Jan 2005 to Dec 2018. Toronto Data via CREA.ca HPI Tool Greater Toronto Composite historical price data Jan 2005 to Dec 2018. TSX data via tmxmoney.com price history. S&P 500 data via http://www.multpl.com/s-p-500-historical-prices/table/by-year. The chart above only looks at price change and does not factor the effects of leveraging or reinvestment of interest or dividends.

Liquidity Risk

Liquidity refers to how quickly you can get your money out if you change your mind about your investment. Are you prepared to invest money into a residence only to find out it’s a money pit? What happens when you struggle to sell it when the market turns, and you could really use the extra money for something else? What if there is an emergency and you need those funds and there is no liquidity? If you are buying a stock or ETF on a major open market, the level of liquidity can be measured in volume of shares bought or sold and shares usually change hands instantaneously. While investing in stocks should be a long-term investment, at least you have the option to get out at any time almost instantly. The same is generally true in real estate; however, the liquidity premium is significantly higher. Continue Reading…

Enable, don’t label … but whatever you do don’t call them ‘seniors’!

By Yvonne Ziomecki, HomeEquity Bank

Special to the Financial Independence Hub

When you are a marketer you tend to look at advertising through a different lens than everyone else – sometimes you are critical, sometimes curious, and sometimes you just admire the genius.  But it’s hard to assess your own advertising through the same lens, especially when you are in your mid forties and the product you market is for people who are retired.  That’s when you call for help!

Last summer our company HomeEquity Bank, provider of CHIP Reverse Mortgages, launched new advertising campaign through a series of humorous ads developed and based on research insights, addressing the fact that older Canadians see themselves as active and able and completely in control of financial decisions related to their home.

Specifically: staying in the home they love.  Our research showed that 93%+ of older Canadians want to age in place.  We also learned that 80% of older Canadians don’t want to be called ‘Seniors’ and most prefer no labels to describe them or their peer group.

In order to better understand if our ads were hitting the mark we engaged the neuroscience research firm Brainsights to study the unconscious brain activity of 300 Canadian Boomers. Research participants were presented with approximately 1 hour of advertisements including our ads, other ads, movie trailers, promotional videos, etc.  Brainsights analyzed participants’ responses to all the content they saw. The findings revealed not only that many marketers were engaging in unconscious age bias, but also that Boomers were pushing back against offensive labels and aging stereotypes.

Research revealed 4 insights to help marketing resonate with Boomers:

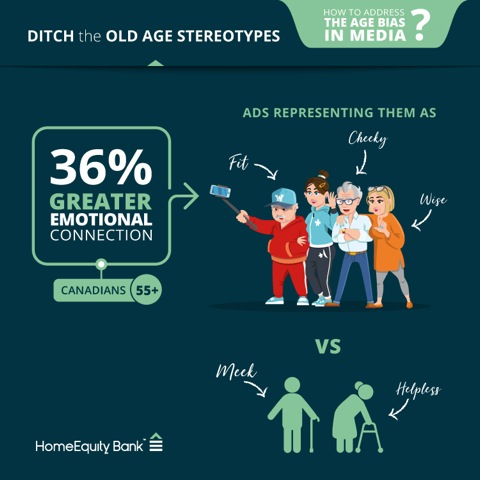
•  Say goodbye to old age stereotypes. Today’s Boomers see themselves as being cheeky, mischievous, adventurous and capable. Old age stereotypes depicting 55+ Canadians as frail and fumbling will miss the mark. Continue Reading…

Alternative assets in ETFs and mutual funds, including a new one from Franklin Templeton


Alternative asset classes like private equity and real estate have long been in vogue with pension funds, institutional investors and some high-net-worth individual investors but the pickings have been slim for retail mutual fund investors. Now, Franklin Templeton Investments Canada has introduced the Franklin K2 Alternatives Fund.

The company says its new mutual fund, announced on Monday, March 11, uses “a multi-strategy approach in seeking to dampen volatility and offer downside protection, while providing added diversification and low-correlation to asset classes typically held in a traditional portfolio.

Franklin Templeton Canada Duane Green pointed to the unpredictable market environment of the past year and said “investors are looking to reduce volatility and protect capital … Our alternatives fund addresses these investor needs and combines the benefits of a sophisticated solution with the liquidity, convenience and fee transparency of a mutual fund.”

In a piece this weekend in the Financial Post, which mentioned the new Templeton fund among others, investing reporter Victor Ferreira said Canadian retail investors looking for exposure to hedge-fund like strategies that can involve leverage and short-selling are being inundated with new options, following a rule change in January. At least six firms have brought so-called “liquid alternative” products (some of them ETFs and some of them mutual funds from firms like Mackenzie and C.I. Funds) to market since regulations barring them from doing so were lifted at the beginning of 2019. Prior to the regulations being altered, he said, only a few firms were able to offer such products after applying for exclusions.

As the Post pointed out, some alternative assets — notably real estate and private equity — are seldom easily liquidated if you need some cash. It cited a 2018 Scotiabank report that projects the Canadian market for these kind of products could grow to be worth $20 billion.

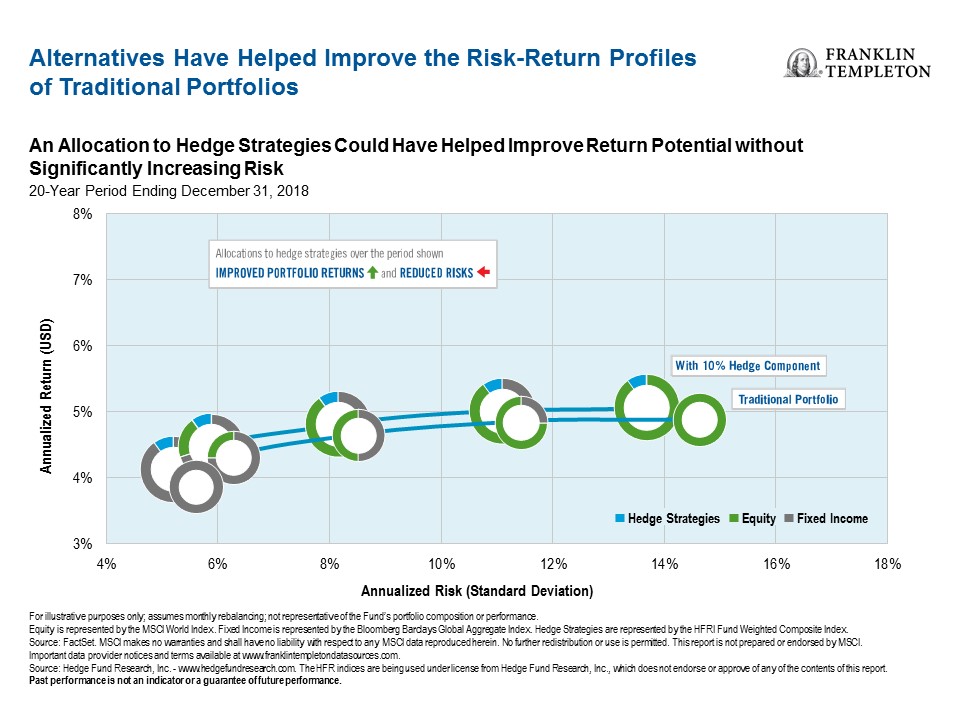
According to Franklin Templeton marketing documents, alternative asset classes or hedging products can improve return potential without significantly increasing risk. It describes three possible “buckets” investors can choose from: traditional Equity Beta or “Risk On,” traditional Bond Beta or “Risk Off” and Alpha Alternatives, or “Risk Uncertain.” It said Alternative Assets can also protect client assets during declining equity markets. In addition, Alternatives have “held up well in weak bond markets.”

Green told the Post that the new Franklin Templeton fund gives investors access to three different strategies: the fund will index 50 hedge funds and aim to replicate their returns. On the long/short side, the fund will also identify the most popular stocks that alternative asset managers are buying and take long positions in them while shorting S&P 500 or futures contracts and any individual names it deems unattractive. Thirdly, the fund will target risk premia.

Or, in the language used in the Franklin Templeton press release: Continue Reading…

How federal housing policies could impact first-time homebuyers

By Jordan Lavin, Ratehub.ca

Special to the Financial Independence Hub

For a little more than a decade, the Federal Government has been making policies that make it harder to buy your first home in Canada.

It’s hard to blame them. The great recession of 2008-09 was principally caused by a crash in the U.S. housing market which, in turn, had been caused by lax mortgage lending standards. Hundreds of thousands of people bought homes they couldn’t really afford, and were later foreclosed on or forced to sell. Left behind was a glut of housing inventory and an equal glut of people who had lost everything. The ripple effect was felt throughout the world, including here in Canada.

Fortunately, the mortgage problem was isolated to the United States. But the repercussions hit Canada hard, and interest rates fell to unprecedented lows as a response to the worsening economic situation. During the recovery, mortgage rates in Canada continued to fall and house prices quickly rose. In hot markets like Vancouver and Toronto, the average price of a home nearly doubled between 2010 and 2016.

All this left government officials on this side of the border wondering if it was possible for the mortgage and housing market to fail here. With the compounding worry of a housing market crash – what if prices went back down as quickly as they had gone up? – they began making new policies with the goal of making it more difficult for Canadians to qualify for a mortgage, especially if that mortgage were to be insured by the Canada Mortgage and Housing Corporation (CMHC).

Among the changes: Limiting amortization length for insured mortgages to 25 years; Limiting CHMC insurance to homes purchased for under $1-million only; Establishing a minimum down payment of 5% and then increasing the minimum for homes over $500,000; and expanding a “stress test” to eventually force all mortgage borrowers to qualify at a higher interest rate than they would actually pay.

This cocktail proved poisonous for first-time homebuyers. High house prices, harder qualification criteria and lower earning potential forced first-time homebuyers to get creative, finding new ways to afford homes.

Today, the government is looking at two new policy changes that could have an impact on first-time homebuyers.

A return to 30-year insured mortgages for first-time homebuyers

Currently, the longest you can take to pay back an insured mortgage (mortgage insurance is usually required when you have a down payment of less than 20%) is 25 years. But one policy change the government says they’re looking at is increasing that limit to 30 years.

This is a boon to affordability, at least at the qualification level. Ratehub’s mortgage payment calculator shows that the monthly payment on a $500,000 mortgage at today’s best rate of 3.29% will be $2,441 when amortized over 25 years, or $2,181 when amortized over 30 years. Since mortgage affordability is based on a fraction of your income, a lower payment equals a higher purchase price you can qualify for.

But there’s a significant downside. The obvious is the additional 5 years of mortgage payments later in life. If you’re over 35, signing a new 30-year mortgage could keep you making payments into retirement. Continue Reading…

Should you start an E-commerce business?

Image via Pexels

By Gloria Martinez

Special to the Financial Independence Hub

Do you want a job where you can work from home, set your own hours, and earn a virtually limitless amount of money? If you answered “yes” and you’re decently tech-savvy, e-commerce could be the perfect fit for you. E-commerce can be any type of online business transaction, but most of the time, it refers to online shopping.

Why e-commerce?

Skyrocketing rents and a shift toward online shopping has brought about the demise of many brick-and-mortar businesses. Unable to compete with the low prices of big-box retailers, mom-and-pop shops are shuttering their doors. Even big-box brands are suffering as their limited inventory fails to keep up with ecommerce giants like Amazon.

With e-commerce, entrepreneurs can avoid these small-business pitfalls. It’s no mystery that hosting a website is far cheaper than maintaining a brick-and-mortar store, and the rise of dropshipping has rendered the need for massive warehouse space obsolete.

Is e-commerce profitable?

E-commerce isn’t a guaranteed path to success by any means. Countless online stores open and close without registering a blip on consumers’ radar. However, stores that do well do very well. An analysis from RJMetrics found a typical ecommerce store generates $63,000 in monthly revenue by its third month. By year three, that number jumps to $352,000 a month.

How to make money in e-commerce

Setting up a successful e-commerce site requires three things:

1.) An in-demand product

Every e-commerce store needs a niche, but it can’t be just anything. Your niche needs to be something shoppers actually want to buy. However, it shouldn’t be the hottest thing on the market either or it will impossible to stand out.

Complete keyword research to find what consumers are searching for, then narrow down your search until you find a micro-niche with a profitable market. Make sure it’s a product you’re genuinely interested in. If you’re selling something you know nothing about, you’ll have a hard time making a compelling pitch to potential customers.

Once you’ve found your niche, have a plan to keep your inventory fresh. If your store has limited offerings, shoppers won’t keep coming back for more. Rotate your inventory on a schedule that makes sense. If you’re dropshipping wholesale clothing, change your inventory with the seasons. If you’re selling video games, make sure your site reflects the newest releases. Remember: It’s much easier to sell more stuff to an existing customer than it is to find new ones.

2.) A great website

Nothing kills an e-commerce site faster than a website that’s not user-friendly. Resist the urge to DIY your site to save money. A clunky website will lose you far more money than it saves. A good e-commerce site instills trust in shoppers, makes products incredibly easy to find, and executes an effective sales funnel. Web Designer Depot gives an excellent rundown of what goes into creating a high-quality ecommerce site. Continue Reading…