Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Where did the Retirement idea come from?

I was reading an article on retirement in The Atlantic. The article discussed the earliest concept of retirement, dating back to Otto von Bismarck of Prussia in 1881.

The concept was to provide financial support to “older members” of society. The idea was radical because people did not retire: if you were alive you worked. At the time the majority of people were employed in agriculture to feed the masses.

The struggle for payment continued for 8 years and finally with pressure from the socialists, legislation was introduced for the state to take care of those disabled from work. Social security was later introduced for those over 70 years old; however, 70 was well above life expectancy at the time.

Soldiers were paid pensions for years prior to social security; however, virtually all worked after their military service. In the late 1800s pensions were paid to many public servants in major US cities  and in 1875 American Express started to offer pensions,  followed by major industrial companies that started paying pensions in the early 1900s.

US Social Security in 1935

All this culminated with the Social Security Act of 1935, with a retirement age of 65 and a life expectancy of 58. Research at the time suggested mental capacity started to decline at age 60 and it was time to pass work onto the younger generation. In Canada, the Old Age Security Act was passed in 1927.

It is interesting to see the history of retirement,which was designed to not pay or pay very little since no one was supposed to live past the age of qualification. In the 1960s people started to live past Social Security age and had the money/savings to actually retire. This led to the problem we see today, which is the strain to fund payouts from government pension plans.

This problem will need to be addressed before it becomes a problem for our children, but that is a discussion for another day. You might have seen this before on this blog, so here again financial and lifestyle planning are critical to ensuring that you enjoy retirement on your terms: expecting anyone else to take care of you, even the government, is not wise.

People are living longer and want to work longer

Our current reality is that people are living longer and want to work longer. You might say we are going back in time. Continue Reading…
Top retirement advisor tips to get the most from your savings

All investments come with a mix of risk and potential reward. The greatest danger comes when you understand the mechanics of an investment, but you’re missing some of the details. Your understanding of the potential reward can make you greedy, while the gaps in your knowledge limit your natural, healthy sense of skepticism.

When it comes to retirement, you should be long-term focused, which takes a lot of the guessing and game playing out of the equation. The best retirement plan you can have is to start saving as early in your working career as possible. You then invest a steady or rising amount of that money in the stock market every year. When you follow this plan, you automatically profit from dollar-cost averaging. You will automatically buy more shares when prices are low, and fewer shares when prices are high.

Continue reading for more retirement advisor tips and strategies for saving.

Retirement advisor tip: Use an RRSP For Retirement

You have to learn a lot of things to become a successful investor, and few people learn them all in any logical progression. Instead, most of us move from one subject of interest to another, with a lot of zigs and zags in between.

But one tip is clear: If you want to pay less tax on your investments while you’re still working, investing in an RRSP (Registered Retirement Savings Plan) is the way to go.

To cut tax bills, RRSPs are a great option. RRSPs are a form of tax-deferred savings plan. RRSP contributions are tax deductible, and the investments grow tax-free. (Note that you can currently contribute up to 18% of your earned income from the previous year. March 1 is the last day you can contribute to an RRSP and deduct your contribution from your previous year’s income.) When you later begin withdrawing the funds from your RRSP, they are taxed as ordinary income.

Registered Retirement Income Funds (RRIFs) are also a great long-term retirement investment planning strategy

Converting your RRSP to a RRIF is clearly one of the best of three alternatives at age 71. That’s because RRIFs offer more flexibility and tax savings than annuities or a lump-sum withdrawal (which in most cases is a poor retirement investing option, since you’ll be taxed on the entire amount in that year as ordinary income).

Like an RRSP, a RRIF can hold a range of investments. You don’t need to sell your RRSP holdings when you convert—you just transfer them to your RRIF. Continue Reading…

Creating retirement income: a Fixed Payment Strategy

Once you stop working you may want to simplify your investment strategy. Your objective shifts from growing your investment portfolio to generating income. Flat and unpredictable markets, combined with historically low interest rates, can make this a challenging time in terms of creating retirement income.

One idea for creating a reasonably consistent level of monthly income is with a Monthly Income Fund. These funds have been around for quite some time. They hold a variety of government, municipal and corporate bonds, preferred shares and dividend stocks, and the payments come from a combination of interest and dividends, and sometimes, return of capital.

With these investments, cash flow is based on the number of units you own, not on the market value of the assets.

In non-registered accounts, the distributions can be more tax efficient than interest earned on GICs and bonds. However, keep in mind that there can also be taxable distributions in December (just as in other mutual funds) in addition to the monthly payout amounts.

Comparison of monthly income funds

Monthly income funds are sold by Canadian banks and mutual fund companies, and are also available in ETF versions.

The following chart is a comparison of some funds sold by Canadian banks as well as two popular ETFs. Continue Reading…

Retired Money: How to boost Retirement Income with Fred Vettese’s 5 enhancements

 Once they move from the wealth accumulation phase to “decumulation” retirees and near-retirees start to focus on how to boost Retirement Income.

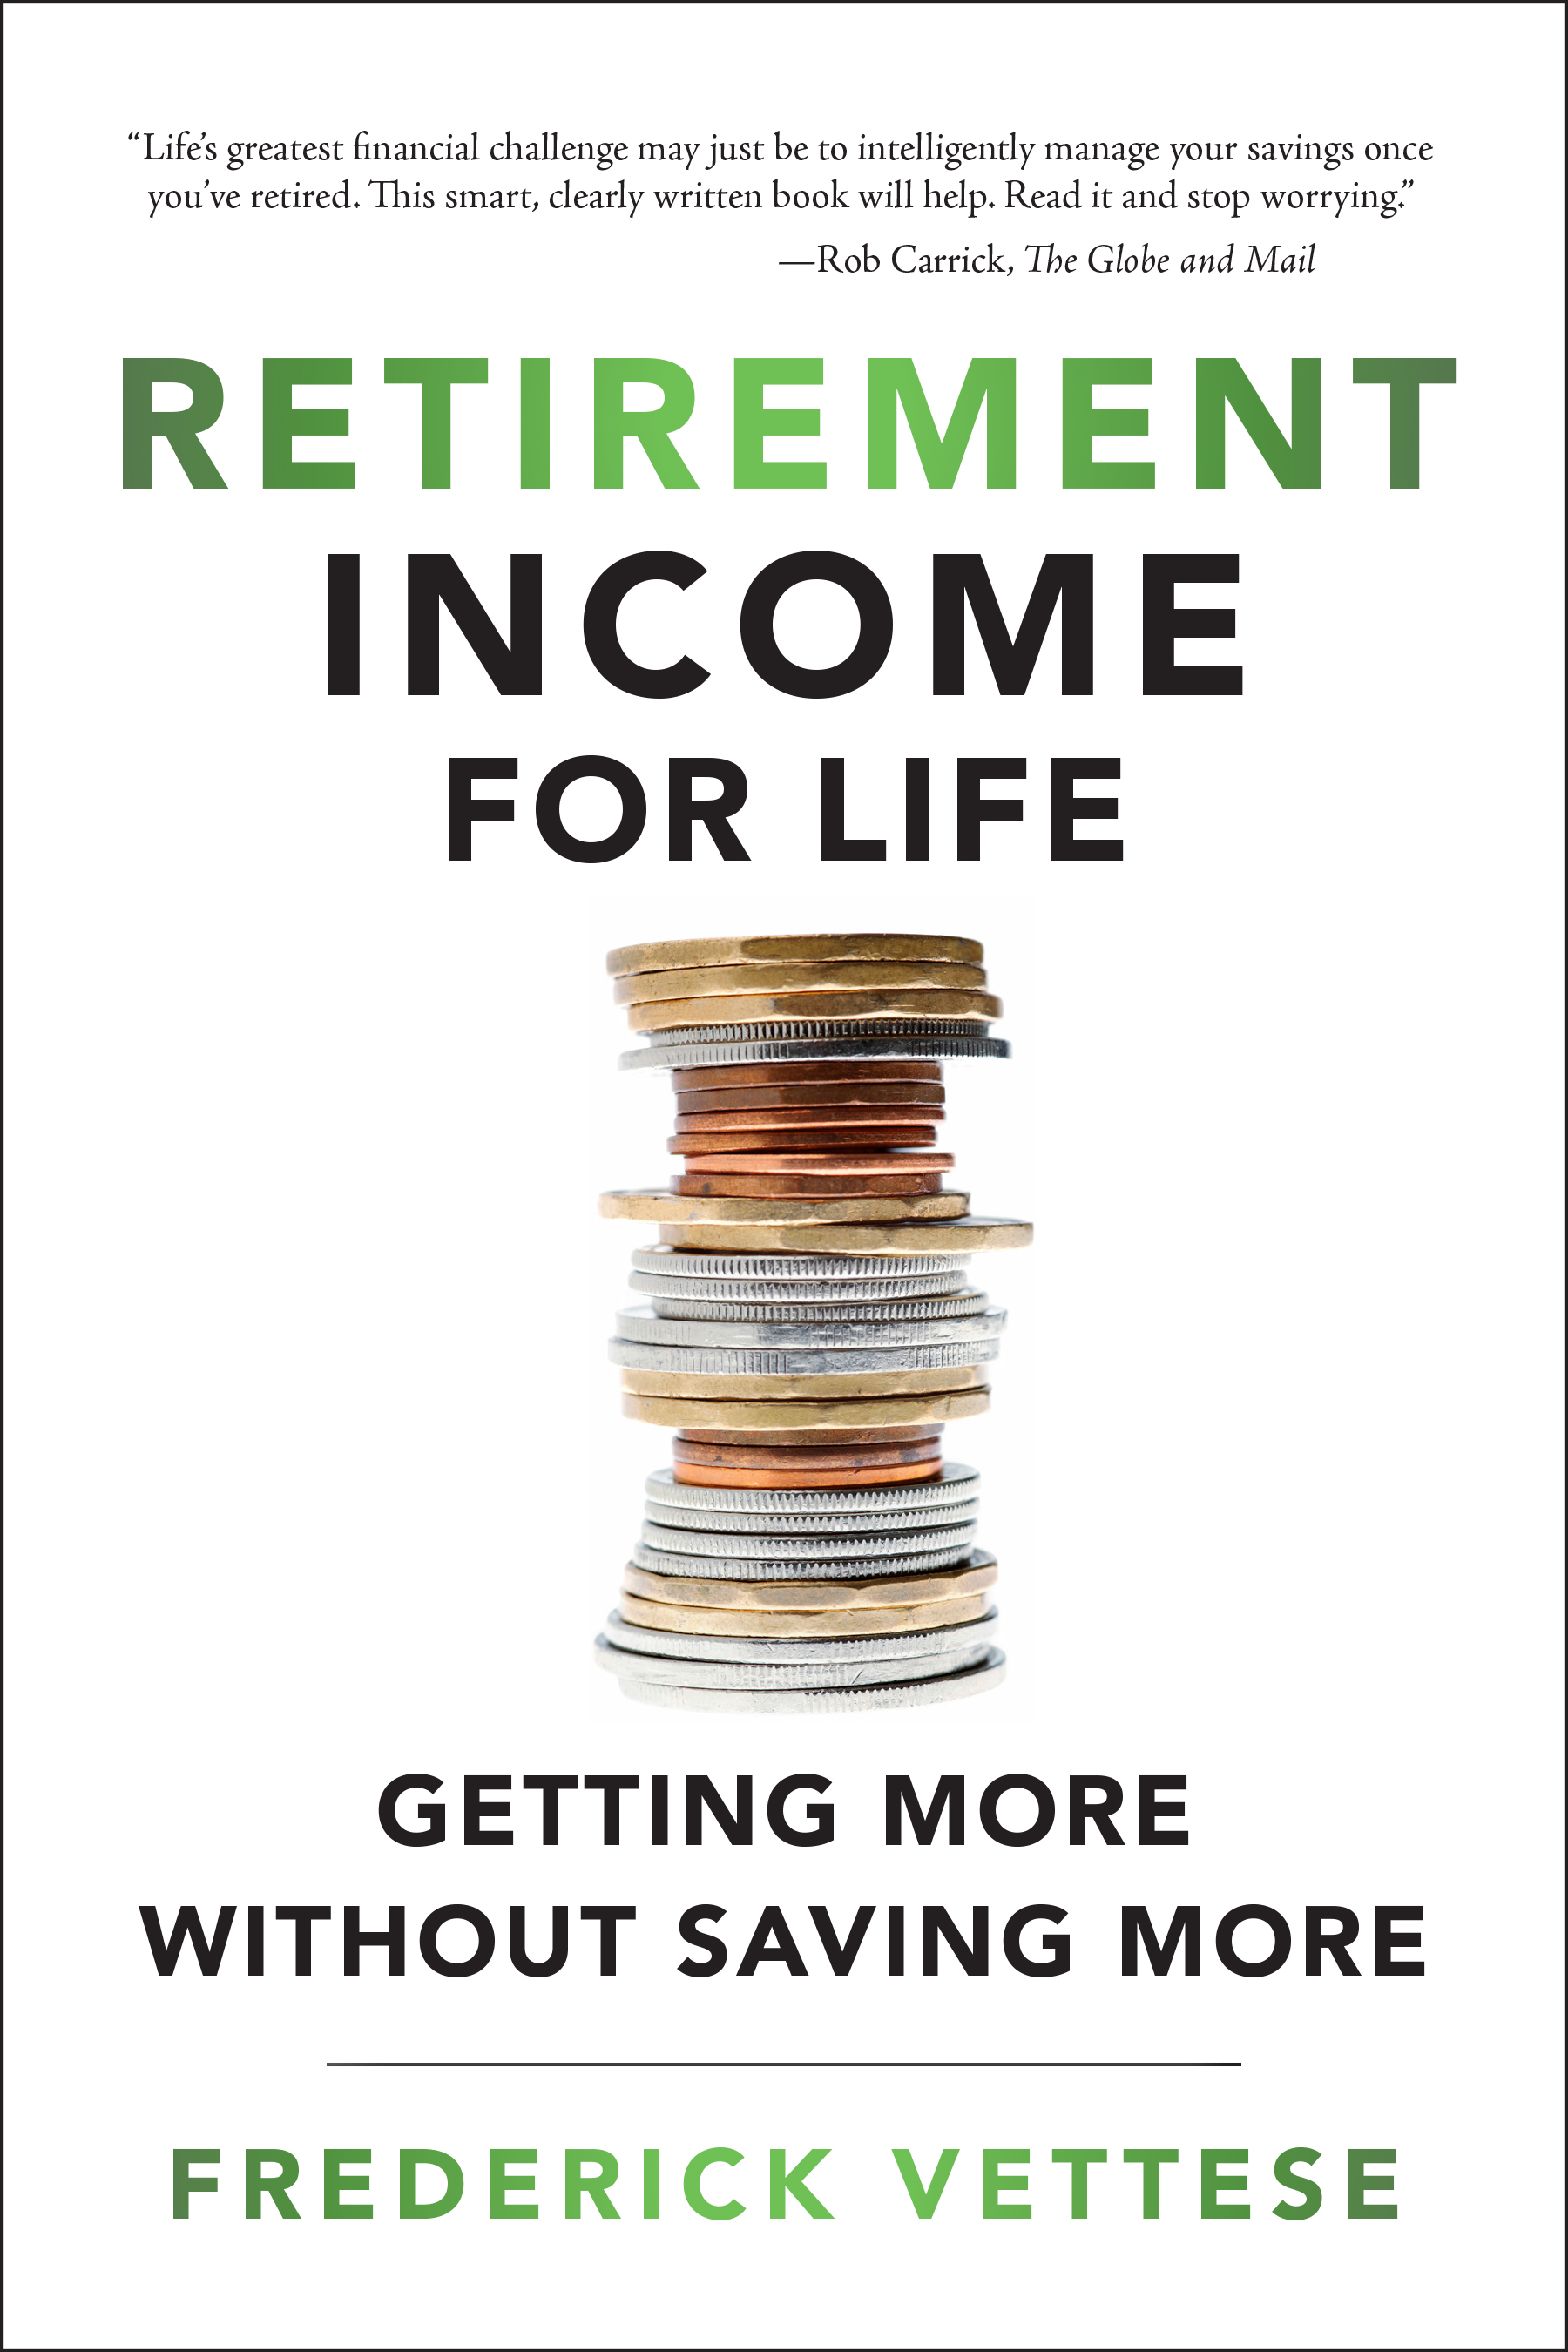
The latest instalment of my MoneySense Retired Money column looks at five “enhancements” to do this, all contained in Fred Vettese’s about-to-be-published book, Retirement Income for Life, subtitled Getting More Without Saving More. You can find the full column by clicking on this highlighted headline: A Guide to Having Retirement Income for Life.

You’ll be seeing various reviews of this book as it becomes available online late in February and likely in bookstores by early March. I predict it will be a bestseller since it taps the huge market of baby boomers turning 65 (1,100 every day!): including author Fred Vettese and even Yours Truly in a few months time.

That’s because a lot of people need help in generating a pension-like income from savings, typically RRSPs, group RRSPs and Defined Contribution plans, TFSAs, non-registered investments and the like. In other words, anybody who doesn’t enjoy a guaranteed-for-life Defined Benefit pension plan, of the type that are still common in the public sector but becoming rare in the private sector.

The core of the book are the five “enhancements” Vettese has identified that help to ensure that those seeking to pensionize their nest eggs (to paraphrase the title of Moshe Milevsky’s book that covers some of this ground) don’t outlive their money. Vettese says many of these concepts are current in the academic literature but have been slow to migrate to the mainstream, in part because few of these “enhancements” will be welcomed by the typical commission-compensated financial advisor. That in itself will make this book controversial.

Each of these “enhancements” get a whole chapter but in a nutshell they are:

1.) Enhancement 1: Reducing Fees

By moving from high-fee mutual funds or similar vehicles to low-cost ETFs (exchange-traded funds), Vettese explains how investment fees can be cut from 1.5 to 3% to as little as 0.5% a year, all of which goes directly to boosting retirement income flows. One of his takeaways is that “Tangible evidence of added value from active management is hard to find.”

2.)  Enhancement 2: Deferring CPP Pension

We’ve covered the topic of deferring CPP to age 70 frequently in various articles, some of which can be found here on the Hub’s search engine. Even so, very few Canadians opt to wait till age 70 to collect the Canada Pension Plan. Because CPP is a valuable inflation-indexed guaranteed for life instrument — in effect, an annuity that you can never outlive — Vettese argues for deferral, although he (like me) is fine with taking Old Age Security as soon as it’s available at age 65. He argues that for someone who contributed to CPP until age 65, they can boost their CPP income by almost 50% by waiting till 70 to collect.  “You are essentially transferring some of your investment risk and longevity risk back to the government, and you are doing so at zero cost.” Continue Reading…

How to enjoy a healthy retirement (literally!)

By Rachel Jackson

Special to the Financial Independence Hub

Whether it’s junk  food, drugs, alcohol, cigarettes or simply laziness there are many things that can lead to an unhealthy life. Not being health conscious can have dire consequences and you can easily walk yourself into an early grave if you don’t take care of your body. But it doesn’t have to be that way. With these tips to live by, you can stay healthy well into your retirement years.

1.) Keep fit

No matter what your age, you should be exercising regularly and doing your best to stay fit. While you don’t need to become a marathon runner or boxing expert, try to exercise for at least 30 minutes every day to maintain a healthy body and mind. Don’t believe that you have to tone it down when you reach a certain age either: your body will keep up with what you offer it. If you don’t start running until the age of 50 then you might have some problems but someone who regularly runs well into their fifties will be able to keep it up. Exercise helps to strengthen your heart, keep your body working and mobile and release endorphins to ease stress and improve mood.

2.) Eat healthily

There’s nothing wrong with a treat now and then but you need to stick to well-balanced meals and healthy snacks for the most part if you want to live for a long time. Eating the wrong diet, can result in  obesity, diabetes, digestive problems, heart problems and high cholesterol. And that’s only the start. Eat well: remember that when you put good stuff in, you will get bad stuff out.

3.) Laugh often

One of the best ways to extend your life is to enjoy it. Failing to spend time with friends and family, to entertain yourself, to have fun and laugh daily can be almost as harmful to your health as smoking or drinking. If you enjoy yourself, you exercise your heart muscles, ease stress and tension and keep a positive mind. If you don’t, you increase your risk of depression, illness, and complications associated with stress such as heart attacks.  Continue Reading…