Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Retired Money: the case for laddering Annuities

“The more bells and whistles, the lower the monthly income,” from annuities, says Caring for Clients’ Rona Birenbaum,

My latest MoneySense Retired Money column looks at the case for laddering annuities in order to avoid the problem of committing funds to annuities at interest rates that are only now coming off their historic lows. You can retrieve the whole article by clicking on the highlighted text: A low-risky annuity strategy to beef up your retirement cash flow.

Many investors are already acquainted with the concept of “laddering” guaranteed investment certificates (GICs), or bonds with different maturities. Maturity dates are staggered over (typically) one to five years, so each year some money comes due and can be reinvested at prevailing interest rates. This minimizes the likelihood of investing the whole amount at what may turn out to be rock-bottom interest rates, only to watch helplessly as rates steadily rise over time.

The same applies when it comes time for retirees or near-retirees to annuitize. At the end
of the year you turn 71 you must decide whether to convert your RRSP into a RRIF,
cash out and pay tax (few do this), or thirdly to annuitize.

Fortunately, annuitization isn’t an all-or-nothing decision. You can convert some of your RRSP to a RRIF and some to a registered annuity. You can take a leaf from the GIC laddering
concept and buy annuities gradually over five, ten or even more years. As regular Hub contributor Patrick McKeough observes in the piece, laddering annuities can reduce the potential downside: “You could buy one annuity a year for the next five years. That way, your returns will increase if interest rates rise, as is likely.”

Tally up how many annuities you may already have

Mind you, few observers believe in converting ALL your disposable funds into annuities. After all, as another Hub contributor — Adrian Mastracci — notes, you need to take inventory of the annuity-like vehicles you already may have, or expect to have: such as  employer-sponsored Defined Benefits, CPP or OAS. Some investors may have a high component of annuity-like income without realizing it, and many families may already have five or six such sources of annuity-like income.
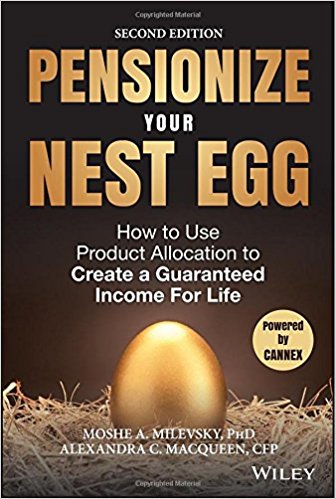
Certainly you need to consider both the benefits and drawbacks of annuities. The main benefit is they are a form of longevity insurance: making sure you never outlive your money no matter how long you live. There’s a case for having enough annuities that your basic “survival expenses” (shelter, food, heat, transport etc.) are taken care of no matter what. Finance professor Moshe Milevsky is also quoted in the article to the effect there are compelling financial and psychological reason to at least partly convert to annuities. And Milevsky is famous for making a distinction between “REAL” pensions (like DB pensions) that behave like annuities, as opposed to vehicles like RRSPs and TFSAs, which provide capital that only have the potential to be annuitized. Hence the title of Milevksy’s excellent book, Pensionize Your Nest Egg.

But annuities are not perfect. Apart from the common reluctance to commit to buying annuities at today’s still-low interest rates, there’s also the matter of the irreversible nature of the decision to convert some capital to an annuity. You’re handing over a large chunk of change to an insurance company and should you die earlier than expected, they in effect “win,” to the partial detriment of your estate. If on the other hand you live to 120, then YOU “win.”

Continue Reading…

Forced Early Retirement? 7 things you should do right now

By Michelle Arios

Special to the Financial Independence Hub

There are a lot of life situations that can lead someone to retire much earlier than they had initially anticipated. It could be illness, injury, the need to move quickly, an emergency family circumstance, or even a company closing its doors. Why you’re being forced to retire isn’t nearly as important as the silver lining you need to find in your situation, and what steps you’ll take to get there.

1.) Get a great Savings plan

Your normal savings account may not be enough to carry you through. It might help to change your current savings account to one that gives you a better interest rate, particularly if you’re going to consolidate your retirement accounts. It might also help to supplement your savings with some investments that will grow with time.

2.) Work out your new Budget

People in retirement often live on fixed incomes, especially if their spouse is also retired. You need to be sure your money can go as far as you need it to, and that might mean breaking apart your old budget and determining where and how you can best reduce costs while maintaining your quality of life. There are some easy-to-use smartphone apps that might help you do that.

3.) Downsize your Home

The expenses of maintaining a household are high. If you’re retired, you probably don’t need all the extra space anyway. Finding a roommate can help, and so can selling your previous home to purchase a smaller home that’s easier to maintain. Often times, utility bills will significantly go down on a smaller property. You’re also gaining some extra cash and a little more financial longevity.

4.) Find affordable alternatives

Monthly costs, like health insurance and cellular phone bills, can often add up to a lot of money. You might want to consider shopping around for a better deal. Continue Reading…

Retired Money: Early or Delayed CPP? Age 65 may be best compromise

My latest MoneySense Retired Money column has just been published, which tackles that perennial personal finance chestnut of whether to take early or delayed CPP benefits. You can find it by clicking on the highlighted headline here: The Best Time to Take CPP: if you don’t know when you’ll die.

That’s a pretty big “if,” of course since with rare exceptions, our futures are unknowable. As readers of the piece will discover, there is a fair bit of personal anecdotes there, which is hard to avoid in a beat known as “Personal Finance.” As the column notes, we’ve written before that in theory it makes sense to delay CPP as long as possible, since monthly benefits are 42% higher than if you took them at 65. And while you can take CPP as early as age 60, you’d pay a 36% penalty to do so compared to taking it at the traditional age 65.

Since experts are all over the place on this one and have valid arguments for either side, it’s interesting that in practice very few Canadians actually wait till age 70 to start their CPP, even if it is an inflation-indexed guaranteed-for-life annuity. Government stats show age 60 is the single most popular option: according to the federal government’s 2016 data, of the 312,251 who began collecting CPP that year, 126,954 did so right at age 60, with the second most popular start date being age 65, when 93,460 started to collect. Only 4,844 waited until 70.

The balanced case for the traditional age 65

As I relate in the MoneySense piece, I still haven’t started to collect CPP myself, even as my 65th birthday looms this coming April. Continue Reading…

Doing it: 50% more income in Retirement

By Mark Yamada and Ioulia Tretiakova

Special to the Financial Independence Hub

Nobel laureate William Sharpe described managing retirement assets as the “nastiest hardest problem in finance.” Living longer on a fixed pool of capital is only the start of a problem complicated by the myriad of possible personal and family needs and obligations that develop over a lifetime.

The need

Demographics are driving big change in the retirement market. Not only will Gen Y workers have fewer opportunities to save for retirement because of high predicted job turnover and reduced access to workplace pensions, but retiring baby boomers are being abandoned by the very industries created to serve them.

The pension, mutual fund and wealth management industries are direct responses to boomers joining the work force, but fewer retiring boomers meet the criteria for investment advisors who are compensated for growing assets. Retiree portfolios don’t get contributions and many are too small to qualify as brokerage minimums rise. Most mutual fund fees are too high for this cohort for whom costs are more important than ever before. The number of advisors is also shrinking, not only because of compensation and compliance pressures but also because advisors too are retiring.

Saving more, starting earlier and taking more risk are the accepted ways to improve retirement outcomes. Two or more of these options may no longer be available for retirees. A growing crisis in retirement savings is stretching an already extended social welfare system and new thinking is needed if disaster is to be averted.

Solutions not products

Our research motivation (Journal of Retirement and two Rotman International Journal of Pension Management papers) is a belief that investing can be improved to solve problems. The pension problem, for example, is best resolved by focusing on what workers really want, reliable replacement income in retirement rather than trying to pick the best performer every period. Consumers today want solutions. The investment industry is still about products.

Just as someone who only owns a hammer sees every problem as a nail, the industry has a singular focus on “maximizing returns.” This sounds good, but anyone using Google maps knows the fastest route to a destination is not necessarily the shortest. UPS routes deliveries to avoid turns against oncoming traffic to reduce accidents and delays waiting for gaps. Their drivers make 90% right hand turns and experience shorter delivery times, lower fuel consumption and operate smaller fleets. What if investment portfolios could similarly be routed more efficiently to correct destinations?

Autonomous portfolios

The self-driving automobile that protects passengers from immediate risks and routes itself to a predetermined destination provides a template for an autonomous portfolio.

Getting to a destination is a different strategy than going as fast as possible all the time. For starters, brakes and steering are needed not just an accelerator pedal. Maximizing returns, the investment industry’s primary approach, is about going fast. If your strategic asset mix is 65% stocks and 35% bonds, your advisor will periodically rebalance to this mix. If stocks go down, she will buy more stocks. This sounds like the right thing to do, and it is, if your investing time horizon is long enough to make back accelerating loses over the next market cycle; your portfolio is throwing money at a falling market after all. For an aging population in general and retiring baby boomers in particular, this is an increasingly risky and unpalatable proposition.

How we can do it

To protect portfolios we keep risks as constant as possible. When volatility rises, some risky assets, like stocks, are sold and less risky ones, like bonds, are added. When volatility falls, we add riskier assets. The critical effect is avoiding big losses. Statistically this is like card counting in the casino game of blackjack. When volatility is higher than average, the deck is stacked against the player. This means we expose portfolios primarily to markets that are favorable. It’s an unfair advantage but it’s legal! Continue Reading…

CPP Reality Check

Repeat after me: The Canada Pension Plan will be there for me when I retire.

In fact, CPP is sustainable over the next 75 years according to the most recent report issued by Canada’s Chief Actuary. This projection assumes a modest 3.9 per cent annual real rate of return over that time.

The plan is operated at arms length from governments by the CPP Investment Board (CPPIB), whose sole mandate is to maximize long-term investment returns in the best interests of CPP contributors and beneficiaries.

Despite this assurance, I still see numerous comments on blogs and social media dismissing CPP as something doomed to fail.

“The feds are robbing the CPP fund to pay for infrastructure and massive debt loads.”

“I’m fairly certain there won’t be a CPP fund in 25 years when I’m ready to retire.”

“My retirement projections don’t include CPP, just in case . . . “

The media exacerbates the problem by reporting on the CPPIB’s quarterly earnings, which, most recently, slumped to 0.7 per cent thanks to a strong loonie dragging down its foreign investments. But to the CPPIB and its long-term investing mandate, a quarter isn’t measured in three months: it’s more like 25 years.

Don’t ignore CPP in your retirement projections

It’s a mistake to ignore CPP benefits in your retirement planning projections. While it won’t save your retirement, CPP is paying out on average $653 per month for new beneficiaries as of July, 2017. The maximum monthly payment amount [if taken at age 65] is $1,114.17.

Continue Reading…