You see lots of people on business channels and investing blogs talking about the types of things to invest in when inflation is high – energy stocks, material stocks, value stocks, dividend growth stocks, floating rate bonds, inflation bonds, oil, copper, gold, silver, crypto, etc. OH MY! – and what types of investments you should avoid. On the surface, it’s pretty reasonable advice.
“Of course!! I should be invested in something that does well when inflation is high! Inflation is high now! And everyone says it’s going to continue like this for a long time! And I want my investments to grow!” But before we go leaping and investing in whatever it is that’s great during inflationary times, let’s explore the soundness of the argument itself.
The Tautology of it all
I’m always a little amused when people say things like:
“When market variable X is high (or low), that will cause thing Y to happen, which will cause thing Z to occur, which will cause some asset A to go up (or down). And so when market variable X is high/low/whatever, then buy (or sell) asset A. Easy peasy!”
There’s a lot happening there, but at its core, it’s just a chain of events: X leads to Y leads to Z leads to A going up (or down). At each step, there are assumptions baked in, assumptions that aren’t exactly baked into the fabric of the universe, but let’s leave that for now. Because what is more interesting here is that the expression above can be simplified as follows:
“When asset A is going to go up, you should buy asset A.”
This is much cleaner. It removes all the unnecessary hand-waving (but, perhaps the hand-waving IS necessary … but by whom? And for what purpose?) and lays bare what is actually being said:
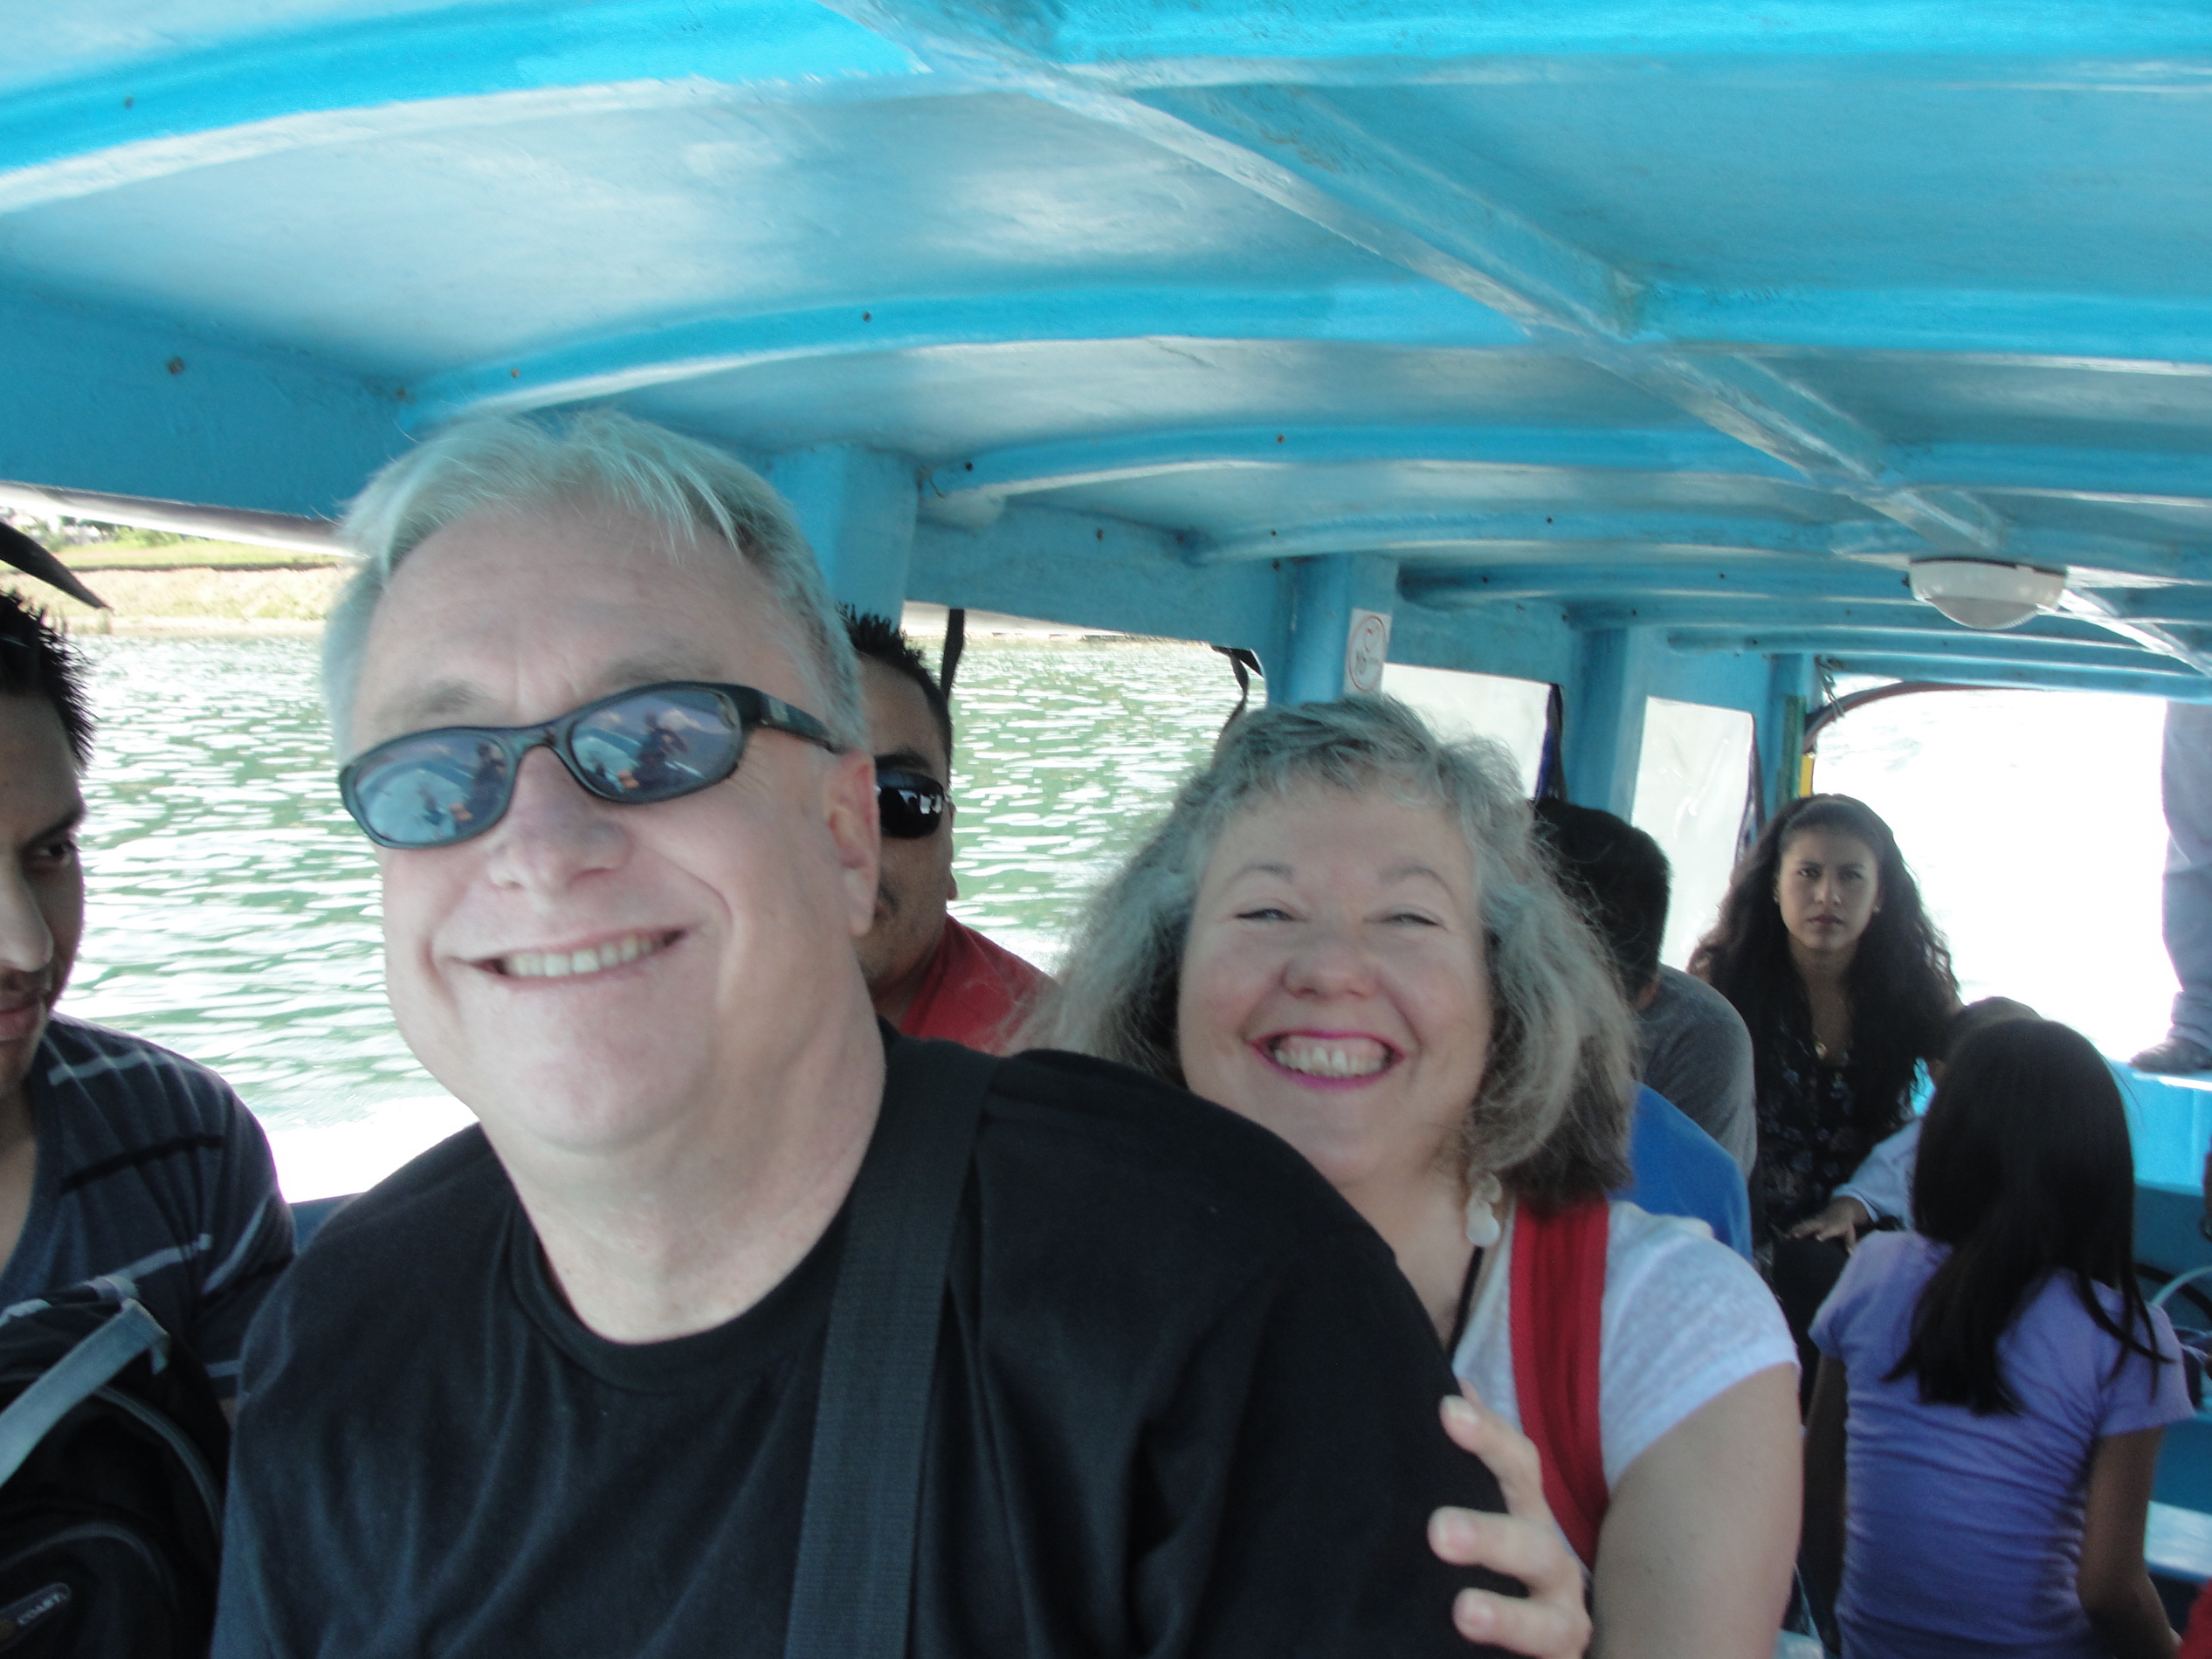
Billy and Akaisha Kaderli on Lake Atitlan, Guatemala
By Billy and Akaisha Kaderli, Retireearlylifestyle.com
Special to the Financial Independence Hub
In January, 2022 we began our 32nd year of Financial Independence. Few people can say they have 30 years of self-funded retirement by the age of 68 and have a higher net worth after spending and inflation than when they started. This is something of which we are quite proud.
As we have aged, one thing we have learned is that long term is getting shorter every day. Life is to be enjoyed now, not someday: the older we get the more we appreciate that view. Life is continuously full of opportunities and we want to take them.
Opportunities abound
For example, a couple of years ago we were approached by a startup company which sponsored us for several months in Saigon, Vietnam in exchange for sharing our past experience in the restaurant and service industry and for exposure to our readers through our popular website and blog. That was a fabulous trip, and it got us back over to Asia again.
Then we were approached for a partnership, offering tours to Europe and South America. Can you imagine? There are always opportunities!
These are just two examples of why we say that life is full of chances to grow and learn something new if you want to take them. And neither of these recent options could have been presented to us if we were still working.
Portfolio getting stronger
Since the 2008 financial meltdown the markets certainly have performed well, thereby increasing our portfolio. And for a longer term view the S&P 500 closed at 312.49 when we retired in 1991, producing a better than 8% annual ride plus dividends. So, our advice is to get invested now and in a couple of decades looking back you will have wished you had invested more. Probably a lot more.
We suggest people track their spending now, then multiply that number by 25 to get a rough estimate of the portfolio amount they need to retire. Once you know that amount, in simple terms, assuming the same 8% growth in the future and you withdraw 4% for living expenses, this leaves you 4% to cover inflation and growth so you are all set.
The 4% rule is a guide not set in stone and oursbounces around depending on the markets and our expenses, but on average we have been able to maintain it easily below 4%. Our data over 30 years gives us security knowing that if one year it is higher we can make adjustments the following year to correct it. Then again, the markets could move higher helping us out as well, which is usually the case. Plus, we now are receiving Social Security, so payments and dividends cover our expenses. You can read our reasoning behind this decision here.
Practical considerations
Another note is that because we have a good percentage of assets in retirement accounts, when we turned 56 years old we used IRS rule 72T to withdrawal an annual amount close to our estimated Social Security payments, thus creating a bridge until we actually qualified. Now that we are receiving benefits we have turned off that spigot and are letting the IRAs grow once again.
The age of 72 is now coming into our sight and RMD, required minimum distributions, are the next issue to deal with, but we still have time and no one knows what the tax laws will be then.
With that stated, we still maintain a core holding of buy and hold (DVY, SPY, VTI) which sends us a steady stream of dividends in our taxable accounts as well as tracking the market. But in our IRAs, where we have no tax issues regarding trading, we have been more active using market seasonality with the idea of side-stepping larger declines. Some years have been better than others but we have been taking about half of the market risk than being all in all the time and that is comforting.
Where to retire, cost of living and healthcare
We are not alone anymore, with Boomers retiring at 10,000 a day, we see more retirees everywhere! But in terms of the foreign locations that we visit, the retirement community of Chapala, Mexico is growing at a fast pace. The Colonial town of Antigua, Guatemala has also attracted its share of Expats, and there is a solid and active retirement community in Chiang Mai, Thailand and Panama.
We would recommend Mexico, Panama and Guatemala for their proximity to the US and Canada as well as being on similar time zones as family and financial markets in the States. We would say that Thailand is attractive for its excellent medical care, warmer weather and uniqueness. All of these locations offer excellent lifestyle for cost of living. Continue Reading…
As a small business owner who is emotionally, physically, mentally, and financially engaged in a growing startup, you may feel consumed in the now. So many small business owners put everything back into their company without setting aside their profits in a tax-efficient way. If you run your business without an eye to the future, you will never reach the point where work becomes optional. Your business is your vehicle to financial independence, but it won’t happen without years of careful preparation.
The independence and freedom of your entrepreneurial path comes with an array of responsibilities. As the business owner, the weight of preparing for your retirement and the retirement of your employees falls entirely on your shoulders. After all, if you don’t plan for your retirement, who will? Start building retirement savings into your company budget and making it a part of your compensation for running the company.
Business owners in the U.S. have retirement options for many situations
As a small business owner, you have a retirement option for almost every situation. When choosing a plan, your most significant consideration is the cost of contributing. If you can only afford to set aside a small amount of money each year, anindividual retirement account (IRA) will serve you well.
ASimplified Employee Pension plan (SEP) is the equivalent of a jumbo IRA. This plan works best for self-employed entrepreneurs with few or no employees. You can contribute up to 25% of your compensation to a SEP, with a maximum of $61,000 per year allowable in 2022. Keep in mind that if you have eligible employees, an SEP requires you to contribute an equal percentage of their salaries to the percentage you contribute from your own revenue. For example, a business owner with an employee making $100,000 per year would have to contribute 25% of the employee’s salary if they want to maximize their own contribution at 25%. If you have a number of employees, a SEP will most likely be your most expensive option. Continue Reading…
In this post I’ll offer up charts on our U.S. stock portfolio and the Canadian stock portfolio. And I’ll put them together so that we can see how they work together. The total portfolio was designed to be retirement-ready. The fact that it beats the market benchmarks is a welcome surprise. At the core of the portfolio is wonderful Canadian dividend payers – the U.S. stocks fill in some portfolio holes. Let’s have a look at our U.S. and Canadian stock portfolio.
I recently received requests to share our U.S. stock portfolio holdings. While I often track that portfolio on Seeking Alpha (the land of stock pickers) that’s not a regular event on this blog. I have certainly shared the Canadian Wide Moat Portfolio on Cut The Crap Investing.
On Seeking Alpha, here is our U.S. stock portfolio. The post may be paywalled for those who have exceeded the 3 free reads on Seeking Alpha. Again, that’s why I will share some details here. But keep in mind, this is not advice. But you may be on the receiving end of some ‘good’ lessons on building the simple stock portfolio.
Skimming the dividend achievers index
In early 2015 I skimmed 15 of the largest-cap dividend achievers. What does skim mean? After extensive research into the portfolio “idea” I simply bought 15 of the largest cap dividend achievers. For more info on the index, have a look at the U.S. Dividend Apprecation Index ETF (VGG.TO) from Vanguard Canada. At the core is a meaningful dividend growth history working in concert with financial health screens. It leads to a high quality skew.
I won’t get too deep into the methodology and how and why I constructed our portfolio in this post. I will offer more details in a post next week. Today, I will just get to the fun stuff – the holdings and the return charts and tables.
The U.S. Dividend Achievers
The 15 companies that I purchased in early 2015 are 3M (MMM), PepsiCo (PEP), CVS Health Corporation (CVS), Walmart (WMT), Johnson & Johnson (JNJ), Qualcomm (QCOM), United Technologies, Lowe’s (LOW), Walgreens Boots Alliance (WBA), Medtronic (MDT), Nike (NKE), Abbott Labs (ABT), Colgate-Palmolive (CL), Texas Instruments (TXN) and Microsoft (MSFT). Continue Reading…
I never thought that I would fail at retirement and end up in Retirement Hell. But I did.
You see, I spent my entire career – almost forty years- in the banking industry. While there, I learned a lot about money and investing and, over the years, I helped thousands of clients save for their own retirement. Furthermore, my wife is a financial advisor. And yet despite all that knowledge and expertise, I still managed to fail miserably at retirement.
Looking back, I now realize that many of my beliefs about retirement were wrong because they were all linked to the financial aspects of retirement. What I know for sure now is you just don’t fall into a happy retirement because you have a lot of money. You need financial security, of course. But designing a satisfying life takes thought, time and planning on many more levels. You need to know your needs and values, and what makes you happy, and then you have to find ways to satisfy these aspirations on a regular basis. Thinking that you will figure things out when you get there doesn’t work.
Traditional retirement planning has programmed us to think it’s all about the money, but it’s not. In conventional planning, the focus is always on the number: how much money you are going to need to retire. Few financial advisors/planners talk about the other important stuff: how you are going to replace your work identity, how you are going to stay relevant and connected, and how you are going to keep mentally sharp and physically fit, among other things.
Believe it or not most retirements fail for non-financial reasons rather than financial ones. I don’t want that to happen to you so for the past year and a half I along with five of my friends have been working on a new book — Longevity Lifestyle By Design — to help people design a life they would be happy to wake up too.
Retiring from work is simple. Figuring out what you are going to do with the rest of your life is the hard part.
Our mission is to help improve the transition to retirement and help retirees to design a life that they look forward to living everyday.
We know that many people are going to struggle with the non financial challenges that can often accompany retirement. It happened to me, my colleagues and through my discussions with other retirees discovered that it also happened to many of them as well. Continue Reading…


 Posted By
 By Myron Genyk, Evermore Capital
 Posted By