General

Flying the Findependence Flag: My appearance on Patrick Francey’s The Everyday Millionaire podcast

The Everyday Millionaire podcast starring REIN’s Patrick Francey has just released its one-hour-plus interview with me. You can find it (audio) on the regular podcast channels by clicking this title: Flying the Findependence Flag.

The podcast has been going since 2017, and sports the slogan “Ordinary people doing extraordinary things.”

It was a wide-ranging and surprisingly personal interview. Most of Francey’s guests are real estate millionaires: given the bull market in Canadian residential real estate it’s not surprising that most of Francey’s guests are technically millionaires: even starter homes in Toronto are going for a million dollars.

REIN’s Patrick Francey

Patrick Francey is the CEO of REIN, the Real Estate Investment Network, with which I have long been familiar: my daughter Helen once worked there. Sadly, as you will discover on the podcast, I confess that our family never made the plunge into investment real estate beyond owning a principal residence in Toronto. We discuss the fact that while real estate is an excellent way to achieve Financial Independence, some of us are more comfortable with investing in financial assets like stocks and bonds: in so-called “clicks” rather than “bricks.”

The foundation of Financial Independence

As I say in the interview as well as the recently updated US edition of my financial novel, Findependence Day, job one is to purchase a principal residence and pay down the mortgage as soon as possible; hence the saying “The Foundation of Financial Independence is a paid-for home.” Continue Reading…

Tax Strategies to Boost your Financial Savings

Lowrie Financial/Unsplash

By Steve Lowrie, CFA

Special to the Financial Independence Hub

Today’s Simple Investing Take-Away: Your tax planning strategy should take a holistic, tax-efficient investing stance in both tax-sheltered and taxable investment vehicles to optimize saving for the future.

Does it bug you to pay more taxes than you need to? I don’t think I’ve ever met anyone eager to shell out extra money, just in case the government could use more. But practically speaking, that’s exactly what you end up doing if you don’t build tax-efficient investing and other tailored tax strategies into your ongoing financial planning.

Are you:

  • A young professional, aggressively saving for a distant future?
  • A seasoned business owner, managing substantial financial savings
  • Starting to spend down your assets in retirement?
  • Planning for how to pass your wealth on to your heirs?

Regardless, there are many best practices for maximizing your after-tax returns—i.e., the ones you get to keep. Today, let’s cover what some of those sensible tax strategies look like.

Fill up your Tax-Sheltered Accounts

The government offers a number of “registered” investment accounts to provide various types of tax-efficient investing incentives. They want you to save for retirement and other life goals, so why not take them up on the offer? Two of the big ones are the Registered Retirement Savings Plan (RRSP) and Tax-Free Savings Account (TFSA).

Saving for Retirement with Your RRSP

As the name suggests, your RRSP is meant to provide tax-efficient investing for retirement. In the years you contribute to your RRSP, you receive a deduction on your tax return in equal measure. Then the proceeds grow tax-free. Once you withdraw RRSP assets in retirement, you pay income tax on them.

In theory, your tax rate is often lower once you retire, so you should ultimately pay fewer taxes on taxable income. Even if there are some retirement years when your tax rates are higher, you’ve still benefited from years of tax-free capital growth in an RRSP. And you still have more flexibility to plan your RRSP withdrawals to synchronize with the rest of your tax planning.

Bonus tips: If you’re a couple, you may also consider using a spousal RRSP to minimize your household’s overall tax burden. This works especially well if one of you generates a lot more income than the other. There also are specialized guidelines to be aware of if you’re a business owner considering how to most tax-efficiently draw a salary and participate in the Canada Pension Plan (CPP).

Saving for the Future with Your TFSA

TFSAs are meant to be used for tax-efficient investing toward any mid- to long-term financial goals. So, at any age, most taxpayers are well-advised to fill up their TFSA space to the extent permitted. You fund your TFSA with after-tax dollars, which means there’s no immediate “reward” or deduction on your tax return in the year you make a contribution. But after that, the assets grow tax-free while they’re in your TFSA, and you pay no additional taxes when you withdraw them, which you can do at any time.

Bonus tip: Too often, people leave their TFSA accounts sitting in cash, using it like an ATM machine. Unfortunately, this defeats the purpose, since you lose out on the tax-free gains you could expect to earn by investing that cash in the market. How much is tax-efficient investing worth? In “Cash is not king: A better investment strategy for your TFSA,” I offer some specific illustrations.

Manage your personal Tax Planning like a Boss

Once you’ve filled your tax-sheltered accounts, you can invest any additional assets in your taxable accounts.

Like hard-working “employees,” these assets can thrive or dive depending on their management. Think of it this way: As a business owner, you wouldn’t hire a promising team of talented individuals, only to assign them random roles and responsibilities. Likewise, your various investments and investment accounts have unique qualities worth tending to within your overall tax-efficient investing. Let’s cover a few of them here.

Capital Gains Reign

In your taxable accounts, your best source of tax-efficient investing income comes in the form of capital gains or even better, deferred/unrealized capital gains. This is super important, but often forgotten in the pursuit of sexier trading tactics, like chasing hot stocks or big dividends. (It’s popular to think of dividends as a great source of dependable income in retirement, but in “Building your financial stop list: Stop chasing dividends,” I explained why that’s mostly a myth.)

Don’t believe me? Consider these 2021 combined tax rates for Ontario on various sources of investment income:


Taxable Income Source

2021 Combined Tax Rate

Interest and other income

53.53%

Eligible dividends (mostly Cdn. companies)

39.34%

Capital gains

26.76%

This illustration assumes a top marginal tax rate in Ontario, or taxable income greater than $220,000. But the point remains the same at other rates: You can usually lower your taxes by favouring capital gains over other sources of taxable income.

Also remember, you don’t pay taxes on a capital gain until you actually “realize” it, by selling an investment for more than you paid for it. Combine this point with the rates just presented, and your ideal investment strategy seems obvious: Tax-efficient investing translates to a low-cost, low turn-over, buy-and-hold approach.

Since minimizing the impact of taxes is a huge way to improve on your overall rate of returns, this happens to be exactly what I advise for any of your investments, whether you’re holding them in a taxable or tax-sheltered account.

Bonus tip: Once you’ve embraced low-cost, low-trade investing, be sure to also use funds from fund managers who are doing the same. It defeats the purpose if you are being disciplined about your tax-efficient investing, but the underlying funds in which you’re invested are not.

Asset Location Is where it’s at

As your wealth accumulates, you’re likely to end up with a mixture of registered and taxable accounts. You can reduce your overall tax burden by managing these accounts as a single, tax-efficient portfolio, instead of treating each as an investment “island.” Asset location means locating each kind of investment, or asset, in the right type of account, given its tax efficiency:

  1. Hold your relatively tax-inefficient assets in tax-favoured accounts, where the inefficiencies don’t matter as much. Examples include bonds, which generate interest and other non-capital-gain income; and investments that have higher than average yields such as REITs.
  2. Hold your relatively tax-efficient assets in taxable accounts; examples include broad domestic or global stock funds that generate most of their returns as capital gains.

An Easy Rebalancing Strategy

As I covered in “Rebalancing in Down Markets, Scary But Important,” it’s essential to periodically rebalance your investment portfolio. It’s like tending to your garden by thinning out (selling) some of the overgrowth, and planting (buying) where you need more. This keeps your productive portfolio growing as hoped for, with a buy low, sell high strategy.

But as usual, there’s a catch: When you “sell high” in a taxable account, you’ll realize taxable gains. So, whenever possible, try using cash you’d be investing anyway to do your rebalancing for you. Instead of just plopping any new investable cash into haphazard holdings, invest it wherever your portfolio is underweight relative to your goals. In so doing, you can improve on your tax-efficient investing. (PS: Here’s another post I’ve published, with additional ideas on “What to Do with Excess Cash.”)

Tax-Loss Harvesting

Again, one of the best ways for your assets to grow tax-efficiently is within your registered, tax-sheltered accounts. That said, tax-loss harvesting is one tax-efficient investing strategy you can only do in a taxable account. Without diving too deep, when one or more of your holdings is worth less than you paid for it — but over the long run you expect the position to grow — you can use tax-loss harvesting to:

  1. Sell the depreciated position to generate a capital loss, which you can then use to offset current or future taxable gains.
  2. Promptly buy a similar (but not identical!) position so you remain invested in the market as planned.
  3. Eventually (optionally), reinvest in the original position to restore your portfolio to its original mix.

Again, all this only works within a taxable account. Also, the CRA has strict rules on what qualifies as a true capital loss, and may disallow it if you violate those rules. This makes it one smart strategy best completed in alliance with your personal financial advisor.

Advanced Tax Strategies for Families and Business Owners

We’ve barely scratched the surface on the myriad tax-planning strategies you can deploy in your quest to pay no more than their fair share of income taxes. Depending on your particular circumstances, you can take advantage of some of these tax strategies: Continue Reading…

Two types of overconfident investors

I started investing in individual stocks shortly after the Great Financial Crisis ended in 2009. I picked an investing strategy that closely resembled the Dogs of the TSX, buying the 10 highest yielding Canadian dividend stocks. As you can imagine, the share prices of these companies got hammered during the stock market crash so I was able to scoop up shares in banks, telecos, pipelines, and REITs on the cheap.

Stocks came roaring back right away and my portfolio gained 35% by the end of 2009. Investing is easy, right?

It took me a while to figure out that my portfolio returns had less to do with my stock picking prowess and more to do with market conditions, luck, and the timing of new contributions. The rising tide lifted all ships, including my handful of Canadian dividend stocks.

I started comparing my returns to an appropriate benchmark to see if my judgement was adding any value over simply buying a broad market index fund. My portfolio outperformed for a few years until it didn’t. In 2015, I had enough and switched to an index investing strategy. Now I invest in Vanguard’s All Equity ETF (VEQT) across all of my accounts.

Related: Exactly How I Invest My Money

New investors who started trading stocks in the past 18 months have likely had a similar experience. Stocks crashed hard in March 2020, falling 30%+ from the previous month’s all-time highs. Since then markets have been on an absolute tear. The S&P 500 is up 91% from the March 2020 lows. The S&P/TSX 60 is up 70%.

That’s just country specific market indexes, mind you. Since March 2020 individual stocks like Facebook and Apple are up 137% and 155% respectively. Tesla is up 700%. Meme stock darlings AMC and GameStop are up 1,045% and 3,621% respectively.

No doubt, unless they’ve done something disastrous, new investors participating in this market have seen incredible returns so far.

This can lead to overconfidence – when people’s subjective confidence in their own ability is greater than their objective (actual) performance.

Overconfident Investors

Larry Swedroe says the biggest risk confronting most investors is staring at them in the mirror. This is the first type of overconfident investor.

Overconfidence causes investors to trade more. It helps reinforce a belief that any investment wins are due to skill while any failures are simply bad luck. According to Swedroe, individual investors tend to trade more after they experience high stock returns.

Overconfident investors also take on more uncompensated risk by holding fewer stock positions.

Furthermore, overconfident investors tend to rely on past performance to justify their holdings and expectations for future returns. But just because stocks have soared over the past 18 months doesn’t mean that performance will continue over the next 18 months.

In fact, you should adjust your expectations for future returns – especially for individual stocks that have increased by 100% or more. No stock, sector, region, or investing style stays in favour forever. If you tilt your portfolio to yesterday’s winners (US large cap growth stocks) there’s a good chance your portfolio will underperform over the next decade.

The second type of overconfident investor is one who makes active investing decisions based on a strong conviction about how future events will unfold.

Related: Changing Investment Strategies After A Market Crash

Think back to the start of the pandemic. As businesses shut down around the world it seemed obvious that global economies would suffer and fall quickly into a massive recession. The stock market crash reinforced that idea. Investors hate uncertainty, but this time it seemed a near certainty that stock markets would continue to fall and remain in a prolonged bear market.

Markets quickly turned around as central banks and governments doled out massive stimulus to keep their economies afloat and their citizens safe at home. Now it became ‘obvious’ that investing in sectors like groceries, cleaning supplies, online commerce, and video technology would produce strong results. Continue Reading…

6 ways to protect your Business from Credit Card Fraud

Image by Pixabay

By Martha Pierson

Special to the Financial Independence Hub

We all want to do our best to provide our customers with the utmost convenience. Isn’t this the whole point of eCommerce, POS financing, and other recent developments in sales?

Unfortunately, with these conveniences also come increased risk. In fact, this article is going to discuss one of the dangers brought about by technology and its added convenience. That is credit card fraud.

Recent statistics point out that 47% of Americans experienced some form of financial identity theft in 2020. More importantly, credit card fraud, especially those related to new accounts, was reported as the second-worst reported following scams related to government benefits.

It is, indeed, very troubling. Fortunately, there are ways to prevent and minimize such malicious attacks. Here are six tips that both business owners and lenders (such as POS finance providers) can put into action:

Tip #1: Invest in Technology

There are numerous technologies that can help minimize credit card fraud. We simply need to take advantage of them.

For instance, declining cards without an EMV chip is a good first step. Not only does EMV provide another level of encryption, but chipped cards also generate unique codes after every transaction. These features make it impossibly difficult for thieves to create counterfeits.

You can also invest in incorporating a fraud prevention system into your eCommerce website. These platforms are easy to integrate and provide real-time protection for every transaction. Most of these programs can help you screen and authenticate customers, prevent fraud, and even identify vulnerable accounts.

You might also want to look into any advanced payment security feature that your eCommerce platform offers as an add-on.

Tip #2: Beware of Red Flags

Speaking of identifying vulnerable accounts, the next best step to prevent credit card fraud is to simply be aware of the red flags. For example, a person reaching for a credit card from his pocket rather than from his wallet is certainly suspicious. The same can be said for an online customer with multiple failed attempts to purchase due to incorrect information.

Of course, we’re not saying that these red flags automatically point out that one is committing fraud for sure. For all we know, that online customer simply had his caps lock on the whole time. Or maybe the previous customer just shoved his credit card into his pocket for no particular reason.

In the end, the skill to discern fraud can simply be achieved over time through the practice of vigilance and experience.

Tip #3: Increase the Quality of Employee Training

So you now have an idea on how to catch credit card fraud. The question is, are your employees equally equipped as well? Unless you manage every aspect of your business on your own, it is imperative for any business owner to make credit card fraud a part of their training.

We also recommend developing a clear procedure that your employees can follow. Here’s an example for in-person transactions.

  • Check the customer’s ID for every credit card transaction.
  • Make sure that the credit card doesn’t look tampered with in any way.
  • Use an Address Verification Service to confirm the cardholder’s billing address.
  • Finally, compare the receipt with the actual card. Check for any errors and inaccuracies. Continue Reading…

What would Employees give up to keep Remote Work? 

By Mike Brown

Special to the Financial Independence Hub

Because of the coronavirus pandemic, there was almost a universal shift to remote work.

It wasn’t supposed to be permanent, just a temporary move to help mitigate the spread of the virus. 

But then employers and employees got used to remote work and some interesting statistics started popping up. A Stanford study of 16,000 workers found working from home increased productivity by 13%, while also leading to improved work satisfaction and a 50% slash in attrition rates. 

A survey by ConnectSolutions found 77% of employees displayed increased productivity if they worked from home just a few times a month. The same study found 30% did more work in less time while working remotely. 

In summation, remote work was a success. 

So successful that now, as the coronavirus pandemic subsides just a bit, there is a fight between employers and employees regarding the return to the office. 

Employees are getting their work done like they always did, sometimes even doing more. They have a case to fight the return to the office. 

In that same vein, employers understand the value of teamwork, camaraderie, and face-to-face interactions. They too have a case to bring back the office.

It will surely be a messy fight mainly because employees now see remote work as part of the new reality, not just a temporary fad. They value their remote work flexibility like they would value salary, benefits, or paid time off, and they will just move to the next employer if their current one makes a return to the office mandatory.

To capture this value placed on remote work, Breeze conducted a survey of 1,000 Americans to see what they would give up if they were able to retain remote work. It’s important to note this survey is meant to capture the value of remote work, not offer suggestions to employers on how they can cut benefits or pay in exchange for remote work.

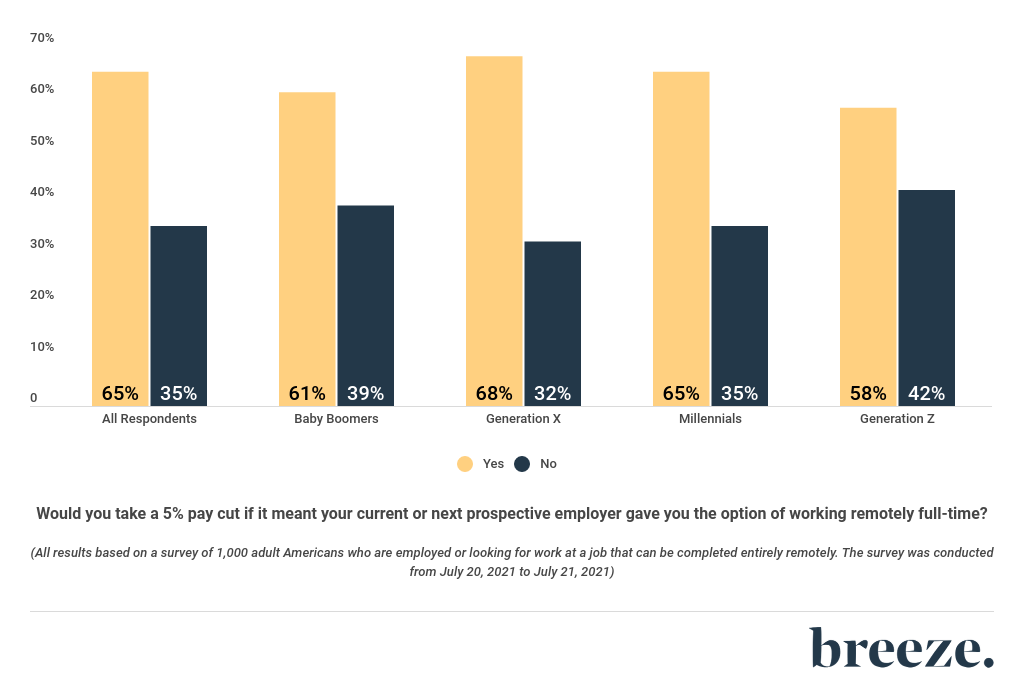
To have the option of working remotely full-time at their current or next employer, 65% of employees would take a 5% pay cut, 38% would take a 10% pay cut, 24% would take a 15% pay cut, 18% would take a 20% pay cut, and 15% would take a 25% pay cut. 

Moreover, 39% would give up health insurance benefits to retain full-time remote work. Breeze found the average monthly health insurance premium is $187, and most workers have a large percentage of this monthly cost picked up by their employers.

With so many willing to give up this crucial employee benefit, it gives you a good sense of the incredible value that is being placed on remote work. Continue Reading…