General

Sustainable Equity Strategies for a Global Recovery

Image iStock/Franklin Templeton

By Mel Bucher, Co-Head of Global Distribution, Martin Currie, Edinburgh, UK

(Sponsor Content)

The investment choices we make can have a profound effect on the world around us. Investing according to sustainable principles allows investors to align their environmental, social and governance (ESG) goals with their investing choices.

Also, we believe sustainability can be a driver of long-term portfolio performance. As global equity markets recover from the COVID-19 pandemic, more Canadians want to invest in opportunities available within a wider sustainable context.

One new option is the sustainability investment expertise that Martin Currie brings to Canada.

Martin Currie may be a new name for many Canadian retail investors. Our firm is a Specialty Investment Manager of Franklin Templeton, based in Edinburgh, UK, and we focus on actively managing portfolios of the listed public equities of companies that generate long-term value from sustainable ESG polices. Our ESG framework helps to identify any material ESG issues related to a company’s cash flow, balance sheet and profit/loss account over time and whether these ESG issues could affect value creation. Having ESG analysis fully embedded in the research process enables our investment teams to uncover material issues.

Martin Currie’s leadership in ESG was recognized with the UN’s Principles for Responsible Investment A+ rating for 2017, 2018, 2019 and 2020.

This article considers our sustainable investing strategies in global equities and emerging markets equities, both of which are now available to Canadians.

A global equity strategy in a global recovery

We expect the strong comeback of the global equity market to be sustained under fairly benign inflation conditions and with asset prices supported by monetary policy. Our global equity strategy is well positioned in this environment.

The Franklin Martin Currie Global Equity strategy invests in companies with exposure to three established growth megatrends:

1.      Demographic change (e.g., aging population, urbanization, healthcare)

2.      Resource scarcity (e.g., electric vehicles, alternative energy, infrastructure)

3.      The future of technology (e.g., outsourcing, cloud computing, security).

We believe these themes will drive long-term structural growth in the global economy. The portfolio seeks diversified holdings with exposures to the megatrends to capture growth.

Global equities for growth, at the right price

The portfolio holds 20-40 stocks of sustainable, well-managed growth companies that dominate their respective industries and have high barriers to entry. They hold pricing power and face a low risk of disruption. These firms have potential for long-term structural growth and value creation. Companies undergo a systematic assessment of their industry, company, portfolio and governance/sustainability risks.

These equities may not be cheap, so the portfolio managers are highly selective about acquiring companies at the right valuations. The goal is to find equities that combine strong industry, financial and governance attributes at the right price.

This global equity strategy is now available to Canadians through the Franklin Martin Currie Global Equity Fund and Franklin Martin Currie Sustainable Global Equity Active ETF (FGSG). The mutual fund’s U.S. equivalent is a 4-star Morningstar-rated fund* in the International Unconstrained Equity category.  

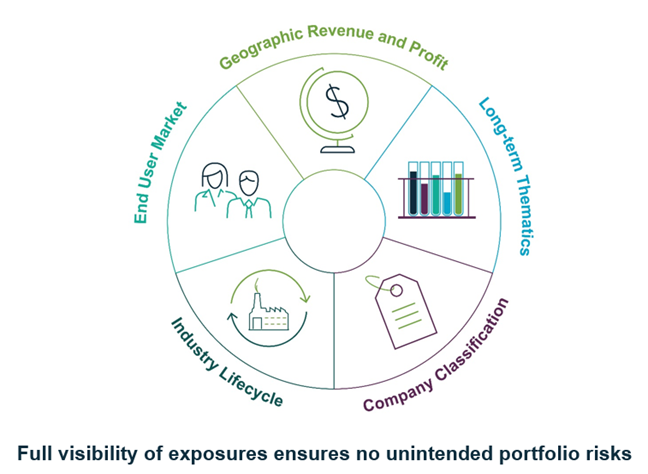
Unique Approach to Portfolio Analysis and Construction
Martin Currie’s sustainable emerging markets strategy Continue Reading…

The dangers in the “Explore” part of a “Core and Explore” Portfolio

By Michael J. Wiener

Special to the Financial Independence Hub

Many people advocate having a portfolio made up of mostly a core of low cost index funds along with a small “explore” part for taking concentrated risks on favourite investments.  This can work well enough if you’re realistic about it, but most investors cross the line to self-delusion.

Ben Carlson does a good job justifying the existence of explore-type investments in his article The Case for Having a Fun Portfolio.  After all, people are entitled to spend their money however they want.  Not every expenditure has to be part of a logical long-term plan.  We can buy a beer, or a motorcycle, or some favourite stock if we want.  So what if the long-term expectation is that the explore part of people’s portfolios will underperform indexes.

All the logic makes sense up to this point.  But just about every stock-picker I know can’t resist taking this a step further.  “Besides, the stock I picked is going to do great.”  In their hearts, they know their stock picks are going to outperform.  Past results don’t seem to deter them.  They wouldn’t bother with the explore part of their portfolios if they truly believed they would lose money over a lifetime of picking stocks.

All the evidence says that professional investors today set good relative prices so that individual investors who choose their own stocks are essentially making random picks.  The odds are against the small guy, but hope springs eternal.  I prefer to find hope in other pursuits.

Michael J. Wiener runs the web site Michael James on Money, where he looks for the right answers to personal finance and investing questions. He’s retired from work as a “math guy in high tech” and has been running his website since 2007.  He’s a former mutual fund investor, former stock picker, now index investor. This blog originally appeared on his site on April 26, 2021 and is republished on the Hub with his permission.  

A sampling of comments from the original post: Continue Reading…

Getting your Fixed Income Fix with BMO ETFs

This article has been sponsored by BMO Canada. All opinions are my own.

Fixed income doesn’t get enough attention on this blog, mostly because I’m still in my accumulation years and invest in 100% equities across all my accounts. But most investors should hold bonds in their portfolio to reduce volatility and so they can rebalance (selling bonds to buy more stocks) whenever stocks fall.

In this post we’re going to take a deep dive into BMO’s line-up of fixed income ETFs. We’ll see that there isn’t a one-size-fits-all approach to investing in fixed income, and that investors can capture yield using a wide array of products and strategies.

DIY investors should be familiar with BMO’s suite of fixed income ETFs. It’s the largest in Canada with more than $23 billion in assets. At the top of the list is BMO’s Aggregate Bond Index ETF (ZAG) with total assets of $5.86 billion.

Robo-advised clients also have BMO fixed income ETFs in their model portfolios:

  • Nest Wealth clients hold BMO Aggregate Bond Index ETF – (ZAG)
  • Wealthsimple clients hold BMO Long Federal Bond Index ETF – (ZFL)
  • Questwealth clients hold BMO High Yield US Corp Bond Hedged to CAD Index ETF – (ZHY)
  • ModernAdvisor clients hold BMO Emerging Markets Bond Hedged to CAD Index ETF – (ZEF)

BMO Fixed Income ETFs

Investors are nervous about holding bonds today. Interest rates are at historic lows, and when rates eventually rise, we’ll see bond prices fall – especially longer duration bonds. We’re also seeing higher inflation, which causes interest rates to go up (and bond values to go down).

Q: Erika, investors are concerned about low bond returns, particularly from long-term government bonds. How should they think about the fixed income side of their portfolio?

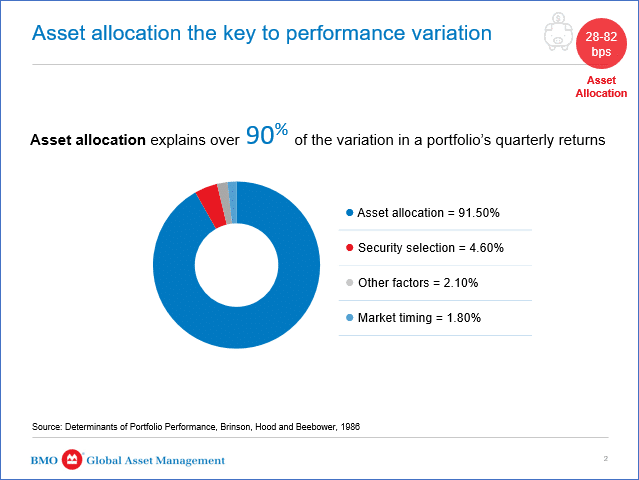
A: Investors should think of fixed income as a ballast in their portfolio. It helps reduce overall volatility (chart below). Correlations between US Treasuries and stocks (represented by the MSCI USA index) have been negative over the last two decades. All that to say, when stocks fall, bonds tend to do well.

BMO figure 1

What the new Higher Stress Test means for Homebuyers

Image courtesy of Loans Canada

By Sean Cooper

Special to the Financial Independence Hub

Ever since the start of COVID, the real estate market has been on fire. To help deal with the record level of activity in the real estate market and also keep things balanced, a new mortgage stress test was introduced June 1st. In this article we’ll look at the new mortgage stress test and how it affects you.

What’s the Stress Test?

The stress test is a measure that anyone buying a home, refinancing their mortgage or switching mortgage lenders must pass. Pretty much the only time you don’t have to pass the stress test is when you’re renewing your mortgage with your existing lender. Whether you’re buying a home with less or more than 20 per cent, it doesn’t matter. You’re affected by the stress test.

The stress test was introduced several years back to help protect homebuyers from becoming overleveraged and taking on too much mortgage debt. Prior to the stress test, you only had to prove that you could afford mortgage payments based on the mortgage rate when you first sign up for your mortgage. However, with Canadians spending more and more on homes and the threat of higher interest rates looming, the Canadian government decided to introduce the stress test in early 2018 out of precaution.

To pass the stress test, you need to show that you can qualify at the greater of your mortgage rate plus two per cent and the stress test rate (currently at 5.25 per cent). With mortgage rates currently somewhere in between the mid one percent’s and the mid two per cent’s for both fixed and variable rate mortgages, you’ll almost always have to qualify at 5.25 per cent as things stand today.

How has the Stress Test changed?

The new stress test rules came into effect June 1st. Prior to the introduction of the new stress test rules, the mortgage stress test rate was 4.79 per cent. That’s because it was based on the average of the big banks’ posted mortgage rates. However, the government decided to change how the stress test was calculated. Continue Reading…

Checking in on the Canadian Wide-Moat Portfolio

By Dale Roberts, cutthecrapinvesting

Special to the Financial Independence Hub

It’s a trade-off. I hold a concentrated portfolio of Canadian stocks. What I give up in greater diversification, I gain in the business strength and potential for the companies that I own to not fail. They have wide moats or exist in an oligopoly situation. For the majority of the Canadian component of my RRSP account I own 7 companies in the banking, telco and pipeline space. I like to call it the Canadian wide moat portfolio.

Like many Canadian investors I discovered over the years that my Canadian stocks that pay very generous dividends were beating the performance of the market. You’ll find that market-beating event demonstrated by the Beat The TSX Portfolio. Eventually, I moved to the stock portfolio approach.

Over longer periods you’ll see that BTSX beat the TSX 60 by 2% annual or more. And as always, past performance does not guarantee future returns.

For the bulk of my Canadian contingent I hold 7 stocks.

Canadian banking.

Royal Bank of Canada, Toronto-Dominion Bank and Scotiabank.

Telco space.

Bell Canada and Telus.

Pipelines.

Canada’s two big pipelines are Enbridge and TC Energy (formerly TransCanada Pipelines).

My followers on Seeking Alpha or Cut The Crap Investing readers will know that I also own Canadian energy producers, gold stocks and gold price ETFs (holding gold) and the all-in-one real asset ETF from Purpose. I also own Canadian bonds and bitcoin.

We hold our cash with EQ Bank.

Related reads:

Investing in Canadian banks.

Investing in Canadian telco stocks.

For the U.S. component there is a basket of U.S. stocks. Here’s an update of our U.S. stock portfolio. That portfolio continues to provide impressive market-beating performance.

The performance update

Here’s the Canadian wide moat 7 from 2014 vs the TSX Composite. I slightly overweight to the telcos and banks. For demonstration purposes the portfolio is not rebalanced. When reinvesting I usually throw the money at the most beaten-up stock. That would be a reinvestment idea that seeks value and greater income, the general approach of the Beat The TSX Portfolio.

Charts courtesy of Portfolio Visualizer

Annualized returns and volatility

The Canadian Wide Moat 7 has delivered greater total returns and with less volatility and drawdowns in corrections.

And of course the portfolio dividend income is more than impressive. I did not create portfolio exclusively based on the generous and growing income, but it is a wonderful by-product. The following is based on a hypothetical $10,000 portfolio start amount. The starting yield is above 4%, growing towards a 9% yield based on the 2014 start date.

In the above, the dividends are reinvested. For example, the Telus dividend is reinvested in Telus. While I will take a total return approach for retirement funding, the generous portfolio income contribution will add a dimension that will help reduce the sequence of returns risk.

The Canadian wider moat portfolio

I know the concentrated portfolio can face criticism (rightly or wrongly). Certainly, don’t try this at home based on what this guy does. Given the concentration risk I did expand the wide moat list for readers on Seeking Alpha. I had offered up the Canadian railways and grocers. That is a nice combo of industrials and more defensive consumer staples. Continue Reading…