Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

How millennials can find Financial Independence


By Mark Seed
Special to the Financial Independence Hub

New year, same movement. The FIRE (Financial Independence, Retire Early) movement remains a big thing.

How can millennials find financial independence?

Can millennials find FI via leverage?

What questions are millennials asking themselves when it comes to wealth building, saving and investing?

This post explores some answers: how millennials can find financial independence.

What do millennials want? Some millennials want financial independence!

While some age ranges will vary depending on the report you read, the millennial cohort (GenY) was born between 1981 and 1995, which puts millennials in the age range of 27-41 in 2022.

As you well know from my site, and my own journey, I believe your 30s are critical years to define your financial wellbeing. Many important life decisions are made during this period of life, such as career selection, buying a house, potentially getting married, starting a family, and much more.

The lifestyle and consumption decisions you make in your 30s could very well define your 40s and future decades, including how much wealth you can build.

In the succinct and well-written book If You Can – How Millennials Can Get Rich Slowly by William Bernstein, there is a simple five-step formula to help millennial investors realize some financial independence dreams. I encourage any 20- or 30-something reading this site to download and read that FREE e-book from my link above or below. I think it will be impactful.

While some millennials will be the major recipients of some of the largest wealth transfers in history, now underway from a mix of older GenX and Boomer parents, via large financial gifts, I suspect some millennials will not have that luxury to rely on for their financial footing.

This means many millennials will need to do what I have done: make their financial independence dreams happen on their own.

Personally, I’m a huge believer in charting your own financial path and not relying on others to do it for you. Sure, you’ll make money mistakes along the way (I have) but you’ll also learn to think for yourself and hopefully hone some critical thinking skills along the way.

Further Reading: My lessons learned in diversification. 

Millennial investor profile – Liquid from Freedom 35 Blog

For many years now, I’ve been inspired and motivated by financial independence. So have other investors that I’ve had the good fortunate to connect with by running this blog. So, in that light, I’ve also been inspired by their stories and what they do differently.

You can read many of those stories on this dedicated Retirement page here. I’ll link to some others below.

One blogger in particular that has an interesting story and some lessons to share is “Liquid” from Freedom 35 Blog.

Liquid moved out of his parent’s basement when he was 21 and hasn’t looked back – paying off some small student loans and building up his net worth recently (now in his mid-30s) to $1.5 million. His long-term goal was always to be “financially free before his 35th birthday”. That goal is now achieved. He ’got there’ by controlled leverage, value investing, taking advantage of market corrections, swing trading, dividend investing, alternative investing and more.

I thought it would be fun to have Liquid on the site, share a bit of his story, and discuss how he used leverage wisely to realize some financial independence dreams far earlier than most.

Liquid, welcome to the site and thanks for your time!

My pleasure Mark and very happy to spend time with you and your readers!

When it comes to our financial journey in general, I know we’re just ‘not there yet’ and I’ve got a few years on you! We are I believe, on a decent path – saving, investing and killing mortgage debt at the same time. Folks are quite familiar with my plan but maybe not so much about you!

Tell us about yourself? In what field do you work, did you work in?

Thanks Mark. Well, I have been enamored with finance and business since I was 18. But despite my best efforts to get into business school I was rejected because of my poor grades. I ended up taking applied sciences instead. But that was a mistake. The program was so difficult I failed all my classes. I was forced to drop out after the first year.

After flunking college, I found a job at Safeway, making minimum wage. Luckily, I was still living with my parents at the time.

One day in 2007 I noticed a local art school was offering a one-year program in graphic design. I’m clearly not academically gifted. But maybe I can draw. I thought it was worth a shot. So, I enrolled.

I received my diploma the following year at age 21 and began my career as a graphic designer. My starting annual salary was $35,000.

Today I’m a senior designer at a large entertainment firm making $75,000 a year. Although it wasn’t my first choice, I am happy with my career decision and how it turned out. The pay is decent. And I can save money to pursue what I’m truly passionate about – finance and investing.

Great stuff. You have found your passion with investing for sure. How did you get started with investing? When did you start investing? What is your investing approach?

In 2009 I wanted to move out of my parents’ basement. After considering my options I concluded that buying was better than renting. So, I purchased a 2-bedroom apartment in Vancouver for $230,000.

This was my first investment, and my first home. At this time, I had $15,000 in personal savings. Not much. But it was enough to cover the downpayment and closing costs. Then I began to invest in the stock market, and other asset classes.

My investing approach can be broken down into 2 parts.

The first part is to mimic the strategies used by the best investors.

Allan Mecham was a college dropout like me. But he managed a fund that compounded at 30% a year.

Activist investor Bill Ackman produced a 70% investment return in 2020. But his long-term record is more like 20% a year, which is still pretty good. Macro investor George Soros managed a fund that returned 30% a year on average for many decades. And of course, value investors like Mohnish Pabrai and Warren Buffett have outstanding long term track records as well.

These public figures in the investment sphere have written books, appeared in interviews, and spoken on podcasts to discuss their ideas, strategies, and outlooks on the markets. Bill Ackman even has a list of 8 core principles that he uses to screen investments. Whenever he deviates from those principles his performance suffers. Furthermore, it’s easy to find exactly what these investors are buying because they have to submit 13F filings regularly to disclose their holdings publicly.

By understanding what these successful investors are doing with their money, I can essentially copy their methods and buy the same stocks as them. This naturally leads to my portfolio having the same kind of high returns as them.

Often the top performing investors will like the same stocks. But sometimes their strategies diverge so I have to decide which one works the best for my situation.

This brings me to the second part of my investing approach, which is to document my investment transactions and track the results. I like to use a spreadsheet for this. I also like to track my thought process, and the reason for making my decisions. This allows me to go back, review what happened, keep what worked, and throw away what didn’t so I can improve my process for next time. This experience has helped me become a better investor over time.

Copy the best, or at least tailor what the best do for you. Good stuff. So Liquid, like some other millennial bloggers are you a fan of FIRE? Why or why not? Have you achieved FIRE or FI? What is the key difference in your opinion between FIRE / retired early or FI or are they same to you?

As a kid I was constantly being told what to do (or not do) by others, and it was frustrating. Despite all the guidance I still felt a lack of direction. However, once I grew up and started to live on my own terms, I began to discover more purpose in life. I was free to make my own decisions and it was liberating. There was just one problem. I still had to work to put food on the table. That’s when I discovered financial independence.

I deeply value freedom so I made it a priority to become wealthy. I’m a fan of FI, but I don’t know about FIRE. I achieved financial independence in 2020 so I consider myself to be FI right now. I’m turning 35 later this spring. And that’s when I will hand in my letter of resignation and quit my 9 to 5 job permanently. Although I will be retired from full time work, I wouldn’t consider myself to be “retired.” There is no universal consensus on what retirement means anymore as the world embraces Web 3.0 and the gig economy.

You’ve had some interesting investments over the years on your path to FI. Can you highlight some investing successes or mistakes along the way? What did you learn from those lessons to help you move forward that might help other millennials reading this?

I’ve been very fortunate to see high returns investing in exotic assets such as Zimbabwe’s banknotes and Playboy magazines.

(Mark: that’s funny but good!)

But I often learn the most from the investments that didn’t do well.

One of my earlier investing mistakes was buying a leveraged volatility ETF that makes trades in the futures market. I knew this fund was risky, but I didn’t really understand what made it so. I initially wanted to make a quick swing trade. But when the ETF’s price fell, I held on – waiting for a reversal instead of cutting my losses. That was the wrong decision. Eventually a lower VIX and the adverse effects of contango wiped out 99% of my position, and I lost $2,000. From then on, I only invest in things that I actually understand. I learned the importance of knowing what I own. Today I can explain any investment I have to a 4th grader, and I can delineate why I own it. Continue Reading…
How Real-Return Bonds compare to Regular Bonds

 
ultimate guide to bonds

Real-return bonds pay a return adjusted for inflation. But when you buy a real-return bond, you are only protecting yourself against unanticipated rises in inflation.

Real-return bonds pay you a rate of return that’s adjusted for inflation, but that’s not always as promising as it seems.

When a real-return bond is issued, the level of the consumer price index (CPI) on that date is applied to the bond. After that, both the principal and interest payments are typically adjusted every six months, upwards or downwards from that base level, to compensate for a rise or fall in the CPI.

Look at this theoretical example to understand how a real-return bond works

The Bank of Canada issues $400 million of 30-year bonds maturing on December 1, 2049. The bonds have a coupon, or interest rate, of 2%.

If after six months from the date of issue, the new CPI level is, say, 1% above the level of the CPI on the issue date, then each $1,000 of bond principal is adjusted to $1,010 of bond principal ($1,000 x 1.01). The semi-annual interest payment is then $10.10 ($1,010 x 2% / 2).

If after 12 months, the level is 2% higher, then the bond principal is adjusted to $1,020 ($1,000 x 1.02), and the interest payment rises to $10.20 ($1,020 x 2% / 2).

Consider these three important factors to realize benefits with real-return bonds

  1. The price you pay for real-return bonds reflects the anticipated rate of inflation. In other words, if investors feel that inflation will rise 2% over the long term, the price of the bond will reflect that future inflation increase and its effect on the bond’s principal and interest payments. So, when you buy a real-return bond, you are only protecting yourself against unanticipated rises in inflation.
  2. When the inflation rate falls over a six-month period, the principal and interest payments of a real-return bond fall. In times of deflation, the inflation rate turns negative. In a prolonged period of deflation, the principal of a real-return bond could fall below the purchase price. Interest payments would fall, as well.
  3. As with regular bonds, holders of real-return bonds must pay tax on interest payments at the same rate as ordinary income. That income gets taxed at the investor’s marginal rate. In addition, holders of real-return bonds must also report the amount by which the inflation-adjusted principal rises each year, as interest income, even though you won’t receive that amount until the bond matures. That amount is added to the bond’s adjusted cost base.

If the CPI level falls, that reduces the inflation-adjusted principal. You deduct the amount of that reduction from your taxable interest income that year, and also subtract it from the adjusted cost base.

Download this free report to learn more about how to profit from stock investing.

Find out how real-return bonds compare to regular bonds and if they make better additions to your portfolio

In simple terms, a bond is a form of lending whereby you lend money to a corporation or government. In return, a bond pays a fixed rate of interest during its life. Eventually, a bond matures, and holders get the bond’s face value—but nothing more. Receiving the fixed interest and face value at maturity is the best that can happen. Note, though, that in some cases, corporate bonds can go into default. As well, inflation can devastate the purchasing power of bonds and other fixed-return investments.

Furthermore, bonds also generate more commission fees and income for your broker, compared to stocks, especially if you buy them via bond funds and other investment products. Continue Reading…

Dealers putting Clients’ Retirements in Jeopardy

By Nick Barisheff

Special to the Findependence Hub

Over time, most investment dealers have implemented misguided policies that will negatively affect their clients’ investment portfolios and their ability to achieve a secure retirement.

There are two main policies that have negative impacts on investors’ portfolios. One is restricting investments to a client’s original Risk Tolerance in the Know Your Client application form (KYC). When opening an account, the client will advise the dealer of their Risk Tolerance.  Most clients will indicate that they are medium risk. On March 8, 2017, the Ontario Securities Commission (OSC) implemented risk rating rules that require all mutual funds to rate their fund according to 10-year standard deviation. In 2018, I published an article entitled New Mandatory Risk Rating is Misleading Canadian investors.

Prior to the OSC’s implementation of the risk rating rules, on December 13, 2013, the OSC issued CSA Notice 81-324 and Request to Comment – Proposed CSA Mutual Fund Risk Classification Methodology for Use in Fund Facts. My comments on this policy were submitted to the OSC on March 12, 2014, along with comments from 50 other industry experts.  

I presented a paper to the OSC that argued that Standard Deviation is not an appropriate measure of risk, since the best-performing mutual fund and the worst-performing mutual fund in Canada had the same Standard Deviation.  The measure of Standard Deviation of an investment does not reduce the risk of incurring losses.

A better, more accurate methodology would have used downside standard deviation or the Sharpe or Sortino ratios which measure risk adjusted returns. Nevertheless, the OSC implemented risk rating rules requiring all mutual funds to rate the risk of their funds according to 10 year standard deviation.

As a result, if investments in a client’s portfolio exceeded the risk tolerance as indicated in the original KYC, the client was forced to redeem those investments, by the advisor’s compliance department. A number of BMG’s clients were forced to redeem their positions since our funds had a medium-high risk rating according to the OSC formula, and the clients’ KYC indicated medium-risk tolerance. A number of clients wanted to change the KYC in order to allow them to maintain ownership of our funds but were advised that, unless there was a significant change in their financial circumstances, they could not change their KYC. Continue Reading…

Spooked by the stock market? Here’s the answer

By Dale Roberts, cutthecrapinvesting

Special to the Financial Independence Hub

Most investors do not like volatility. They do not like looking at their investment account balance observing that they’ve ‘lost money.’

Of course, you have not lost money until you buy an asset at a certain price and then sell at a lower price. You’ve then just realized your losses. You have not lost money when your portfolio value goes down. And in fact, swings in portfolio values are just par for the course. Stocks and bonds and real estate change in price (with wild swings at times) in regular fashion: it’s normal behaviour. If the stock markets have you spooked, there is a simple and timeless plan of action.

With this strategy, you can ‘win’ if stocks go up. You can win if stocks go down. It’s a strategy that worked during the worst period in stock market history: the Great Depression of the 1930s .

The answer of course is adding money on a regular schedule. In the investment world they call it dollar cost averaging; we can abbreviate that to DCA. There is no need to guess about which way the market is going to go today, next week, next month, next year, or even the next five years. We simply expect or hope that the markets will go up over longer periods, as they have throughout history.

Stock market history

U.S. stocks, S&P 500

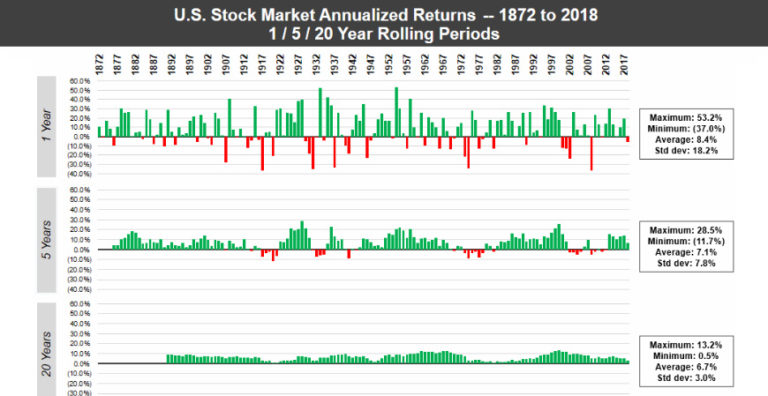
You can see that there is lots of green on the board. Stocks mostly go up. It is those pink years (on the table) that usually trip up many investors

The key to long-term wealth building is being able to invest through those down years. And in fact, adding money in those years is quite beneficial as the stocks go on sale.

But keep in mind that stocks can stay under water for extended periods.

Dollar cost averaging

Now this is a consideration for those who have very little exposure to stocks, or who have been out of the markets for quite some time. That event is not as rare as you might think. Many investors have left the markets, though they recognize that they need to be invested to reach their financial goals and enjoy a prosperous retirement. They also want their wealth protected from inflation.

Here’s the demonstration: investing through the initial stages of the Great Depression.

In the above charts we see equal amounts invested, but the dollar cost averaging strategy still delivered positive returns in a vicious bear market. Buying at those lower prices was very beneficial. Now keep in mind for the above to work, the markets have to go up over time. They have to recover. And historically they have.

Time reduces risk

Here is a wonderful graphic that demonstrates the returns over various periods. Our odds increase as we lengthen the time period that we remain invested.

And a table that frames the probabilities of positive returns.

Charlie Bilello

Spread out that lump sum

If you are sitting on a large sum that you want to get invested you will have to have a plan. Over what time period should you get those monies into the market?

If you start investing and the markets keep going up, great. Mission accomplished. The money you’ve invested has increased in value. You are collecting dividends along the way.

But of course when we enter a stock market correction, your total portfolio value will decline. Though you might get enough of a head start so that your money invested remains in positive territory.

At that point when markets are declining, remember that lower prices are good. The stocks are going on sale. And of course, you do not have to invest in an all-equity portfolio. You can dollar cost average into a balanced portfolio.

I’d suggest that you spread the money out over 2 or 3 years. For example, If you are on the 2-year plan and have $100,000 to invest and you’re investing every month, you’d invest $4,167 per month.

You can’t time the markets

For those who already have substantial assets invested, you can’t move in and out of the markets. We don’t know when the corrections will occur. The most reasonable course of actions is still dollar cost averaging. That said, whenever you have money to invest, stock market history says get it invested. The sooner the better.

From My Own Advisor here ‘s – Dollar cost averaging vs lump sum investing.

Invest within your risk tolerance level

This is key. If you get scared and sell, you might lose money.

You might have to accept a lower-risk portfolio that is likely to earn less over time compared to a more aggressive stock-heavy portfolio or balanced portfolio. It’s also possible that you do not have the risk tolerance to invest (at all), even in a very conservative ETF portfolio. If that is the case you would have to stick with GICs and high-interest savings accounts. You might add to your real estate exposure for growth. In retirement, you might use annuities to boost your income.

For savings we use EQ Bank. 3-and 6-month GIC’s now 2.05%

To help gauge your risk tolerance level and the appropriate level of portfolio risk, please have a read of the core couch potato portfolios on MoneySense. You’ll find a table within that post that breaks it down.

If you are risk averse, you likely need a managed portfolio and advice. You might consider a Canadian Robo Advisor. These investment companies provide lower-fee portfolios at various risk levels. Advice is also included. A few of these firms also offer financial planning.

At Justwealth, you get access to advice and financial planning. In fact, you’ll have your own dedicated advisor.

Justwealth. The Canadian Robo Advisor that knows when to get personal.

They will do a risk evaluation to see if investing is right for you, and then you will be placed in the appropriate portfolio(s). And once again, you’ll be offered the greater financial plan as well.

Start investing

Preet [Banerjee] puts some of the above in video form [YouTube.com]. Preet also goes over how much you might market over various time frames, at different rates of return.

The key is to not be frozen on the sidelines. We might refer to that as ‘paralysis by analysis’.

Build wealth at your own comfort level, at your own pace. You will learn as you go. You can build up your comfort level for risk and volatility. It’s quite possible that you can increase your risk tolerance level over time. We develop risk callouses.

Walk before you run, perhaps.

Robo Advisors are a great training ground for investors.

Thanks for reading. We’ll see you in the comment section. If you’re not sure what to do, feel free to flip me a note.

Dale Roberts is the Chief Disruptor at cutthecrapinvesting.com. A former ad guy and investment advisor, Dale now helps Canadians say goodbye to paying some of the highest investment fees in the world. This blog originally appeared on Dale’s site on Feb. 12, 2022 and is republished on the Hub with his permission.

MoneySense Retired Money: CDRs reduce currency risk of US stocks for Canadian investors

https://www.neo.inc/

My latest MoneySense Retired Money column looks at the newish CDRs, or Canadian Depositary Receipts. You can find the full column by clicking on the highlighted text: CDRs versus U.S. Blue-chip stocks: which makes more sense for Canadian investors?

CDRs resemble the much more established American Depositary Receipts (ADRs), which I’d wager most seasoned investors have used. See also this article on CDRs republished on the Hub early in 2022: Should you invest in CDRs? 

ADRs were launched by J.P. Morgan in 1927 for the British retailer Selfridges and are a way to gain easy access to global stocks in US dollars trading on US stock exchanges. According to Seeking Alpha, among the ten most actively traded ADRs are China’s Baidu [Bidu/Nasdaq], the UK’s BP [BP/NYSE], Brazil’s Vale [Vale/NYSE], and Switzerland’s Novartis. Here’s Wikipedia’s entry on ADRs.

Dividends paid by ADRs are in US dollars. Canadians are of course free to buy ADRs just as they buy US stocks or US ETFs trading on American stock exchanges. But they will have to convert their C$ to US$ to do so, and ultimately if they plan to retire here, they will have to pay again to repatriate that money.

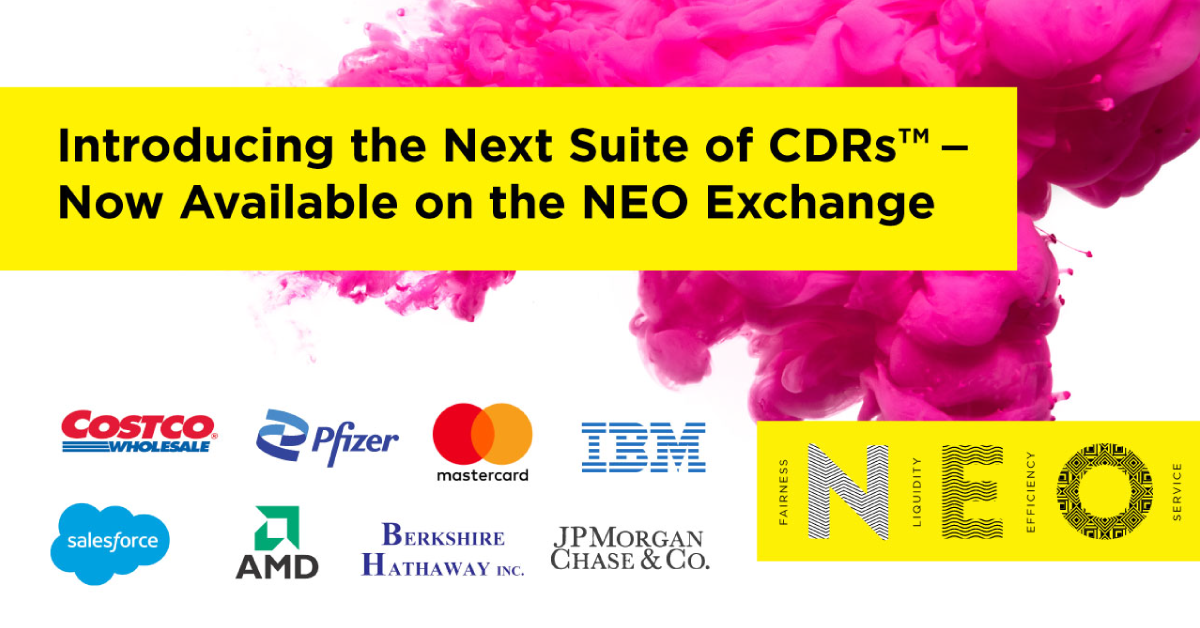
By contrast, CDRs give Canadian investors a way to buy popular US stocks (particularly the FAANG stocks) in Canadian dollars and trading on the Canadian NEO exchange. As you can see in the above image, there are also such popular stocks as Pfizer, Berkshire Hathaway, IBM and MasterCard. You can find more information at CIBC, which developed CDRs. As you might expect, CIBC puts a positive spin on CDRs, saying they provide the “same stocks, lower risks,” with a “built-in currency hedge,” while also offering “fractional ownership, easier diversification.”

They even went so far as to trademark the slogan “Own the company, not the currency.” A video found here says that while Canadian stocks only account for 3.1% of the world’s stock market capitalization, most Canadians have 59% of their investments in Canadian stocks. To the extent foreign [and especially American] stocks have generated stronger returns, arguably Canadians are missing out. It suggests that one reason for this is Foreign Exchange.

CDRs may be of particular advantage to younger investors with limited wealth, since they are a way of accessing high-priced stocks that may have prohibitive minimum investments. For example, Amazon (AMZN) currently costs a whopping US $3,200 for a single share. Compare that to the CDR version, AMZN.NE, which costs just C$20 a share. Generally, the CDR version has the same ticker as the underlying US stock, so be careful when you are buying to specify which version you wish to acquire.

If the US company pays a dividend, then so will the CDR. The two main advantages then are that you don’t get dinged on currency conversions between the US and Canadian dollar, and those with modest amounts to invest have the equivalent of buying fractional shares in some of their favorite stocks. Since most retirees will spend their golden years in Canada, you can diversify beyond Canada’s resource and financial-concentrated market, but still have your assets and dividends in Canadian dollars.

CDRs still count as Foreign Content

When I first heard about CDRs, I had a faint hope that perhaps they would not be considered foreign content by the Canada Revenue Agency. However, that is not the case. So investors with large foreign taxable portfolios will be disappointed to learn that even though they trade in Toronto, CDRs are still considered foreign content, so must be included in the CRA’s requirement that portfolios with more than C$100,000 (book value) must complete its T1135 Foreign Income Verification Statement.  The MoneySense column goes into this aspect in more depth.