Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

The Dividend Aristocrats for Retirement


By Dale Roberts, cutthecrapinvesting

Special to the Financial Independence Hub

The Dividend Aristocrats are U.S. stocks (members of the S&P 500) that have increased their dividends for at least 25 years or more. That index methodology will find incredible quality and it also offers a large cap bias. Large cap (capitalization) means that the companies are at the higher end with respect to what it would take to buy the company outright. It is the number of shares multiplied by the share price. The Aristocrat methodology has outperformed the market, and with lesser volatility. That might make it a solid approach for the U.S. stock component for a retiree, or for one who seeks better risk-adjusted returns. We’re looking at the Dividend Aristocrats for retirement, on The Sunday Reads.

Now certainly, when we bring up the subject of dividend investing, that will split many investors and stock market watchers into two separate camps. Many feel that it is a superior form of investing. At the other end of the entrenched opinion – dividends have absolutely nothing to do with investment success. They will argue that it is a zero sum game, the company is simply giving you money by way of a dividend and that reduces the value of the company by an equal amount.

What do those dividends find?

If we want to think of dividends or dividend investing as a factor, the argument can be that dividends find certain kinds of companies. Of course dividend investing will almost always find profitability (unless they’re faking it). Most dividends seek dividend growth and that can find companies with a longer history of increasing profits and increasing free cash flow. And when you stretch that dividend growth history to 10, 15, 20, 25 or 50 years that can find higher quality companies with incredible track records, sustainable moats and durable business models. While certainly not foolproof, the approach can lessen the chance of failure within a stock or large basket of stocks.

This post from S&P Global, the importance of stable dividend income offers this quote and fact …

Across all of the time horizons measured, the S&P 500 Dividend Aristocrats exhibited higher returns with lower volatility compared with the S&P 500, resulting in higher Sharpe ratios.

Better risk adjusted returns is appealing for many. But it can have even more importance for the retiree, as we have that sequence of returns risk.

Ploutos, Seeking Alpha

On Seeking Alpha, author Ferdis tracks and measures the quality of each Dividend Aristocrat. Here’s the most recent Dividend Aristocrats ranked by quality scores.

Readers will know that for our U.S. stock portfolio the approach has found many U.S. Dividend Aristocrats, so I like to check in on the Ferdis reports to see where our Aristocrats stand on the Ferdis scale. I continue to find that our Aristocrats are in the top echelons of quality. In fact the only stock at the bottom of the scale is our only loser – Walgreens.

The Dividend Achievers skims

From that U.S. portfolio link you’ll see that I skimmed 15 of the largest cap Achievers in early 2015. That index methodology insists on at least 10 years of dividend growth, and the Dividend Achievers (Appreciation) index applies proprietary financial health screens. Our stock performance suggests that the index skimming exercise found enough growth and truly excelled at that quality ‘thing’. Within the original mix of stocks were several Dividend Aristocrats.

I took a look at our U.S. portfolio returns and then offered this comment on the Ferdis post …

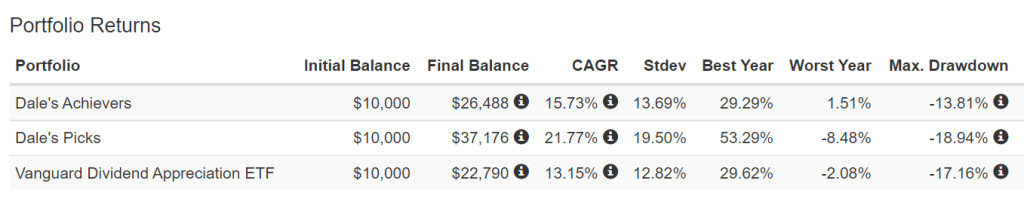
From my 2015 start date I beat the Aristocrats Index (ETF NOBL) by about 2.7% annual with much better risk adjusted returns. So ya, quality works. In the COVID correction I had about 35% less draw down. Dale’s Achievers were down by less than 21% in the correction.

Solid returns with lesser volatility and less draw down in major corrections was exactly the rationale for embracing the Achievers and Aristocrats for retirement.

And then when you add in a few solid quality U.S (no brainer) picks with decent growth prospects.

Our total U.S. returns are even more exaggerated as the 3 picks beat the Appreciation fund by 7.5% annual. They are AAPL, BLK and BRK.B (as a defensive stock market correction hedge – that’s an underperformer for the period).

That growth kicker has contributed greatly to the wonderful performance. As always past performance does not guarantee future returns.

Here’s the summary in chart form.

And setting the table for retirement.
Equal weight by stocks or ETF

An additional ‘bonus’ is that you can choose to equal weight the stocks. And that’s exactly what also happens within the Dividend Aristocrat Index. Here’s the current sector mix. The index is equal-weighted, that can contribute to a value tilt as well (finding greater current earnings accompanied by generous growth prospects). Continue Reading…
Overlooked retirement income and planning considerations

By Mark Seed, MyOwnAdvisor

Special to the Financial Independence Hub

I’ve updated this retirement income planning post to reflect some current thoughts. Check it out!

I’ve mentioned this a few times on my site: there is a wealth of information about asset accumulation, how to save within your registered and non-registered accounts to plan for retirement. There is far less information about asset decumulation including approaches to earn income in retirement.

Thankfully there are a few great resources available to aspiring retirees and those in retirement – some of those resources I’ve written about before.

Retirement income and planning articles on my site:

One of my favourite books about generating retirement income is one by Daryl Diamond, The Retirement Income Blueprint. 

An article about creating a cash wedge as you open up the investment taps.

A review about The Real Retirement.

These are six big mistakes in retirement to avoid.

A review of how to generate Retirement Income for Life.

This is my bucket approach to earning income in retirement.

Here are 4 simple ways to generate more retirement income.

Can you have too much dividend income? (I doubt it!)

Other resources and drawdown ideas:

Instead of focusing on the 4% rule, you can drawdown your portfolio via Variable Percentage Withdrawal (VPW).

A reminder the 4% rule doesn’t work for everyone. Some people ignore the 4% rule altogether.

Getting older but my planning approach stays the same

As I get older, I’m gravitating more and more this aforementioned “bucket approach” for retirement income purposes. This bucket approach consists of three key buckets in our personal portfolio to address our needs:

  • a bucket of cash savings
  • a bucket of dividend paying stocks
  • a bucket of a few equity Exchange Traded Funds (ETFs).

My Own Advisor Bucket Approach May 2019

5 Harvest ETFs have yields over 5%

(Sponsor Content)

As interest rates have fallen, investors who have traditionally relied on bonds and bond-like investments for income have faced tough decisions. Finding safe and predictable income streams has been a challenge.

For many, this has meant turning to equities, particularly global brand leaders with strong businesses. While the share price of these companies rises and fall with the broader economy, they have strengths that allow them to continue to remain profitable in downturns while continuing to pay dividends.

A diversified portfolio of these large-capitalization multinationals helps to protect against economic risk and offers shelter and opportunity. The companies have strong cash flow and balance sheets, well-established businesses and a commitment to dividend growh. In downturns, their share prices tend to fall the least and recover first.

This strategy is at the heart of the Harvest ETFs philosophy. Harvest offers simple, transparent, competitively priced Exchange Traded Funds (ETFs) that own the most successful global businesses. Over time these companies generate steady growth and income. The Harvest way can be summarized as: Global leaders = high income + long term growth.

This thinking led Harvest to create a suite of ETFs that combine capital growth opportunity and monthly distributions with tax efficient current yields of between 5 and 8%.[i]

Harvest achieves this yield in two ways. It chooses global leaders, or the biggest and most dominant companies in their industry. The companies must have a history of profitability and weathering all economic cycles, plus a record of paying dividends that tend to rise over time.

Second, Harvest enriches the returns with a covered call strategy. Harvest is third largest option writing firm in Canada with seven of its 13 ETF’s having option writing strategies.

The covered call strategy adds to the basic dividend income safely by selling a portion of the potential rise in stock price in exchange for a fee. The fee limits the gain a bit, but it also acts as a cushion if share prices fall, because the fee is kept no matter what. Continue Reading…

Are you suffering from investing bias?

Overview

Situation: Nobody is immune from the adverse ramifications of investing bias.
Symptom: Left unchecked, your bias can inflict long-lasting portfolio damage.
Solution:  Recognize your biased patterns and muster up willpower to change.
Summary:  Stop emotional attachments and adopt rational decision making.

“The art of being wise is the art of knowing what to overlook.”
— William James (1842 – 1910) American psychologist and philosopher.

Our investment behaviours are dramatically influenced by the bias we keep. Left unchecked, bias can inflict long-lasting portfolio damage, such as lower returns. The goal is to become aware of how bias affects the outcomes of investing behaviours. My challenge is extended to all investors.
Bias has many definitions, such as, “a preference or an inclination, especially one that inhibits impartial judgment.” Too many portfolios are devastated by various signs of biased investing. Resolve to unravel the consequences of biased investing to regain a portfolio with purpose.

Recognize and make adjustments to bias that is holding back your money management. Step out of your comfort zone and revisit your biased behaviours. All investors can resolve to make simple and sensible bias alterations. This process helps us become better investors.

Nobody is immune from the adverse implications of investing bias. Researchers point out that our brains are wired with many preset investment bias, professionals included. Thankfully, the wiring is easily changed. In addition, portfolio managers devote plenty of effort in minimizing the affects of bias found in client portfolios.

Delving into a few amusing behaviours of investing is a fascinating subject. My favourite is the impatience bias that grandmas and grandpas don’t have.

Change this wiring soon

I highlight a few important biases for you to recognize and change:

• Over-confidence bias: The most common investor bias by far is over-confidence. That is, believing that we are more savvy and wise about particular investment strategies than we actually are. Over-confidence often leads to quick decisions that we later regret. For example, investing too much money into one or two “surefire” stock selections.

• Confirmation bias: Investors have built-in desires to find facts, figures, data, trends, information, people and institutions that agree with their existing views. Then they ignore all the other people and data that contradict existing beliefs and positions. Does it sound close to home?

• Recency bias: Your next investment decision can be unduly influenced by the outcome of your last trade. You are more receptive to investing if you just realized a gain, versus if you realized a loss. Regardless of whether or not the investment climate is right for you.

• Impatience bias: Have you noticed that grandmas and grandpas seldom get mad or annoyed for very long with their grandchildren? In contrast, the children’s moms and dads may reach the hot point with the same children much sooner. This observation also applies to their investment portfolios. Those grandmas and grandpas have more patience with portfolio outcomes, versus their sons and daughters. Consequently, the moms and dads reach more emotional resolutions and/or fewer logical decisions than grandmas and grandpas. This is an easy one to correct. Continue Reading…

Gold still shines but watch China

Financial advisors should ensure that gold comprises 20% of their clients’ portfolios to improve their return and lower volatility, Nick Barisheff, CEO of BMG Group Inc. in Markham told Wealth Professional.

“From an advisor’s point of view, that’s the easiest thing to do: just add some gold to your client’s portfolio – without getting into all the complexity of a currency or anything else,” he said. “It’s that simple. That’s as far as they need to go. Everything else gets very complicated.”

Barisheff was reacting to recent commentary that gold’s place in the investment world was being eclipsed by Bitcoin. He noted that for something to be an effective currency, it needs to store wealth as well as be a medium of exchange – and Bitcoin doesn’t accomplish that.

“You can’t conceive of doing a long-term bond with Bitcoin because the volatility in the fluctuation is so huge,” he said, “and then there’s really nothing backing it.”

While Bitcoin’s value is increasing, Barisheff attributed that to the hype surrounding it rather than any solid justification for it.

The Bank of International Settlements, which he noted sets the rules for all central and commercial banks, has authorized gold as a zero-risk monetary asset equal to U.S Treasuries.

“They didn’t say that about Bitcoin,” he added.

China and Russia increasing their holdings of Gold

The other thing that Barisheff said to watch for in the world of gold is the fact that the world’s central banks hold about 30,000 tonnes of gold – and the central banks of China and Russia, as well as other countries, are increasing their holdings. China has said it has 1,600 tonnes of gold, but he said some estimate that its sovereign wealth fund, which doesn’t have to report its gold holdings, may have 5,000 to 6,000 tonnes of gold.

“They will move it to the central bank when they feel they’ve bought enough gold,” he said. “Their officials have publicly stated that their objective is to have more gold than the U.S. and the U.S. has 8,000 tones, so China’s goal is to have 10,000 tonnes. So, they’re not going to announce that until they’ve finished buying the gold because, when they do, the price will go ballistic, and it’s in China’s best interest for the price to stay down for the time-being.”

Once that happens, he noted that there will be questions about where they got that gold. Continue Reading…