Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Q&A with MyOwnAdvisor’s Mark Seed on speculating near Retirement

Mark Seed’s MyOwnAdvisor website has just published a Q&A with Yours Truly. The Hub often republishes Mark’s blogs here (with his permission of course) and this Q&A covers topics like dividend investing, asset allocation ETFs, hybrid strategies using both and even crypocurrencies.

You can find the original blog by clicking here, or you can read the republished version below:
MyOwnAdvisor’s Mark Seed

Mark Seed: “Fun money” is an apt term for monies you can afford to lose. I mean, nobody wants to lose money on purpose of course but there is always an undeniable trade-off when it comes to investing.

Risk and return and related.

Higher risks can signal a higher potential return. Higher risks taken can also signal flat-out failure.

I was curious to hear about how some retirees or semi-retirees invest and keep speculation in their portfolio.

So, I reached out to author, blogger and columnist Jon Chevreau for his thoughts including how much he speculates in his own portfolio, at age 67.

Jon has already contributed to My Own Advisor a few times.

Jon, welcome back to the site to discuss this interesting topic!

Jon Chevreau: Glad to be back Mark.

Mark: In our last post Jon, we talked about low-cost ETF investing, investing in stocks and more in your Victory Lap Retirement book.  

Let’s back up a bit…

What should Canadians consider before Do-It-Yourself (DIY) investing? I mean, it’s not for everyone including those in retirement right?
Hub CFO Jonathan Chevreau

Jon: No, DIY investing is probably not for everyone: some need good advice and like most things in life, you get what you pay for.

If you need a full-service advisor or a fee-based advisor that can add value not just on investments but on tax strategies, estate planning, retirement income, insurance and the like, then paying on the order of 1% a year of assets is not unreasonable. On the other hand, with interest rates so low, the more you can save on the fixed-income portion of a portfolio the better. That applies doubly to retirees, who should have a good percentage of their investments in fixed-income (say 40 to 60% depending on objectives and risk tolerance.) I often tell retired readers that if all they use is a discount brokerage in order to hold a Vanguard or iShares asset allocation ETF, that can be a good compromise: you get the equivalent of near professional stock-picking prowess via indexing, asset allocation and rebalancing all for a very good price; and you could then hire a fee-only financial planner for specific guidance outside that pure investing realm.

(Mark: you can find many of those asset allocation all-in-one ETFs here.)

Mark: Seems wise Jon.

So, given some aspiring retirees might not want to invest entirely alone, what good options might be available to help them out (beyond blogs like yours and mine of course)!? Ha!

Jon: I often direct new or aspiring retirees who are worried about the shift from wealth accumulation to generating regular retirement income to the books by good Canadian authors like Moshe Milevsky, Daryl Diamond and Fred Vettese. Sites like yours and mine probably have reviewed these. There are also several retirement planning software packages that are worth considering; ViviPlan, Cascades and Retirement Navigator, to name three I once reviewed in a Globe & Mail article.

(Mark: you can find many references to those authors and their books below.)

Daryl Diamond – Your Retirement Income Blueprint

Fred Vettese – Retirement Income for Life

Fred Vettese – The Essential Retirement Guide

The Long View: Follow the Herd?

By Jeffrey Schulze, CFA, Director, Investment Strategist with ClearBridge Investments, a Specialty Investment Manager of Franklin Templeton

(Sponsor Content)

There are times to follow the herd and there are times to stray away from the pack. Investors must learn this lesson. Sometimes, it can be beneficial to follow a larger group, but there are moments when it can make sense to chart one’s own course. In the early and middle stages of an economic expansion, running with the herd can be a beneficial and safe proposition.

As the U.S. recovery unfolds, some investors may be tempted to break off, worried about the formation of a bubble. Indeed, many investors are concerned that the market may be overheating, based on metrics such as the forward earnings of the S&P 500 Index.

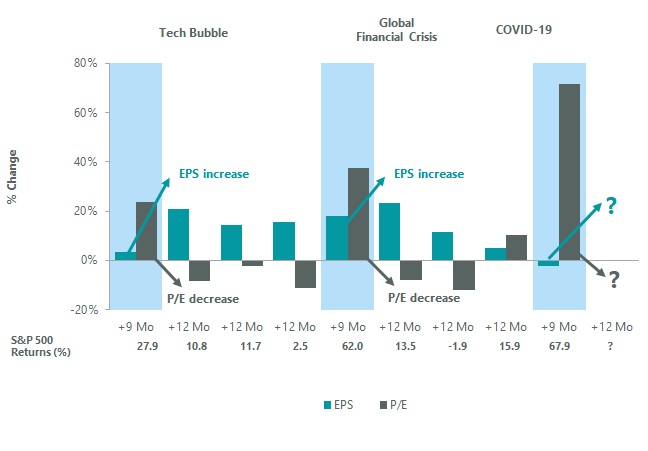
Importantly, an increase in equity multiples is not uncommon during the early stages of an economic expansion. Following recessionary troughs, market returns tend to be driven by price-to-earnings (P/E) multiples during the initial market rally (approximately nine months) as investors anticipate an eventual earnings rebound. As the recovery matures over the subsequent two years, the opposite dynamic occurs, with multiple compressions on the back of stronger earnings growth. Put differently, earnings typically make a significant contribution toward stock returns during this second phase of the rally and declining P/Es become a modest drag on returns (see Exhibit 1 below).

Exhibit 1: Multiples vs. Earnings Data as of Dec. 31, 2020. Source: JP Morgan.

As we move through 2021 and eventually into 2022, we expect this same pattern to unfold; however, multiples may remain elevated.

Higher multiples not uncommon early in Expansion

Valuations are elevated in part because investors correctly sniffed out the budding U.S. economic recovery. Unprecedented stimulus actions (both monetary and fiscal) short-circuited the typical bottoming process, as policymakers formulated a response that rapidly ended the economic crisis and fueled an upturn in financial markets.

ClearBridge Investments has been tracking the scope of this improvement, and we see an overall expansionary green signal since the end of the second quarter of 2020. In our view, it has become clear that a durable U.S. economic and market bottom has formed, with the S&P 500 up 67.9% from the lows and a third-quarter GDP rebound of +33.4%, as of December 2020. Continue Reading…

4 Investing lessons from 2020

Lowrie Financial/Unsplash
By Steve Lowrie, CFA
Special to the Financial Independence Hub
Sometimes, it takes years for key investment lessons to play out to the point we get to say, “See? Told you so.” 
Not so in 2020. Now that this excruciating year is behind us, we can at last appreciate the remarkable crash course it offered in nearly every principle inherent to successful long-term, goal-focused investing.

Where to begin?  Let’s start with the power of planning.

Lesson #1: Planning beats reacting

“Short-term thinking repeated again and again doesn’t lead to long-term thinking.” — Seth Godin

You were there, so you probably remember:  Major global stock markets declined from near all-time highs in mid-February to a low on March 23rd (34% in 33 days).

Few of us saw that coming.  Fewer still might have guessed things would so abruptly reverse, to end 2020 with new highs, well into positive territory.  The U.S. stock market reached new heights last summer, even as the pandemic and its economic devastations raged on.  The Canadian stock market reached a new high recently on January 7, 2021.  Europe and other global stock markets still have a way to go.

The lifetime lesson here, and my key, repeated observation for 2020, is simply this:

The economy can’t be forecast, and the market cannot be timed.  Instead, have a long-term plan and stick to it during dramatic turning points.

Planning as opposed to reacting: this is your and my investment policy in a nutshell, once again demonstrating its enduring value.  Consider these points:

Much ado about nothing:  The velocity and trajectory of the equity market recovery nearly mirrored the violence of the February/March decline.  For those who like to relate letters of the alphabet to economic or market performance charts, the 2020 stock market chart was a pretty pronounced V.

Patience is a virtue:  In volatile markets, it’s tempting to “wait for the pullback” once a market recovery is underway, and/or wait for the economic picture to clear before investing.  Either or both formulas are more likely to underperform compared to simply sticking with your disciplined plan.

Lesson #2:  In investing, “shiny and new” often isn’t

“Modern portfolio management tools give today’s investors control over their own savings, insight into fees and performance, and the luxury of watching their money vanish in real-time when markets plunge.” — Tim Shufelt, The Globe and Mail

The most significant behavioural mistakes investors make (individuals and institutions alike) are panicking in a down market or getting caught up in the allure of a hot market fad.  While both can be severely hazardous to your financial health, my experience is that chasing hot new trends is often the most damaging.

Today’s trends may be new, but the lesson is all too familiar:  A hot new investment trend is wonderful and exciting … until it’s not.

For example, reading today’s financial news, I sometimes wonder if I have been asleep for the past 20 years, like Rip Van Winkle.  Have I just woken up in the tech boom of the late 1990s, when there was more than an average number of hopeful investors trying to score big on the latest tricks of the trade?  If you’ve been around as long as I have, you know that didn’t end well.  A lot of investment portfolios were left woefully deflated once that bubble burst.

From the adventures of day-trading brokerage accounts, to chasing the latest hot IPO, to piling into large technology companies (regardless of their bloated valuations), the similarities between then and now are uncanny.  Today, we could add record-busting bitcoins and blank-check SPACs to the mix.

Then and now, rising markets often tempt the uninitiated to abandon their well-diversified portfolios to chase after the “easy” money.  Then and now, your best move remains the same: stay diversified.  Concentrated bets on hot trends generate wildly unpredictable outcomes, which makes them far closer to being dicey gambles than sturdy investments.

Put another way, if investing were a school, the markets charge a steep tuition to those who don’t heed their history lessons.  I wonder if 2021 could be an expensive year for those chasing the latest hype?

Lesson #3:  Be selective in your media diet

“Wow. If I’d only followed CNBC’s advice, I’d have a million dollars today … provided I started with $100 million dollars. How do they do it!?” — Jon Stewart, The Daily Show

This is a topic for deeper discussion, but it’s worth including in our 2020 reflections:  Investors should remember that popular and social media is much better at hyping extreme news than offering calmer views. Continue Reading…

How the one-ticket Asset Allocation ETFs performed in 2020

easy peasy lemon squeezy - Dictionary.com

By Dale Roberts

Special to the Financial Independence Hub

The one-ticket ETF portfolios are game changers in Canada. You can get a more comprehensive and ‘complete’ portfolio by way of entering one ticker symbol. The fees are incredibly low, in the area of .20%. Yes, that’s about one-tenth of the cost of a traditional mutual fund in Canada. Of course most Canadians should ditch their mutual funds and head on over to their one-ticket ETF of choice. The performance has been very strong. Today we’ll look at the performance of the one-ticket ETFs for 2020.

A one-ticket ETF portfolio will give you access to Canadian, US and International stocks. The stock market risks and volatility are managed by way of bond ETFs. Those bonds (depending on the ETF provider) can be by way of Canadian, US and International bonds.

Remember, stocks are the unruly and unpredictable toddlers, while the bonds are the adult in the room. We might also manage risks by way of cash, gold stocks and gold ETFs that hold physical gold, plus bitcoin and a basket of commodities and currencies. Personally, I am in the camp of managing the risks beyond the bond ETFs. You may choose to top up your one=ticket ETF; that is a personal choice.

One ticket ETFs are managed portfolios

When you invest in a one-ticket ETF you are accessing a managed portfolio. Your job is to add the monies. The ETF provider will buy the stocks and bonds and will rebalance the portfolio on a regular schedule. Easy peasy. That’s why most Canadians will not or do not need an advisor or broker. Especially if you are in the accumulation stage and are simply filling up your RRSP and TFSA accounts.

It’s so simple and effective. When you do need financial planning you can pay as you go by way of a fee for service financial planner. You don’t have to fork over a percentage of your investment wealth every week. In fact, IMHO, most Canadians should not allow perpetual access to their pockets.

The one-ticket ETF providers

The most famous and adopted one-ticket portfolios are offered by Vanguard. The following post will also help you learn how to choose the right ETF portfolio at the right level of risk. Here’s which Vanguard One Ticket ETF should you invest in? The following links are my reviews of each offering.

You might also look at the BMO One Ticket ETFs.

There are also the Horizons One Ticket ETFs and the iShares One Ticket ETFs.

And new to the fold is the TD One Click Portfolios offered by TD Bank. The TD portfolios were launched in August so they will not be part of our full year 2020 evaluation.

If you have any questions about which one ticket might be right for you, please use that contact form. I’m happy to help. No charge.

The one ticket returns for 2020

Even though we experienced the first modern day pandemic, returns for investment assets in 2020 was very strong. Here’s the 2020 year in review. In that post you can see the breakdown of returns for stocks and bonds in 2020. Continue Reading…

Lessons learned in diversification: reducing my Canadian home country bias

By Mark Seed, myownadvisor

Special to the Financial Independence Hub
Many financial advisors, analysts and investing gurus alike argue in favour diversification.

That said, there are some experts who claim owning about 30-40 individual stocks, in various industry sectors, will provide modest diversification to mitigate portfolio risk.

You can find some of those expert opinions on how many stocks are enough in this post.

Dedicated readers of this site will know I’m a fan of portfolio diversification myself, since I adhere to some personal rules of thumb when it comes to my DIY portfolio. Here are some of those rules of thumb:

  • I strive to keep no more than 5% value in any one individual stock.
  • I’m working on increasing my weighting in low-cost ETFs over time, more specifically, owning more of the U.S. market since I’ve had a long-standing bias to Canadian dividend payers in my portfolio.

You can always review some of my current holdings on this standing page here.

Why diversification?

Portfolio diversification aims to lower the volatility of my portfolio because not all asset categories, industries, nor individual stocks will move together perfectly in sync. By owning a large number of equity investments in different industries and companies, and countries, those assets may rise and fall differently; smoothing out the returns of my portfolio as a whole.

“There is a close logical connection between the concept of a safety margin and the principle of diversification.” – Benjamin Graham

As I contemplate semi-retirement in the coming years, this is what I’m considering for cash on hand to support any bearish equity markets or to ride out unfavourable market returns.

Diversification: applying some knowledge and lessons learned

With 2020 in the rear-view mirror, and a trying investing year for many to say the least (!), I decided to make a few portfolio changes so I could embrace diversification more while simplifying my portfolio as those needs for capital preservation draw nearer.

Today’s post outlines some of those changes, by account, and why.

1.)TFSA

I’ve admittedly been wrestling a bit for what to invest in, inside this account for the current 2021 contribution year.

I know I need some more U.S. and international exposure even with the recent comeback in many of my Canadian stocks since the market calamity began in March 2020.

In looking at my sector allocation to the oil and gas industry, I decided to cut complete ties in late-2020 with Inter Pipeline (IPL) after their dividend cut of 72% earlier in the year. You can see some of that dividend news I reported in this previous dividend income update.

I will use that money, along with new TFSA contribution room in 2021 to invest in some all-world ETF XAW amongst other investments.

XAW will provide far less yield inside my TFSA going-forward, which will impact the income generation machine that is my TFSA, but more importantly I think this fund will provide some much needed total return growth from ex-Canada.

XAW iShares December 2020

2.) RRSP

In a taxable account, Canadian dividend paying stocks earn favourable tax treatment thanks to the dividend tax credit. So, I keep those stocks there and see no reason to change that approach. Continue Reading…