Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

New Millennial parents need to prepare for the future

By Donna Johnson

Special to the Financial Independence Hub

One of the most exciting events in most people’s lives is becoming a parent. Those who are currently bringing new kids into the world tend to fall into the Millennial generation, which includes people born between 1981 and 1996. These parents need to be prepared for many things they may not be ready for. Having a home security system is a good idea, but there are also many other financial considerations to take into account.

Kids are expensive

The cost of raising a kid is now estimated to be around US$233,000. That’s just until they are 18. Therefore, Millennial parents can expect to pay more than $12,000 per year for their little bundles of joy. Of course, there are ways to avoid some of these costs, like skipping out on day care costs by having one parent stay home until the child goes to school and buying clothes at thrift stores. Additionally, family members like grandparents might be willing to watch kids for a reduced fee, if they charge anything at all. Regardless, there are costs that come with having a child, and new parents should be prepared for them.

It’s important to get your documents together

Many parents fail to adequately prepare for the future. No one wants to die before their kids reach adulthood. However, there is always that possibility. Therefore, taking out a solid life insurance policy is a good idea. Also, setting up a will that indicates where the kids should go in the event that both parents die or become incapacitated will help ensure that the children stay out of the foster system.

College is coming up

Those who have a child this year will likely have between 18 and 19 years to get ready for college expenses. As of 2018, a year at a public four-year school at the in-state tuition rate averaged US$20,770, while a year at a private school costs just under US$47,000. Continue Reading…

Regulating professional designations for financial planners and advisors

By Darren Coleman

Special to the Financial Independence Hub

If you want to practice law you must graduate from law school. If you want to be a doctor you need a degree in medicine. But what if you want to be a financial advisor who counsels people on how to handle their money and their investments? Until now, pretty well anyone could hang a shingle, but thankfully, those times appear to be changing which is good for the consumer/investor.

The recent 2019 Ontario Budget had a proposal to formally regulate the terms ‘financial adviser’ and ‘financial planner.’

What’s the difference? The adviser helps clients manage their investments, but the planner is a bit different. A financial planner helps you identify and meet your goals. That may be paying for your child’s post-secondary education, paying off your mortgage, or just getting everything in place so you can retire comfortably.

While one needs a professional license to offer advice on the purchase or sale of a stock, insurance policy, or mutual fund, until now pretty well anyone could claim to be a financial planner or wealth management adviser who dishes out general advice for the masses.

Forensic financial planning

But bad or erroneous financial advice from one who isn’t properly qualified can be disastrous for the client/investor, and I have seen it happen all too often. Those of us in the industry call this ‘forensic financial planning’ and the key word there is forensic.

What exactly am I talking about? It might be putting too much weight into something like whole life insurance or high-risk securities. It might be not taking a prudent look at leverage in your investments. Or buying expensive mutual funds that don’t pan out. Continue Reading…

Motley Fool: Getting out of Debt as the first step to achieving Findependence

Those who are regulars to this site will know that Getting out of Debt is the first step towards achieving Findependence, or Financial Independence.

My latest Motley Fool Canada blog has just been published on this topic, which you can read in full by clicking on the highlighted headline: Getting out of Debt to achieve Financial Independence.

As one of the characters in my financial novel, Findependence Day, says to the protagonists: “You can’t climb the tower of Wealth while you’re still mired in the basement of debt.”

As the article reprises, most of us start our financial life cycle with zero or even negative net worth, depending on how much student debt, credit-card debt or later mortgage debt one has accumulated. So if a young person has graduated from college or university and is able to get out of the hole early in their working life, that should be regarded as a huge initial step towards achieving Financial Independence, or Findependence (my contraction).

Keep up the frugal behaviour that got you out of debt

So how do you get out of debt as quickly as possible? The book coins another phrase, guerrilla frugality, which simply means super frugality, whether brown bagging your lunches, taking public transit or any number of other money-saving activities that ensure that you are living within and well below your means. Continue Reading…

If you must speculate in penny stocks, find those with these common characteristics

Penny stocks do sometimes pay off, but there are many pitfalls to avoid. As you’ve heard us say often, a lot of penny stocks are little more than very well executed marketing campaigns.

Take a look at the penny stocks in your portfolio. If you’re a penny stock investor you likely have a number of them. The top 10 penny stocks in your portfolio should follow these guidelines:

Tips for analyzing your top 10 penny stocks

  • Look for strong management: Look for an experienced management team with a proven ability to develop and finance a mine, product or service.
  • Look for a strong balance sheet: High-quality penny stocks should have strong balance sheets with low debt. It’s even better if they have a major financing partner.
  • Look for well-financed companies: To profit in penny stocks, you should look for well-financed companies with no immediate need to sell shares at low prices, since that would dilute existing investors’ interests.
  • Look past the hype: Avoid stocks that are trading at unsustainably high prices as a result of broker hype or investor mania.
  • Look for stocks trading on a well-regulated exchange: We think you should avoid stocks trading “over-the-counter”, where such things as regulatory reporting are lax. Stick to penny stocks trading on regulated exchanges like the Toronto and New York stock exchanges.
  • Look for a results-focused company: Automatically rule out investing in companies that promote themselves too aggressively, or do so misleadingly. Success is more likely if the managers focus on developing a saleable product or service, rather than hyping their story.
  • Look for reasonable share prices: Compare the market caps (the total dollar value of all of a company’s outstanding shares) of the stocks with the estimated value of their assets or future earnings streams. Only a few penny stocks will successfully launch a product with enough success to justify the current share price and avoid collapse.

Your top 10 penny stocks will not be marketing ploys

Many penny stocks are little more than very well executed marketing campaigns. Your top 10 penny stocks won’t fall into this category. Many penny stock promoters will do anything in their power to get their penny stock noticed. These extensive marketing campaigns include emails, TV interviews, podcasts, newsletters and paid sponsorships.

There are also some so-called news sites that will sell sponsorships to penny stock promoters. These are great opportunities for penny stock promoters but bad for investors looking for an unbiased opinion on a stock. Continue Reading…

What’s performing in China?

By WisdomTree ETFs

Special to the Financial Independence Hub

While we remain optimistic that a U.S.–China trade deal will ultimately be reached, investors need greater transparency into what’s performing (or not) in the Chinese equity market. In this article we break down performance by a variety of factors including share class.

In December 2017, WisdomTree partnered with Standard & Poor’s (S&P) to launch the most inclusive Chinese beta product that tracks the S&P China 500 Index.

The WisdomTree ICBCCS S&P China 500 Index ETF, CHNA.B, gives investors seeking a beta exposure to Chinese equities access to the broadest diversity of opportunities in the market by investing in H-shares, B-shares, A-shares and P-chips: shares listed in Hong Kong, Shanghai, Shenzhen, Singapore and New York.

Share Class Attribution

There was a great deal of market interest when MSCI announced they would start to include A-shares in the summer of 2017. Since then, current A-share exposure in the MSCI China Index is just over 2%, despite A-shares representing the largest segment of the Chinese equity market. In our view, the S&P China 500 Index provides a more representative exposure by allocating close to 50% to mainland shares.

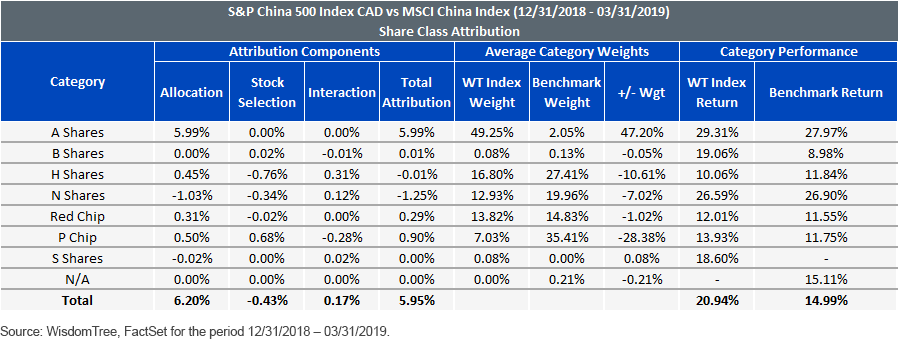
Breaking down exposures by share class, you can see the impact of gaining broad access to the Chinese equity market. In the performance attribution table below, we can see how the S&P China 500 Index has a more balanced exposure across the different share classes than the MSCI China Index, which limits its exposure to class A-shares.

Since the beginning of 2019, the Chinese equity market has experienced strong growth, and the S&P China 500 Index has been in the best position to take advantage of this rebound, having nearly 50% exposure to class A-shares versus the MSCI China Index’s 2.05% exposure. This allocation was the primary driver for the almost 600 basis points (bps) of outperformance that the S&P China 500 Index had in the first quarter of the year.


 Better value and higher quality

Another consequence of having an increased exposure to class A-shares comes in the form of better valuations and increased quality as measured by price-to-earnings (P/E) and return on equity (ROE), respectively. As shown below, we can see that over the past year, the S&P China 500 Index has had higher average exposure to the highest ROE quintile, while also being underweight in the lowest ROE quintile and negative earners. Continue Reading…