Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Retired Money: the glut of books about Trump and prospects for Boomers’ retirements

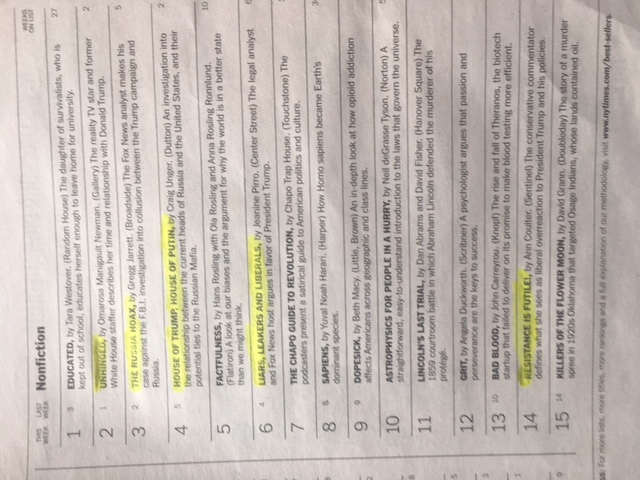
As the yellow highlights show, books about Donald Trump now dominate the New York Times’ non-fiction bestseller lists

As my latest MoneySense Retired Money column recaps in depth, roughly half of the top ten New York Times bestselling non-fiction books are about the Donald Trump presidency. You can access the full column by clicking on the highlighted headline here: How Trump’s policies are affecting my investment choices.

Soon after the 2016 election that brought Trump to power, my financial advisor and I would exchange emails about the latest books: initially biographies and warnings and then in the last year the current glut of books about the actual presidency and the administration.

I’m normally a fan of biographies and love him or hate him, it’s hard to ignore the life of Donald Trump, considering that everything he says or tweets can impact us all. Yes, he may or may not be a threat to the looming Retirement of the baby boom generation of which he is on the leading edge, but his hair-trigger temper and proximity to the nuclear codes gives us something more to fear than merely our financial survival.

Some of the books I mention do give some insights into the implications of this presidency for the global economy and stock markets. Others are mere political diatribes from the left or the right, while still others are more salacious tell-alls. Stormy Daniels, I’m looking at you! (The book is titled Full Disclosure.)

As the column mentions, there are a number of books written by rabid left-wingers who are convinced Trump is a serial liar and a treasonous sellout to Russia president Vladimir Putin, but there are also several written by conservatives and republicans who are more sanguine about it all. In the latter camp I’d include Conrad Black, Ann Coulter and David Frum, plus a few titles from FOX news personalities who are obviously sympathetic with “The President,” as they like to refer to him.

Crazy crazy or Crazy like a fox?  Continue Reading…

Aman Raina’s mid-year 2018 Robo Advisor review

By Aman Raina

Special to the Financial Independence Hub

We’re half-way through the year, so I thought it would be a good time to check back into my ROBO portfolio to see how it’s doing and if there is anything interesting going on.

Three and half years ago I decided to try an experiment and find out for myself. I set up an account with one of the big Robo Adviser firms and invested $5000 of my own money into it. My goal was to go through the process and blog about my experience and more importantly, the results. I said that we need a good five years to really get a handle on how effective these services are compared to traditional wealth management services. Well, we’re coming upon the 4th anniversary of my ROBO account, so let’s take a look at how it’s doing at the mid-year mark.

Performance

Since we last checked in at the 3-year mark in January, the markets had a bit of a throw-up in February and March and so I was curious to see how the ROBO portfolio handled that pressure.

Year to date the portfolio is up 4.2 per cent. Since the January 30th anniversary date the portfolio is up 1.5 per cent. Going back to when setup the portfolio in January of 2015, the portfolio is up 26.6 per cent. The portfolio has increased $92 this year, of which $80 was in dividends.

So far this year ROBO has been rather pedestrian, which it should be. The value proposition of the robo advisor model is steady, consistent implementation of a passive oriented, low cost investment strategy. We haven’t had any adjustments to the weightings of the portfolio unlike last year. There haven’t been any rotation of ETF products.

Despite my concerns about the weighting of the portfolio to Canadian and US equities, the allocation has paid off nicely, especially the US components. In fact all the equity allocations have performed quite well. Fixed income components continue to lag, which makes sense as interest rates continue to track up.

Screen Shot 2018-08-07 at 4.50.10 PM.jpg

Given the strong performance I’m curious to see if the ROBO will actually take some profits and redistribute money towards fixed income or whether they will stay the course. In other words, how “emotional” will my ROBO be? It would be a shame to lose all those gains but I guess that’s what this is all about. That’s me the human being talking and when we let emotions into our thinking we often make the wrong decision. Will the ROBO be different and ignore?

Screen Shot 2018-08-07 at 4.51.03 PM.jpg

Fees

Year to date I paid my ROBO $20.12 in fees, which represents about 0.32% of my assets. If this trend continues (they charge a couple of dollars a month), the total fees I pay to the ROBO will come in around 0.6-0.7%. This does not include the Management Expense Ratio fees that are paid to each ETF itself, which would add additional costs.

The Missing Piece

I’ve commented frequently that one thing we don’t know about ROBO portfolios is how they behave in a significant market downturn. We got a small glimpse in February and March when the markets appeared to be on the verge of a major correction. The Dow Jones Industrials were dropping 1000 points a day at one point. How did the ROBO behave during that period? Continue Reading…

Thinking about taking a flyer on cannabis stocks or blockchain? Follow these guidelines.

By Scott Ronalds

Special to the Financial Independence Hub

 
“I’m thinking of taking some money out of my portfolio with you guys to buy some shares in a blockchain-related start-up. Am I crazy?”


We were asked a question along these lines recently, and I suspect we’ll hear it again, whether it’s blockchain, bitcoin, cannabis, space tourism or whatever new investment opportunity seems exciting. Our answer might surprise you.

No, you’re not crazy. We don’t necessarily think it’s a bad thing to invest a portion of your portfolio in an unconventional, illiquid, or even highly speculative investment. You can learn a lot from it. We do have a few caveats, however. Most importantly, you need to have a high tolerance for risk and should be mentally prepared to lose everything you invest, because you just might. Below are a few other things to consider.

Limit it to 5% of your portfolio

Five per cent isn’t a magic number, but curbing a risky investment to 5% or less of your total portfolio will limit the damage if things go south. True, it will also limit your potential upside, but it’s a prudent trade-off. You don’t want to put your retirement plans and future standard of living at risk by investing too much of your portfolio in an adventure.

Have a plan

This seems obvious, but we find it’s often overlooked. Let’s use bitcoin as an example. Say you invest in the cryptocurrency when its value is $16,000. What will you do if it falls to $8,000? Or if it rises to $24,000? Do you have a floor and ceiling in mind for how much you’d be willing to lose or gain before making a difficult decision with your investment? Bitcoin is a great example of the hyper volatility that comes with speculative investments. You need to be prepared for it, and you need to have a plan.

Consider how it will change the risk profile of your portfolio

If your target breakdown between stocks and bonds is 60/40 and you want to carve off 5% to invest in a start-up, for example, you should be taking the money from the stock portion of your portfolio so that you don’t inadvertently increase your overall level of risk. If you’re venturing into investments that are higher up the risk spectrum, you shouldn’t fund them by cashing in your safer stuff (e.g. cash and bonds).

Further, if you hit the jackpot on a speculative investment, it will comprise a larger portion of your portfolio, which means you should think about reducing the level of risk in the rest of your accounts to keep your overall balance between growth and safety in check. On the other hand, if your investment tanks, your overall portfolio may have less exposure to growth assets than your plan calls for. In this case, it would be appropriate to increase your exposure to stocks. After a bad experience with a high-risk investment, this can be hard to do.

Read the fine print on fees and redemption clauses

If it’s a product or offering that you’re considering, rather than an individual security, be sure to do your homework on fees. Continue Reading…

5 ways Real Estate boosts Financial Independence

By Sia Hasan

Special to the Financial Independence Hub

Gaining financial independence is one of the most difficult propositions. Life is expensive, particularly if you live in a metro area, which is where most of the higher paying jobs are located. As a result, most people save only small amounts of their paychecks or none at all. Clearly, this is not the path to financial independence (aka “Findependence.”).

Thankfully, you don’t have to make a massive salary to become financially independent. There are several methods for building wealth, including starting a business, investing in securities, and investing in real estate. Even if you do the first two already, you need to consider these five ways of increasing your financial independence through real estate.

Real estate investment offers the highest returns for the lowest risk when compared to starting a business or investing in stocks. The reason is that real estate offers five surefire ways to grow your money, known by the acronym IDEAL. By setting a long-term plan to benefit from these five methods of making money in real estate, you are on your way to financial independence.

The IDEAL investment

IDEAL stands for income, depreciation, equity growth, appreciation, and leverage. To succeed in making real estate work as an investment, you need to look beyond your principal residence. Though owning your own home provides appreciation and tax benefits, most people can’t produce income from their principal residence, owners of duplexes and people who rent out spare rooms aside.

1.) Income

When you purchase a rental property, you generate income, provided that you collect enough rent to exceed expenses. With a cash purchase, this is easy. If you finance the purchase, you need to analyze the numbers carefully. Provided you finance the right rental property, you earn a much higher rate of return on the financed property than if you purchased it with cash.

2.) Depreciation

To increase your rental income profits, you need to bone up on the IRS depreciation rules. Because the property is a business investment, you get to deduct all depreciation off of your profits. This saves thousands of dollars in income taxes every year. Continue Reading…

Vanguard: The hidden $1.3 trillion player in active management

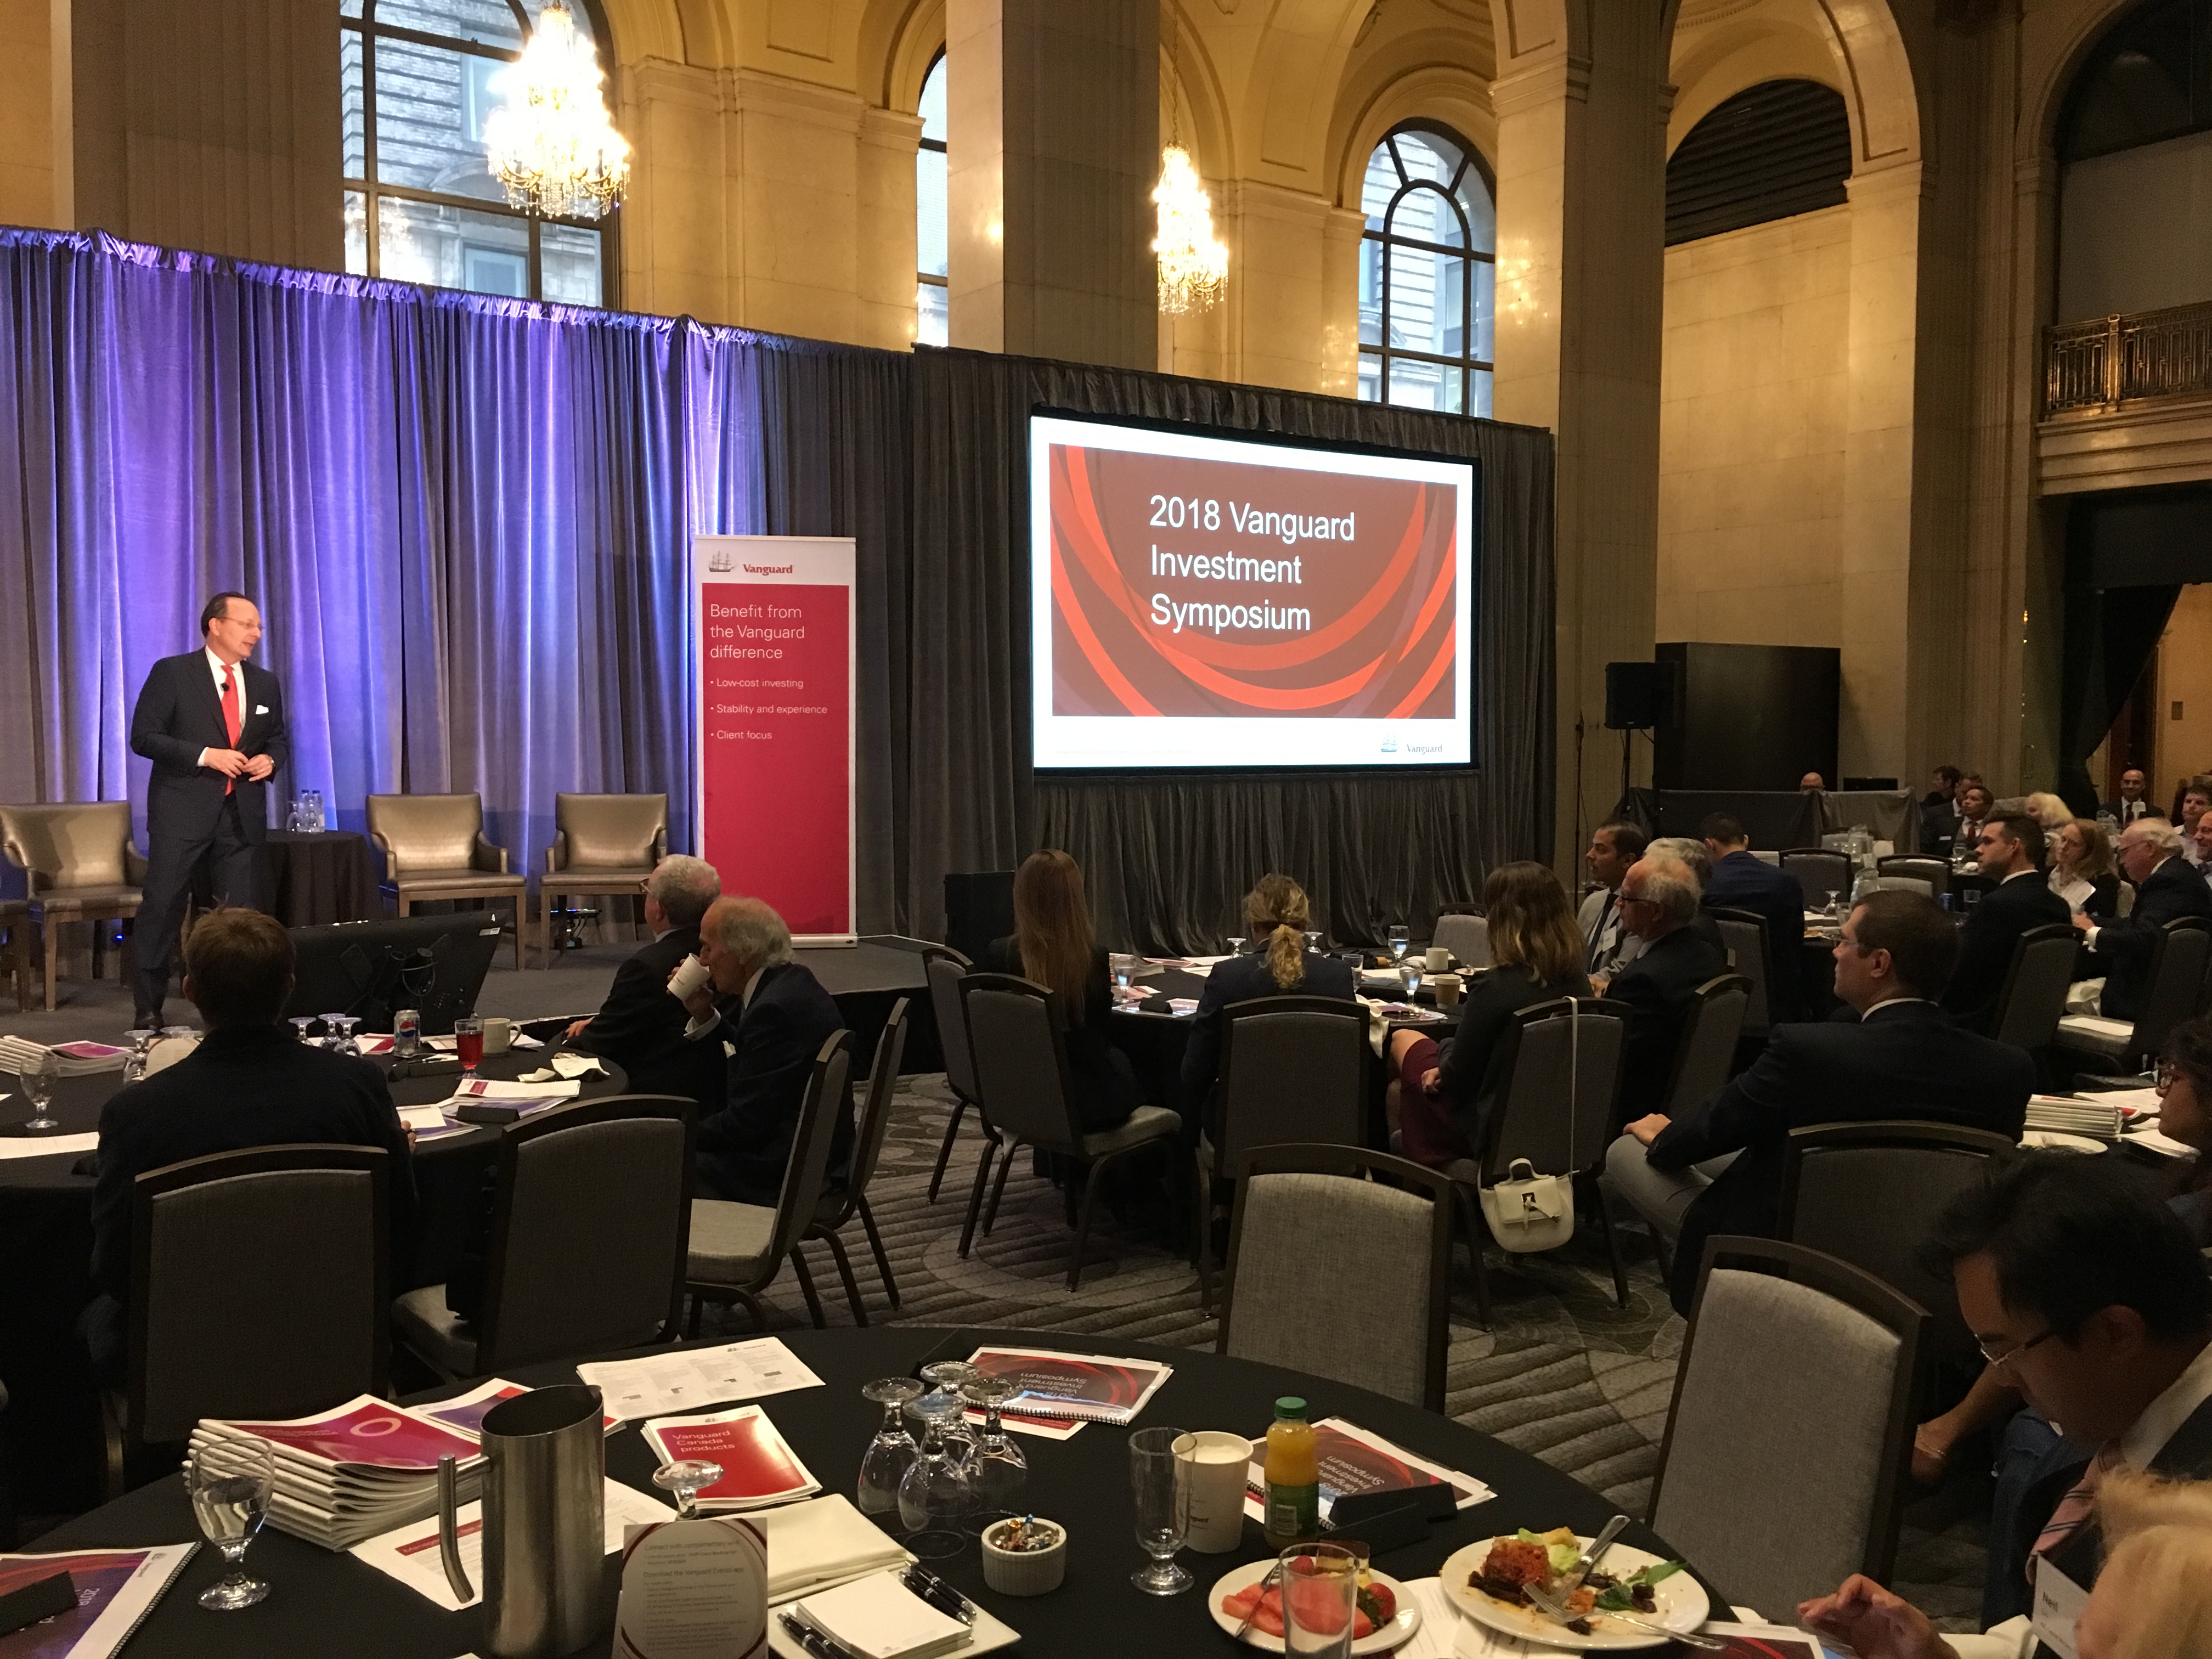
Vanguard’s Daniel Wallick addresses financial advisors at 2018 Vanguard Investment Symposium

While the Vanguard Group is best known for being a pioneer of index mutual funds and exchange-traded funds, it also happens to be one of the world’s largest practitioners of active management. In a presentation Tuesday in Toronto that is taking place across the country, Vanguard executives said the US$5 trillion of money it manages worldwide includes $1.3 trillion in active management.

Vanguard Investment Strategy Group’s Head of Multi-Asset Portfolios, Daniel W. Wallick, presented financial advisors with a framework for constructing portfolios that combine active and passive approaches to investing. The heart of Vanguard’s approach remains broad cap-weighted indexes (or so-called Beta), which is what Vanguard says it means when it uses the term “indexing.”

For many investors, the broad diversification, low costs and tax efficiency of its mainstream index funds and ETFs may suffice.

But, depending on the desired complexity, Vanguard can incorporate “factors” like momentum, value, or liquidity, all factors that have shown a persistency for generating alpha (outperformance) over long periods of time. Beta and Tilts (to for example, overweighting the home country or large market caps) can be combined for the single most important task of Strategic Asset Allocation but overlaying this can be the addition of potential “Alpha” sources like Security Selection and Timing.

“Strategic asset allocation through market-cap-weighted indexes makes for a powerful tool,” Wallick said. And over 10-year periods, asset allocation policy continues to be the biggest source of variations in returns. Asset allocation explains 86% of return variation in 303 Canadian balanced funds tracked by Vanguard, 91.1% of 709 balanced funds in the U.S., 80.5% of 743 balanced funds in the UK and 89.1% of 580 balanced funds in Australia.

Cost trumps talent, patience is crucial

The 3 keys to successful active management = long-term performance

Vanguard sees three keys to successful active management: Cost, Talent and Patience. Wallick described the in-depth process Vanguard uses to select subadvisors for its actively managed funds but hiring talent has to be within strict cost-control parameters.

“Cost is a powerful indicator of future alpha.” But once the talent has been identified and hired, patience is required: Vanguard research over 15 years found that of 2,200 initial funds, 22% survived and outperformed, 24% survived but underperformed, and 54% did not survive. But even among the 22% that survived and performed, 98% of them underperformed in at least four years.

By focusing on both low costs and rigorously overseeing actively managed subadvisors, Vanguard multi manager funds have outperformed their Lipper peer-group averages by various percentages: 78% of them over 1 year, 83% of them over 3 years, 76% of them over 5 years and a whopping 100% over 10 years.

Factor-based funds vs traditional active funds

There is a half-way position between traditional beta-based Style index funds and ETFs and traditional active funds. The former (Beta) provide low cost, low turnover and lower tracking error while traditional active funds provide the opportunity to add alpha, albeit at a higher cost, potentially greater volatility, and less transparency and control. Between these are factor-based funds and ETFs, which provide consistent targeted exposure as well as low cost, but may have higher tracking error and potentially higher turnover. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.