Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Book Review: The Devil’s Financial Dictionary

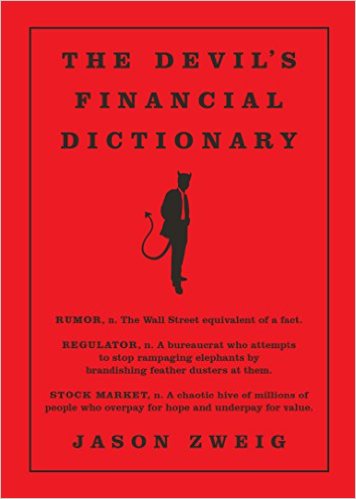
41ixw3fyeLL._SX354_BO1,204,203,200_Like most closed shops, the financial industry features its own specialized vocabulary. As an investor, the key to understanding the financial industry is to understand the buzzwords and special terminology that are as often used to obfuscate concepts as to illuminate investors.

All of which makes Jason Zweig’s The Devil’s Financial Dictionary an invaluable tool for serious investors. Zweig is of course the Wall Street Journal’s eminent personal finance columnist. The book, published late in 2015, was inspired by Ambrose Bierce’s classic book, The Devil’s Dictionary.

As Zweig writes in his book’s introduction, “If investors are to be partners instead of pigeons, they must master the many ways in which Wall Street uses language to conceal rather than reveal information. Every profession is a conspiracy against the laity, and every profession’s jargon is meant to confuse and exclude those who aren’t part of the guild.”

If you learn nothing else, consider the following pithy observation by Zweig:

The denser the jargon, and the more polysyllabic the terminology, the more likely someone is hiding something from you.

Arranged alphabetically, as one would expect of a dictionary, this is a book you can peruse randomly; in fact, I’d suggest that approach. Without further ado, here are some sample definitions that got my attention and/or made me chuckle: as you’ll see, many of the definitions are simultaneously amusing and yet useful in penetrating the true meaning of many financial terms. They’re also quite cynical, which is half the fun: I’m sure Zweig had a blast writing them up in the first place.

ANALYST, n. A purported expert on a company who in theory estimates its value by breaking it down into its constituent parts but in practice functions as a salesperson and cheerleader.

CREDIT CARD, n. A thin slab of plastic that enables a person to feel pleasure today by incurring pain tomorrow. Continue Reading…

Starting is Hard, Doing it is Easy: 9 ideas to get you started

The secret of getting ahead is getting started - famous American writer Mark Twain quote interpretation with pink notes on vintage carton board

Starting is hard.  Doing is easy.  Even when it comes to the hardest things, starting is harder than actually doing the hard thing.

For the most important things, or the things where we have the most to gain, starting is the hardest thing.

If things are really easy to do, if they’re important, starting is hard.

Why is that?  Maybe we’re afraid of the consequences if we fail.  Maybe we’re afraid of the consequences if we succeed. After all, what would we fret about all day if all our “to do’s” were done?  Who knows where or why but as the proverb goes, “there is an enemy within.”

And if this enemy shows itself in areas which are important or where we have the most to gain or lose – it probably manifests itself as often as ever when it comes to the following:

  • relationships
  • personal fulfillment
  • exercise
  • diet
  • finances

These are all big areas where we could stand to gain a lot if we get things right!  And the longer we delay starting, the more it stresses us out – we sit in a paralytic trance, waiting for inspiration to hit us and it just never happens.

Perhaps breaking larger goals into smaller, more tangible steps might help, or at least it might trick you into doing something that sends you in the direction of progress.  While we don’t proffer advice in many of the above areas and in fact struggle as much as anyone,  we think the following smaller steps might help get you on the road to sorting out your financial house.  We’re sure there are more but here’s 9 to start:

9 smaller ideas to move you towards getting your finances in order

1.) Make sure you have an up-to-date Will, Power of Attorney designation and Health Directive.

2.) If you have people that depend on you, get insurance to make sure they’re taken care of if something happens to you – term life insurance is relatively cheap and pricing is fairly standardized.

3.) Pledge allegiance to the following mantra: “By far the most important thing I can do to ensure long term financial success is to live within my means.”

4.) If you have children, be sure to open a Registered Education Savings Plan (RESP) and invest enough to get the maximum Canadian Education Savings Grant (CESG)….free money from the government (need we say more?).

5.) If your company has a retirement savings program with matching contributions, it’s usually a good idea to contribute enough to get the maximum match.

6. ) Open a Tax Free Savings Account (TFSA).

7.) If you have investments, grab a pen and piece of paper and write down what you’re invested in, why and how much you pay annually in fees.

8.) If you can’t do number 7 without turning on your computer, educate yourself – we recommend the following Sensible & Concise Investment Books

9.) If these steps still seem overwhelming, find someone qualified and independent to help you.

Postscript –  if you’re interested in digging a little further into the enemy within, please read Steven Pressfield’s The War of Art.  He calls the enemy Resistance and it’s very real and very, very scary…..

graham-bodelGraham Bodel is the founder and director of a new fee-only financial planning and portfolio management firm based in Vancouver, BC., Chalten Fee-Only Advisors Ltd. This blog is republished with permission: the original ran late September here. 


How to invest in gold, including in your RRSP

Closeup silver ingots and golden bullions in bank vault. Finance 3d illustrationAt TSI Network, we recommend that if you are looking at investing in gold that you stay away from buying gold bullion, coins (unless you collect them as a hobby) or certificates representing an interest in bullion.

That’s because gold investing in bullion does not generate income. Instead, bullion and coins come with a continuing cash drain for management, insurance, storage and so on.

Instead, that’s why we recommend that you limit your gold investing to gold-mining stocks. Unlike bullion, gold-mining stocks at least have the potential to generate income.

However, if you do want to hold physical gold or silver in an RRSP, here’s how to do it:

More than a decade ago, the 2005 Canadian federal budget made investment-grade gold and silver coins, as well as gold or silver bullion bars, eligible to be held in an RRSP.

To be considered investment grade, gold coins must be at least 99.5% pure, and silver coins must be at least 99.9% pure. As well, only legal-tender coins produced by the Royal Canadian Mint are RRSP-eligible.

Bullion bars are also eligible for RRSP gold investing, as long as they are produced by a metal refinery that is accredited by the London Bullion Market Association. Accredited metal refineries include the Royal Canadian Mint and Johnson Matthey.

However, to hold the coins or bullion bars in your RRSP you need to find a third-party custodian of your coins or bars who will verify that you indeed hold the amount of bullion claimed, and report that to the Canada Revenue Agency on your behalf.

Investing in gold: a practical way to hold gold bars and coins in your RRSP

Continue Reading…

Robb Engen’s 4 biggest Investing Mistakes

Learn from your mistakes - motivational words on a slate blackboard against red barn woodI was 19 years old when I first started investing. I diligently set aside money every paycheque, starting with $50 every two weeks and eventually increasing that to $200 per month, to save for retirement inside my RRSP. Sounds like I was off to a great start, right? Wrong!


Even though my intentions were in the right place, my first attempt at investing was a complete disaster. Here’s why: I didn’t have a plan

It’s good practice to save a portion of your income for the future, even at a young age. The problem for me was that I was still in school and didn’t have a plan – I had no clue what I was saving for.

I had read The Wealthy Barber and The Millionaire Next Door and so I knew the earlier I started putting away money for retirement, the longer I’d have compound interest working on my side, and the bigger my nest egg would be.

Unfortunately, I was saving for retirement at the expense of any other short-term goals, like paying off my student loans, buying a used car, or saving for a down payment on a house.

I didn’t have any short-term savings

Speaking of RRSPs, what was a 19-year-old kid doing opening up an RRSP when he’s only making $15,000 per year?

There were no real tax advantages for me to save within an RRSP when I was in such a low tax bracket. I’m sure I blew my tax refunds anyway, so what was the point?

Granted, the tax free savings account hadn’t been introduced yet, but I would have been better off using a high interest savings account for my savings rather than putting money in my RRSP.

I didn’t have a clue about fees and tracking performance

Like a typical young investor I used mutual funds to build my investment portfolio. I was encouraged by a bank advisor to select global equity mutual funds because, as I was told, they would deliver the highest returns over the long term.

What the bank advisor didn’t tell me was that the management expense ratio (MER) on some of those mutual funds can be 2.5 per cent or more, and high fees will have a negative impact on your investment returns over the long run.

Bank advisors also don’t tell you which benchmark these funds are supposed to track (and attempt to beat) so when you get your statements in the mail it’s impossible to determine how well your investments are doing compared to the rest of the market.

I drained my RRSP early

I didn’t have a good handle on my finances in my 20s and often resorted to using credit cards to get by. Without a proper budget in place, and no short-term savings to fall back on in case of emergency, I had no choice but to raid my RRSPs to pay off my credit-card debt and get my finances back on track.

Taking money out of my RRSP early meant paying taxes up front. Withdrawals up to $5,000 are subject to 10 per cent withholding tax, while taking between $5,000 and $15,000 will cost you 20 per cent, and withdrawals over $15,000 will cost you 30 per cent.

Your financial institution withholds tax on the money you take out and pays it directly to the government. So when I took out $10,000 from my RRSP, the bank withheld $2,000 and I was left with $8,000. In addition to the withholding tax, I also had to report the full $10,000 withdrawal as taxable income that year.

While I can’t argue with my reasons for selling, my dumb decisions beforehand cost me a lot of money and left me starting over from scratch.

Final thoughts

We all make investing mistakes – some bigger than others. If I had to do things over again today I would have done the following:

  1. Create a budget – A budget is the foundation for responsible money management. Had I used a budget and tracked my expenses properly from an early age I would have lived within my means and kept my spending under control.
  2. Open a tax free savings account – Yes, the TFSA wasn’t around back then but for today’s youth it makes much more sense to save inside your TFSA instead of your RRSP like I did. You can put up to $5,500 per year inside your TFSA and withdraw the money tax free. You contribute with after-tax dollars, so you won’t get a tax refund, but you’ll likely be in a low tax bracket anyway, so contributing to an RRSP won’t give you much of a refund either.
  3. Make a financial plan – We all have financial goals and even at a young age I should have identified some short-and-long term priorities to save toward. I’d take a three-pronged approach where I’d use a high interest savings account to fund my short term goals, my TFSA to fund mid-to-long term goals, and eventually open an RRSP to save for retirement. No doubt I’d be much further ahead today if I took this approach earlier in life.
  4. Use index funds or ETFs – Now that I understand how destructive fees can be to your portfolio, I’d look into building up my investments using low cost index funds or ETFs. The advantage to using index funds is that you can make regular contributions at no cost while achieving the same returns as the market, minus a small management. Some brokers also offer free commissions when you purchase ETFs.

Did you make similar mistakes when you first started investing? How did you overcome them?

 RobbEngenIn addition to running the Boomer & Echo website, Robb Engen is a fee-only financial planner. This article originally ran on his site on August 7th and is republished here with his permission.


Do you live next door to a Millionaire? Or is it you?

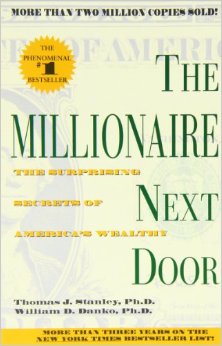
51es1dfibl-_sy344_bo1204203200_Two decades ago, Thomas Stanley and William Danko set out to interview wealthy people for their best-selling book The Millionaire Next Door. They started out in the affluent neighbourhoods on streets dotted with extravagant homes with luxury vehicles parked out front and in-ground swimming pools in the backyards.

They were shocked to find out that the people living in these homes were not wealthy at all. Many of these upscale homes had huge mortgages. The luxury cars were leased and, while the occupants had high salaries, they had very little net worth. They only seemed wealthy.

Instead, they found millionaires in modest homes in reasonably priced neighbourhoods, working and living next door to people who have a fraction of their wealth. They were living well below their means and not calling attention to themselves. They didn’t have the big-spending lifestyle most of us associate with rich people.

To be clear, for this purpose a wealthy, or high net worth, individual is described as someone who has at least $1 million in investable assets that is not inherited. These assets do not include their home or cottage.

Also not included are the ultra-high-net-worth, super wealthy individuals with a bankroll of more than $100 million who actually represent only a small minority of Canadians.

The road to riches

What can the average Canadian learn from the habits of the wealthy? Danko and Stanley found these factors common to wealthy people:

1.) They live well below their means

When I first read this book years ago I thought – what a bunch of cheapskates with their Timex watches, $50 suits, and 10-year-old Ford trucks! If I had that kind of money, I’d at least upgrade a little. I’ve known a few people who had a large amount of assets and spent hardly anything, ultimately leaving their wealth to relatives, and often distant ones at that.

I understand now that the millionaires mentioned do tend to be frugal, but they enjoy luxuries that are meaningful to them, and only once they are well on the road to security and financial freedom.

2.) They chose the right occupation

Many are small business owners or entrepreneurs, but you don’t have to own a business to get into this circle. Often they are hard-working, well-educated, middle-to-high income earners.

I’m not suggesting you choose a career primarily for the high salary. But, it’s obvious that if a person is educated and trained in some sort of profession, they will do much better than say, a cashier or shipper-receiver.

3.) They have a good marriage

Dual incomes enable couples to get ahead financially much more quickly. However, even more important are spouses who have similar values and goals and are willing to resolve any differences and work together in building their wealth.

There is no quicker way to lose half the assets of a household than to go through a divorce.

4.) They are skillful in targeting opportunities

People shouldn’t worry about the doom and gloom reporting on the news and things they can’t control. Instead, have a long-term view of investing and don’t let emotions sway your decisions. Have cash available to buy when markets are down and to take advantage of any bargain opportunities.

Start saving and investing in your early years to take advantage of compounding and reinvested dividends.

Pay less for purchases by shopping for bargains and learn to negotiate. Avoid high-interest credit-card debt. Use smart tax reduction strategies.

Allocate your time, energy, and money efficiently, in ways conducive to building your wealth.

5.) Their adult children are economically self-sufficient

Children are taught money management at an early age and encouraged to enrol in secondary education. As adults, they don’t ask their parents for money or bail-outs or help with the bills.

Final thoughts

Danko claims that it’s really about buckling down and living on less:

“How in the world can you be an investor and let compounding work for you if you are not a saver? And how can you be a saver if you are in debt? Many people who are strapped with debt are looking for a magic bullet, but continue the free-spending ways they have become accustomed to. Live on 80% of what you make, and save and invest 20%. Let the time value of money work for you.” 

Calculate how much money you will earn over your working life. Most people will earn well over a million dollars in their lifetime, but very few will become millionaires.

Accumulating wealth takes discipline and hard work.

We all want a sense of long-term security and peace of mind as well as the comfortable lifestyle that wealth provides.

Saving diligently, being frugal, setting aside a portion of your income for the future and investing wisely are the strategies to becoming the millionaire next door.

Do you think you live next door to a millionaire? Or, is it you?

MarieEngenMarie Engen is the “Boomer” half of Boomer & Echo. In addition to being co-author of the website, Marie is a fee-only financial planner based in Kelowna, B.C. This article originally ran at the Boomer & Echo site on September 20, 2016 and is republished here with permission.

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.