Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

What Is the Income Factor in U.S. Equities?

blog-see-more-dividendschris_gannatti_crop-bwBy Christopher Gannatti, Associate Director of Research, WisdomTree

Special to the Financial Independence Hub

The factor discussion is gaining popularity in the world of smart beta indexing. Size, value, momentum, minimum volatility, quality—these are all factors in the current discussion, and for the initiated they are becoming part of the common index lexicon.

But are investors really looking for these specific factors by name? We explore how these factors relate to real-world investment goals.

Translating Factors into Investment Goals

Some commonly referenced investment goals are:

• Keeping principal stable for unexpected expenses and emergencies

• Generating a certain average annual return to meet future goals in retirement

• Drawing income in order to meet planned expenses

We focus on income, as WisdomTree was the first to create a suite of U.S. equity Indexes weighted by cash dividends.

Defining the Income Factor

Continue Reading…

Dogs of the Dow is themed ETF investing but flawed

Dog Breed Small Brabant AccountantInner Circle members often ask us about themed ETF investing strategies, and most of the time, we tell them we do not recommend investing in themes.

For example, some ETFs out there are based on the so-called “Dogs of the Dow” stocks. Essentially, the “Dogs of the Dow” ETF is based on a collection of the lowest-priced, highest dividend yielding stocks that trade on the Dow Jones Industrial Average and are updated yearly.

Rising interest rates will work against Dogs of the Dow ETF investing approach
The ALPS Sector Dividend Dogs ETF (symbol SDOG on New York; www. alpssectordividenddogs.com), is an example of an ETF that applies the “Dogs of the Dow” theory on a sector-by-sector basis using the stocks in the S&P 500.

As we mentioned above, the Dogs of the Dow approach involves buying the lowest-priced, highest-yielding stocks in the Dow Jones Industrial Average. At the end of each year, you pick the 10 stocks from the 30-stock Dow with the highest dividend yields. You then invest an equal dollar amount in each, hold them for one year and repeat these steps annually.

The ALPS Sector Dividend Dogs ETF picks five stocks from each of the 10 sectors as defined by the S&P 500 index—consumer discretionary, consumer staples, energy, financials, healthcare, industrials, information technology, materials, telecommunication services and utilities. The ETF picks the stocks with the highest dividend yields. Each holding is then equally weighted so that every company has a similar influence on the ETF’s total return. The end result is a portfolio of 50 large-cap stocks.

The Dogs of the Dow strategy worked well in the 1990s because interest rates were going down. This tended to raise all stock prices. But high-yielding stocks were affected more than most, because they attracted former bond investors who were switching into stocks.
Interest rates are now likely to remain steady, or they could creep upward. So we see little appeal in a Dogs of the Dow approach.

For that matter, we see little appeal in following any formulaic approach to investing. The one basic rule about things like this is that if it sounds too good to be true, then it isn’t true.

The ALPS Sector Dividend Dogs ETF holds a number of stocks we recommend in Wall Street Stock Forecaster (including McDonald’s, Kraft Foods Group, Wells Fargo & Co., Baxter International, Pfizer, General Electric and Intel). It also holds a lot of stocks we don’t recommend. But, more to the point, we don’t recommend using a Dogs of the Dow approach to picking stocks or ETF investing.

There is no “philosopher’s stone”

Continue Reading…

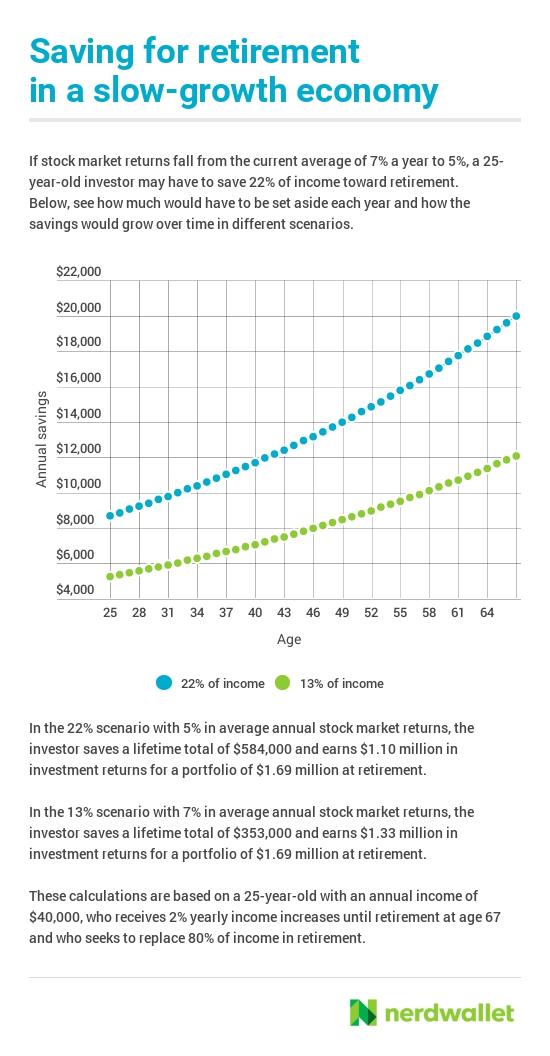
Millennials may need to save 22% of income just to retire by 70

chart-1As my Financial Post blog today recaps, a new study being released today by the San Francisco-based personal finance site NerdWallet warns that just to retire by age 70, today’s millennials would have to save a whopping 22% of yearly income. Click on the highlighted text for the FP piece: Millennials may have less time on their side, U.S. retirement study shows.

The adjacent chart shows the math and how much millennials would need to save every year, depending on whether the stock market generates its historic 7% annual rate or the more pessimistic projections of 5%.

“Era of supernormal returns is over”

Continue Reading…

Capital gains tax is one of the lowest you’ll ever pay

Hand with pen pointing to GAIN word on the paper - financial and investment conceptsThere are three forms of Investment Income in Canada: Interest, Dividends and Capital Gains. Each Is taxed differently. Here’s a reminder of how smart investors use their knowledge to taxation rates, especially tax on Capital Gains, to protect their returns.

With stocks, you only pay capital gains tax when you sell or “realize” the increase in the value of the stock over and above what you paid for it. (Although mutual funds generally pass on their realized capital gains each year.)

Several years ago, the Canadian government cut the capital gains inclusion rate (the percentage of gains you need to “take into income”) from 75% to 50%. For example, if an investor purchases stock for $1,000 and then sells that stock for $2,000, then they have a $1,000 capital gain. Investors pay Canadian capital gains tax on 50% of the capital gain amount. This means that if you earn $1,000 in capital gains, and you are in the highest tax bracket in, say, Ontario (49.53%), you will pay $247.65 in Canadian capital gains tax on the $1,000 in gains.

The other forms of investment income are interest and dividends. Interest income is 100% taxable in Canada, while dividend income is eligible for a dividend tax credit in Canada. In the 49.53% tax bracket, you’ll pay $495.30 in taxes on $1,000 in interest income, and you will pay $295.20 on $1,000 in dividend income.

Three capital-gains strategies

Continue Reading…

Four psychological biases investors must understand

Concept of stress with gear in the head of a businessmanIn our last post we highlighted that behaviour might just be the biggest source of trouble for investors.  People just aren’t psychologically wired to make investment decisions that are good for them and often do things that are potentially harmful.

Our brains have evolved to create protection mechanisms that in many instances are helpful – just not when it comes to investing!  The subconscious creates short cuts designed to save us time when making decisions and to protect us from pain, both emotional and physical: basically, these short cuts help us perform better in “fight or flight” situations.  While many of these biases and their implications for investors have been documented by the likes of Daniel Kahneman, Amos Tversky and others, we think the following four stand out:

1.) Familiarity Bias

We tend to stick with what we know, whether that is products we buy, places we frequent or stocks in which we invest.  Presumably this heuristic evolved over time to help us make quicker decisions and keep us safe but when it comes to investing it can have the opposite effect.  For example Canadian investors tend to overweight their portfolios towards Canadian stocks, a common phenomenon globally but Canadians are among the most extreme examples of what’s known as “home bias.”

While Canadian investors might feel more comfortable owning the shares of companies they read about in the news most often and that are closely tied to our own economy, from an investment perspective they are taking on unnecessary risk by being overly exposed to specific companies in the oil, mining and financial sectors.  Canadians would be better off from a risk and reward perspective if they were to diversify more outside of Canada.

2.) Recency Bias

We tend to remember things better that happened more recently than we do things that occurred further back in time.  If you look at expert forecasts from Wall Street analysts going back in time, they tend to forecast very high returns just at or following market peaks (like the internet bubble) and low returns following market bottoms (like during the 2008/2009 financial crisis): clearly not very helpful and if so-called experts fall victim to the same biases, what chance do the rest of us have?  Markets are volatile and move in cycles:  anchoring on recent trends or sentiment might lead us to make decisions that result in the opposite of what’s good for us.

3.) Overconfidence Bias

Daniel Kahneman believes this to be the most dangerous of all behavioural biases and the most difficult to overcome.  Just like driving ability, people tend to believe they have a better than average ability to pick outperforming investments or investment managers.  This bias leads people to ignore overwhelmingly convincing evidence, often at their peril.

For example, despite the fact that data shows that paying high fees for active investment management leads to lower returns on average and greater uncertainty of outcomes, people continue to try to beat the market or find winning investment managers.  (Full disclosure, Chalten Fee-Only Advisors espouses an evidence-based low-cost, largely passive investment philosophy!).

4.) Herding

It’s a lot more painful to be wrong on your own than be wrong when everyone’s wrong.  Surely the herding mentality stems from some innate desire to feel included, to avoid being exposed whether right or wrong.  The result of herding in the investment world is that once trends develop there tends to be a “bandwagon effect” that becomes difficult for many investors to resist.  “Fear of missing out” or FOMO as it’s popularly acronym-ed these days can drive individuals to make irrational investment decisions they might normally avoid if deciding independently.

The net effect of the above is that people make investment decisions that are harmful.  Often the result is that investors buy into euphoric market peaks and sell out at the bottom of market panics.  It is no surprise that studies show that investment returns earned by individual investors are not only lower than market index returns but lower than those of the mutual funds in which they invest: investors just get in and out at the wrong time.

And if it’s not enough of a struggle that we have these psychological biases to battle against, most of the financial media and investment industry use communication and advertising practices that are specifically designed to exploit all of our psychological pitfalls!

How can you win?  To begin with, develop a investment plan that fits in with your overall financial plan.  Define parameters that address your ability, need and willingness to take risk and then use your plan as an anchor (in this case an anchoring bias is OK!) to keep you on track and avoid being swayed by both external noise and internal psychological biases.
graham-bodelGraham Bodel is the founder and director of a new fee-only financial planning and portfolio management firm based in Vancouver, BC., Chalten Fee-Only Advisors Ltd. This blog is republished with permission: the original ran on September 14th on Bodel’s blog here.