Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

When to buy an ETF for maximum return


To determine when to buy an ETF, some investors use technical analysis and other tools. But you need to dig deeper.
ETF-25Y-medallion-ROUND-ENInvestors often wonder: what is a good entry point when purchasing a stock or an ETF?

The first question before asking when to buy an ETF is whether an exchange traded fund investment is right for your portfolio. An ETF investment is one of the most popular and most benign investing innovations of our time. ETF investments are a little like conventional mutual funds, but with two key differences.

First, ETF investments trade on a stock exchange throughout the day, much like ordinary stocks. So you can buy them through a broker whenever the stock market is open, and generally you pay the same commission rate that you pay to buy stocks. In contrast, you can only buy most conventional mutual funds at the end of the day. What’s more, commissions vary widely, depending on negotiations with your broker or fund dealer.

Second, the MER (Management Expense Ratio) is generally much lower on ETFs than on conventional mutual funds. That’s because most ETFs take a much simpler approach to investing. Instead of actively managing clients’ investments, ETF providers invest so as to mirror the holdings and performance of a particular stock-market index.

ETFs practice this “passive” fund management, in contrast to the “active” management that conventional mutual funds provide at much higher costs. Traditional ETFs stick with this passive management—they follow the lead of the sponsor of the index (for example, Standard & Poors). Sponsors of stock indexes do from time to time change the stocks that make up the index, but generally only when the market weighting of stocks change. They don’t attempt to pick and choose which stocks they think have the best prospects.

This traditional, passive style also keeps turnover very low, and that in turn keeps trading costs for your ETF investment down.

When to buy an ETF

Continue Reading…

8 Habits that will kill your Retirement Dreams

 8 habits that are killing your retirement dreamsA growing number of Canadians plan on working longer because they haven’t saved enough for retirement. We see it at a macro-level; Canadian households owe a record $1.65 in debt for every dollar in disposable income; meanwhile, the personal savings rate in Canada stands at a paltry 3.9 per cent.

There are plenty of reasons why we owe too much and save too little. The economy stinks, people get laid off, and salary increases are few and far between.

That said, we’re often our own worst enemy when it comes to taking care of our finances. Here are eight habits that are killing your retirement dreams:

1. You don’t watch your spending

It’s tough to stop a money leak when you have no clue where your money is going. Small daily purchases do add up (latte factor, anyone?), but these spending categories can bust your budget much faster – big grocery bills, dining out too frequently, filling your closet full of new clothes, one-click online shopping, and expensive hobbies, to name a few.

The solution: Write down everything you spend for three months. I guarantee you’ll have an ‘a-ha’ moment at best, and at worst discover something useful about your spending habits that you’d be willing to change.

The goal of course is to spend less than you earn. It’s one of the major tenets of personal finance.

2. You want the newest ‘everything’

Fashion and décor trends change, technology constantly evolves. Staying ahead of the curve means shelling out big bucks for the latest and greatest products. The problem is your capacity to buy new things will never keep up with the pace of innovation and change. It’s an endless cycle.

The solution: Wait. Early adopters pay a hefty premium to be first. Look no further than televisions, where the latest innovations can initially go for between $5,000 and $10,000 – 10 times what they’ll cost in a year or two.

The bigger issue is the psychological need to always have the latest gadget or be at the cutting edge. Ask yourself whom are you trying to impress.

3. You have the constant need to upgrade

Fewer than half of all iPhone users hang onto their smartphones until they stop working or become obsolete. Most want to upgrade as soon as their provider allows it – usually every two years. A small percentage upgrades every year whenever a new model is released.

While spending a few hundred dollars on a new phone every other year might not hinder your retirement plans, it could be a symptom of a bigger problem. The constant need to upgrade your technology, your car, and even your home can be a big drain on your finances.

Nearly three in 10 homeowners get the urge to move every five years, and 14 per cent actually want to move every year.

The solution: The same buy-and-hold approach that you take with your investments can also apply to your major purchases. The Globe and Mail’s Rob Carrick suggests a 10-year rule for homeowners to combat the odds of a housing crash and to save on transaction fees.

Extending the life of your purchases, even by a year or two, can free up cash to pay down debt or save for retirement.

4. You treat credit-card debt as a fact of life instead of a hair-on-fire emergency

Life can be expensive but there is no excuse for using credit cards to support your lifestyle. Despite what your friends or coworkers might say, credit card debt is not a fact of life. This may come as a shock but you can save up in advance for a vacation or new kitchen appliances.

The solution: Nothing can ruin your finances quite like high-interest credit card debt compounding every month. Stop everything and assess your income and expenses. Cut discretionary spending, put any savings plans on hold, and throw every cent towards your highest interest debt until it’s gone.

Related: Debt avalanche vs. debt snowball (or when math trumps behaviour)

5. You use low interest rates as an excuse to finance depreciating assets

Borrowing to invest can make sense when your expected return is greater than the cost of the loan. But it’s a mistake to take out a loan -– even at today’s low interest rates –- to finance consumables and depreciating assets.

Common reasons to take on debt today include weddings, vacations, furniture, and vehicles. A home equity line of credit can provide flexibility to pay for big purchases, but the habit of borrowing from your future self to pay for today’s consumption is a major retirement killer.

The solution: You need a financial plan. Most of us can wrap our heads around saving for retirement but we struggle prioritizing and funding our short-term goals. A good plan helps you identify what’s important in both the immediate and distant future and steers your savings towards the appropriate goals.

Put a dollar amount and a timeline on your goals and start saving. Trust me, it’ll feel great to pay for your next vacation or big-ticket purchase in cash.

6. You’re too complacent

Doing nothing is often the best course of action when it comes to a volatile stock market, but financial inertia can cost you in other ways. Some of us can’t find $50 a month to save for retirement, yet we pay $15 a month or more in bank fees, won’t drive half a block to save money on gas or groceries, and don’t bother returning items of clothing that don’t fit.

Worse examples of complacency are when people don’t take advantage of their employer matching RRSP program, don’t shop around for a better rate on their mortgage, or continue to pay high fees on their investments.

The solution: Sometimes we need a wake-up call or major life event before we start taking our finances seriously. Once you see how much complacency is costing you that’s usually enough to motivate you into taking action.

7. You put off retirement savings until a later that never comes

“We’ll start saving for retirement once we’ve paid off our credit cards-line of credit-mortgage.”

There are so many priorities competing for your hard-earned dollars. Sadly, retirement savings is easy to put on the back-burner while you deal with more immediate needs like a big mortgage, two car payments, a new trailer, and some expensive seasonal hobbies. Retirement is far away and you can save later, right?

If you’re already killing your retirement dreams with the previous six habits then later might never come.

The solution: There’s a reason why ‘pay yourself first’ is such a powerful savings tool. Money is automatically whisked out of your account before you get a chance to spend it. Like some kind of magic you barely notice and are somehow able to live on the rest.

8. You keep your long-term savings in cash

You actually managed to get some money from your chequing account into your RRSP or TFSA. The problem now is that it’s sitting in cash – you actually need to take the next step and buy an investment such as a mutual fund, ETF, stock, bond, or GIC.

This is a uniquely Canadian problem as investors have nearly $75 billion in excess cash sitting in their portfolios.

The solution: Whether it’s risk-aversion or analysis paralysis, you need to take action and get your retirement savings working for you. Speak with a financial planner who can help you make sense of your investment choices and risk tolerance. Read books, blogs, and magazines to try and educate yourself about investing and how to build a portfolio.

A good place to start is with the model portfolios listed on the Canadian Couch Potato blog.

Final thoughts

It’s true, we do plenty to sabotage our own retirement dreams. The good news is that it’s never too late to take control of your finances and start saving for retirement. Start by fixing bad habits that have a negative effect on your finances.

Save enough and you can retire on your terms.

 RobbEngenIn addition to running the Boomer & Echo website, Robb Engen is a fee-only financial planner. This article originally ran on his site on August 28th  and is republished here with his permission.

Investing isn’t about hitting home runs but staying out of trouble

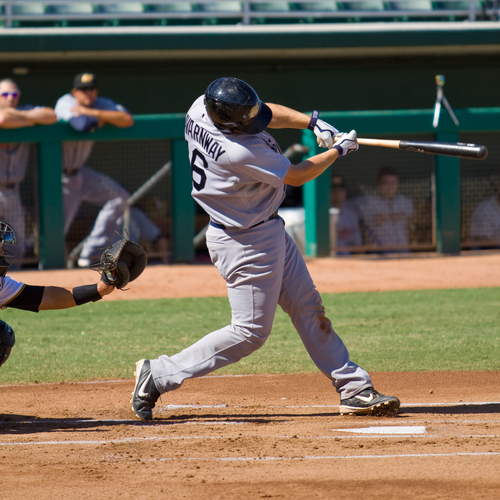
MESA, AZ - OCTOBER 18: Ryan Lavarnway, a top prospect for the Boston Red Sox, hits for the Peoria Javelinas in an Arizona Fall League game Oct. 18, 2010 at HoHoKam Stadium. Lavarnway went 1-for-4.People are often surprised when we say that successful investing does not mean you have to “beat the market.” Instead, successful investing is simply that which allows you to meet your financial goals.

Trying to hit “home runs” by picking hot stocks before they jump or timing market swings are activities more aligned with speculating than investing and may actually decrease your chances of meeting your goals. Ultimately, success is less about swinging for the fences and more about staying out of trouble.

Unfortunately, trouble can manifest itself in many ways. The most common troubles that can trip investors up are:

High and hidden fees

Canadian mutual funds have among the highest fees in the world – high fees detract from investment performance and over a long period of time can significantly erode your savings nest egg.

Lack of diversification

Continue Reading…

Can “RoboTrader” take the emotion out of picking individual stocks?

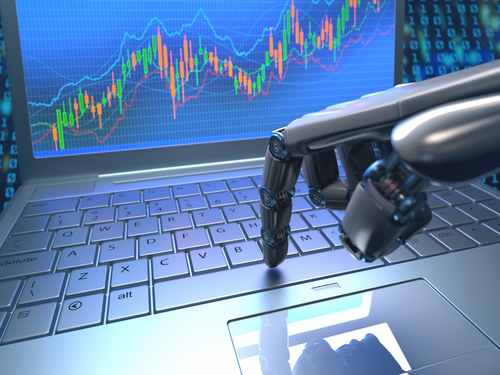
Robot hand, ordering on a laptop keyboard, an exchange trade. Robot trading system is a computer trading program that automatically submits trades to an exchange without any human interventions. Depth of field with focus on finger.My latest Financial Post blog looks at a new term, RoboTrader. You can find it by clicking on the highlighted text: VectorVest-Questrade partnership brings unemotional ‘robo’ to retail investing.

As I point out in the piece, the better-known term robo-advisor is well entrenched as a shorthand description of automated online investment services, and generally refers to semi-automated portfolio management systems built on low-cost exchange-traded funds or ETFs.

The idea is to build low-cost well-diversified portfolios and benefit by gradual dollar-cost-averaging of the underlying ETFs, as well as regular rebalancing. This takes a lot of the emotion out of building and monitoring an ETF portfolio.

By contrast, RoboTrader attempts to do a similar thing in the realm of individual stock-picking. RoboTrader revolves around 23,000 individual stocks rated every day by  VectorVest Inc. of Charlotte, N.C., which provides investors with both tools to help them with both technical and fundamental analysis of stocks, as well as ETFs. VectorVest has announced RoboTrader as part of a partnership with Questrade Inc., the Toronto-based discount brokerage service.

VectorVest describes RoboTrader as a “powerful new trading tool that solves the biggest problem for many traders: executing a trading plan without letting emotions cloud judgement.” RoboTrader lets clients implement a trading plan that requires only client confirmation for fast, accurate execution, with results monitored in real time.

VectorVest says RoboTrader leverages the intelligence of its fundamental and technical analysis, making it easier to manage portfolios. RoboTrader sends instant alerts to investors’ VectorVest accounts, phone and email, “letting traders know exactly which trades to make, when to make them and in what order quantity.”

Similar deals with US-based TradeKing and TradeStation

Continue Reading…

Why you should forget about buying Canadian marijuana stocks


Canadian marijuana stocks offer some speculative appeal — but here’s why we think you should avoid them

AMSTERDAM - AUGUST 26: Candy and cookies with marijuana for sale in the coffeeshop on August 26, 2014 in Amsterdam.

As you probably know, several U.S. states have decriminalized or legalized marijuana use and have begun authorizing legal production and sale of the plant. In Canada, marijuana has been legal for medical use for some time, and we are occasionally asked about Canadian marijuana stocks.

This change in the law is bound to lead to a shift in current and future marijuana production, from the underground economy to the legal economy, where it can be regulated, taxed and invested in. Tax revenues are already starting to roll in, but we haven’t found any Canadian marijuana stocks worthy of investment. So far, most of what we’ve seen are stock promotions.

We advise staying out of stock promotions of Canadian marijuana stocks businesses or anything else. They attract the wrong kind of people. Stock promotion is a take-the-money-and-run type of business. Most successful entrepreneurs value their reputations, and want to build a profitable, sustainable business that can pay off for investors. So they generally go into some other line of work, and stay out of stock promotion.

These days, it’s faster and easier than ever to launch a stock promotion, thanks to the Internet. One recent “penny pot” stock scam almost seems like an MBA-style case study on how to launch one of these frauds online.

We won’t name the penny stock company that is the subject of the promotion campaign, since it claims it’s not involved in the fraud. Let’s just refer to it as “Pot o’ Gold,” or POG for short.

The POG spam emails we’ve seen use the following techniques:

Continue Reading…