I know it’s tough to save money. It’s even more difficult to up the ante and increase your savings year-after-year. But saving is necessary to meet both our short- and-long-term financial goals. Without any savings, and living paycheque-to-paycheque every month, you’ll either work until you die or else retire in extreme poverty.
So what will it take for you to save more this year? Some people start off small, saving two or three per cent of their salary, and that’s fine – every little bit counts. But many of us short-change our retirement by not finding ways to increase that amount every year. Here are four easy ways to save more in 2015:
Click above link for the full article. I’ve reproduced the ten headings below, after which I make a few additional observations, based on my own transition in 2014 from employment (21 consecutive years of it.)
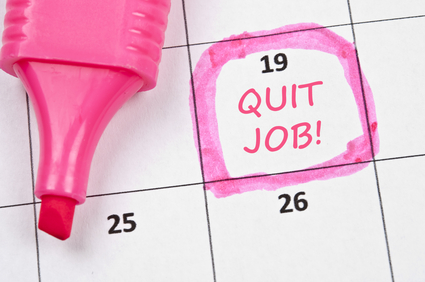
The bottom line is this is what Findependence (Financial Independence) is all about, and the raison d’être of this website. In fact, the cover of the US edition of my book on Financial Independence is very similar to the illustration to the left, except that the calendar date circled is Findependence Day.
As I note below, there may also be good reasons NOT to quit your job in 2015 but instead in 2016 or later. I wrote the original Findependence Day in 2008 but the day didn’t actually arrive until 2014, so you could say it was six years in the making. Sometimes, big life events need to be planned out that far ahead.
In any case, here are the ten reasons for quitting sooner than later: Continue Reading…
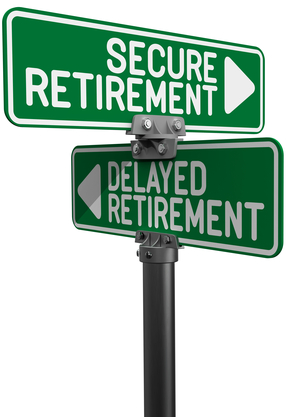
The headline on today’s blog so perfectly sums up the subtle difference between “Retirement” and “Financial Independence” (aka “Findependence”) that I felt compelled to devote a whole blog to the idea.
Ardrey, who is with T.E. Wealth, seems to view the topic of Financial Independence just as we do on these sites, even down to the basic principle repeated often in the book to which our sister site (FindependenceDay.com) is devoted. In Findependence Day, one of the two financial planning characters, Theo, tells his young clients more than once: “The foundation of Financial Independence is a paid-for home.”
Here’s what Ardrey tells clients just starting down the road to Financial Independence:
I’m often asked how one can get to this wonderful nirvana known as financial independence. The first step is to pay off your home. By having a debt-free residence, you have eliminated what is most people’s largest single expense. Without this hanging over your head, you have freed up significant cash-flow.
Even Ardrey mistook FI for Retirement early on
Ardrey and I have followed each other on Twitter for some time. Ardrey posts as @MattArdreyCFP. But it was only recently, in response to something on one of these sites, that Ardrey casually dropped the fact that he’s been preaching Financial Independence (as opposed to traditional Retirement) to his clients since he entered the financial planning business at the turn of the century.
He noted that the financial planning software used at the financial firm where he got his start did not have a retirement calculator. Instead it had an an analysis tool on “Financial Independence Needs.” At the time, being new to the business, Ardrey thought it was just a fancy way of referring to retirement planning but as the years progressed, “I would soon discover that financial independence was something else entirely.”
So, to return to the headline today, what exactly IS the difference? Here’s the key passage:
Retirement, by definition, is the cessation of work with the intent of not returning. Financial independence, on the other hand, is having sufficient financial assets to have the choice about whether or not you continue to work. So, one can be retired and not financially independent or vice versa.
It’s all about Freedom of Choice
This is of course pretty much what I’ve been saying, or at least the characters in the book and ebooks: “When you’re financially independent, you work because you want to, not because you have to (financially speaking).” And that’s exactly what Aubrey tell his clients:
The main differentiator is freedom of choice. If you are not financially independent, you have no choice but to continue working if you don’t want to alter other aspects of your life. Once you are financially independent, you can choose if you want to continue to work in the same capacity – or at all. This freedom to choose is empowering and it’s what I encourage all of my clients to work towards.
Some real examples
So far in this blog, I’ve reiterated Ardrey’s views. I want to close with some examples closer to home. I can think of a few friends or family members who are “retired, but not financially independent.” One couple in particular comes to mind: they do not work and live entirely on government largesse: some combination of CPP, OAS and GIS. Once upon a time they owned a home , a cottage and a car but today they rent a small apartment above a store. They have time freedom, yes, but no financial freedom. They depend entirely on the one source of income from the Government and if that dried up, I don’t know what they would do. Even with it, they are severely constrained in what they can do. So they are indeed “retired, but not financially independent.”
For the opposite situation, I need look only in the mirror. My wife and I choose to continue to work, and keep deferring future income sources that could be taken now if we chose: employer pensions, CPP, drawdowns from registered and non-registered investments, etc. Our home was paid for early in the 1990s, our cars are paid for and we have no debt. We are in fact financially independent but NOT retired, paradoxical as that may seem.
And finally …
Today is Boxing Day and I will probably CHOOSE not to do much more work on these sites, or for paying clients, until the New Year begins, apart from a few pre-arranged pieces and guest blogs. I wish all readers a very Happy New Year. See you on the other side!
Via BC-based certified financial planner Fred Kirby comes this Marketwatch piece on ten things retirees won’t tell you. Several of the points may resonate with readers of this site, although of course our distinction between the terms “Retirement” and “Financial Independence” may make some of the points moot. We may riff off this list at some point in the future, but in the meantime also check Monday’s guest blog by Matthew Erdrey on a similar theme, and watch for a similar post on Boxing Day.
Below is Marketwatch‘s list of ten; click through on the above link for the complete piece:
1.) We’re broke.
2.) Retirement is more stressful than it looks.
3.) We spend too much time by ourselves.
4.) We’re in denial about our health problems …
5.) … and our health costs are huge.
6.) We’re coming after your jobs.
7.) We still get frisky.
8.) We’re planning to move in with you.
9.) That big Hawaii trip? It’s more like a pipe dream.
The guest blog below by certified financial planner Matthew Ardrey followed a discussion we had on social media about the distinction between traditional retirement and financial independence. Matthew, who is with T. E. Wealth, uses a definition of financial independence that is virtually identical to the one we use on this site, right down to having a paid-for home. We especially like this line: “One can be retired and not financially independent or vice versa.” Over to Matt:
Matthew Ardrey, T.E. Wealth
By Matthew Ardrey, CFP
Special to the Financial Independence Hub
I was first introduced to the concept of retirement as a young boy, when my grandfather retired from the TTC on his 65th birthday. I understood that he no longer worked, and that this is what you do when you reach 65. From the eyes of a child, it seemed like a far away notion.
It wasn’t until 2000, when I started working in the financial services industry, that I was properly introduced to the concept of financial independence as it differs from retirement. The proprietary financial planning software we used at my workplace did not have a retirement calculator. Instead, it had a “Financial Independence Needs” analysis tool. As I was young and green, I saw it as a fancy way of saying retirement planner. Through the benefit of experience, I would soon discover that financial independence was something else entirely.
Retirement vs. Financial Independence
Retirement, by definition, is the cessation of work with the intent of not returning. Financial independence, on the other hand, is having sufficient financial assets to have the choice about whether or not you continue to work. So, one can be retired and not financially independent or vice versa.
When I explain financial independence to my clients, I let them know that the main differentiator is freedom of choice. If you are not financially independent, you have no choice but to continue working if you don’t want to alter other aspects of your life. Once you are financially independent, you can choose if you want to continue to work in the same capacity – or at all. This freedom to choose is empowering and it’s what I encourage all of my clients to work towards.
How to Get There
I’m often asked how one can get to this wonderful nirvana known as financial independence. The first step is to pay off your home. By having a debt-free residence, you have eliminated what is most people’s largest single expense. Without this hanging over your head, you have freed up significant cash-flow.
The second step is budgeting – both before and after you have reached financial independence. Before, determine what you will need to save to reach your goals, and pay yourself first. After, understand what and how you spend to determine if you have accumulated sufficient assets in the “before” stage.
Know Your Asset Returns
Understand the return on the assets that are funding your freedom. Which assets in your portfolio are generating income or appreciating, and at what rate are they growing? How are taxes affecting these returns? These are questions to which you should know the answer, as small changes in that rate compounded over a long period of time can have a significant effect.
Costs matter, period. Focus on the cost/benefit relationship of your investment structures. Benchmark both what you make and what you pay to make it. If you find that the costs are inordinate while the performance is average or worse yet, lackluster, take steps to fix the cost/benefit. Even better yet, get the jump on “CRM2” by asking your advisor to fully delineate all costs pertaining to your investments and what services are offered in exchange for these costs.
As I guide my clients towards their future goals, I find the word “retirement” is used less and less in my lexicon. When my clients leave the workforce, the pursuits they undertake tend to be much different from my grandfather’s, who retired 35 years ago. What they are pursuing is the freedom to make their life whatever they want it to be.
Matthew Ardrey is a Certified Financial Planner with T. E. Wealth. He can be reached at its Toronto offices here. He is also on Twitter as @MattArdreyCFP.
 Posted By