This audio clip is from the More Than Money radio show from Calgary, recorded shortly after the Hub launched. The focus was on a MoneySense blog I’d written after the question “Will your retirement date be a surprise?” was posed in a Sun Life poll. But we also touch on the longevity theme that is the focus of the Longevity & Aging section here at the Hub. There’s also an update on the launch of the Hub and the recent e-books.
When you get to the show’s link, just press the small “Play” icon next to my name, or indeed the same icon next to any of the other guests’ names there.
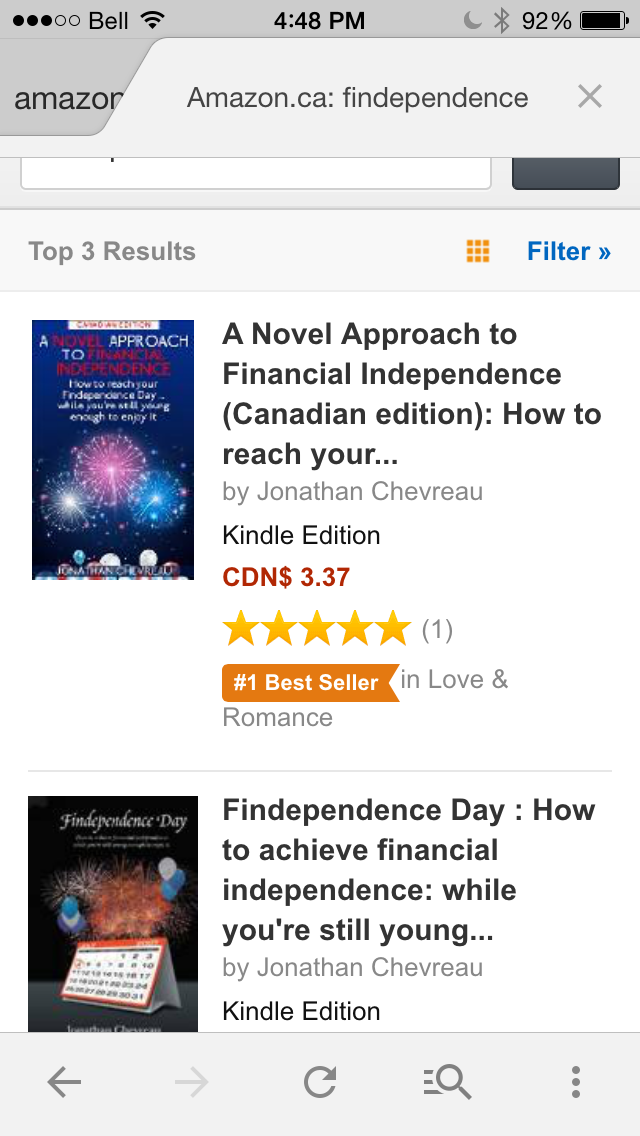
A Novel Approach to Financial Independence is one of the bestselling e-books in Amazon.ca’s Love & Romance category this weekend, as you can see in the screen shot to the right. Here’s the link to Amazon’s listing.
Love & Romance? What about personal finance? Well, I’ve always described the original Findependence Dayas a financial love story so it’s not as out of the box as it may seem at first blush. Click on the red link in the title above to find out more about the Romance plot that’s at the heart of the original novel.
The full book features a couple, Jamie and Sheena, who are 28 at the start and follows their ups and downs as a couple over 22 subsequent years. It takes a “life cycle” approach to personal finance and centers around Jamie’s declaration that he will become financially independent (“findependent”) by the time he turns 50. There are numerous setbacks along the way, including business failure and betrayal, separation, children and more.
As CTV Senior Financial Commentator Patricia Lovett-Reid says in the foreword to both the original book and the e-book, money troubles are often the cause of marital disharmony. You can read that foreword, by the way, for free because it’s near the start and Amazon lets you “look inside.”
e-book is a “Coles Note” synopsis of the novel
I liken the e-book to a “Cole’s Notes” synopsis of the original book, summarizing the plot but focusing more on the content on financial independence. It’s short (15,000 words) but costs only C$3.37. Amazon lets you designate purchases as gifts and with Christmas just around the corner, you have to admit it’s pretty cost-effective! Especially if you can change a young person’s life for the better, as we say in the ad below (also shown on the front page of Findependence.TV).
There is also a U.S. edition of the full novel available here, as well as a U.S. edition of the e-book, which you can find on the main page of this site.
The System Worked was published earlier this year, bearing the tantalizing subtitle: How the World Stopped another Great Depression. I ordered it from the library after reading a New York Times review on it and several related books.
I have to admit it took some time to wade through it, in part because I returned my copy to avoid lugging physical books through Turkey, where I spent three weeks in October. But on my return, I borrowed it again and finished the book.
The author, Daniel Drezner, is a senior fellow at the Brookings Institution and a professor of International Politics at Tufts University. I found his prose somewhat dull but the ideas underlying them are worth mining.
U.S., Europe and China pulled together
In book publishing it’s probably harder to sell an upbeat title than a pessimistic one. (When was the last time a newspaper led off an issue with “No planes fell from the sky yesterday?”) And The System Worked is decidedly upbeat about how governments around the world coordinated their response to what could have been a global economic and stock-market disaster in 2008 and its aftermath. It credits this coordination primarily to the United States first and foremost, ably assisted by the Eurozone and China. Japan, it seems, slipped into a second tier throughout this struggle to avert what otherwise was shaping up to be another Great Depression.
Daniel Drezner (Oxford Press)
The early chapters recap the common perception (a false one in the author’s view) that the system did NOT in fact work: this after Drezner lays out his case for why it did indeed work out splendidly. Those who claim otherwise cite specific trouble spots like the escalation of Europe’s sovereign debt crisis or the failure of climate-change negotiations. Here is a typical upbeat Drezner quotation:
“Even though the initial drop in output and trade levels was more acute in 2008 than in 1929, by any measure the global economy has rebounded more robustly over the past five years than it did during the Depression … The liberal economic order proved to be more robust than expected.”
Certainly, Drezner’s optimism has been justified through late November of 2014. Friday’s twin events of China cutting its interest rates and the ECB’s stimulus talks suggests that the world’s central banks continue to fight the good fight against deflation, depression and other horrors.
But can the system work for more than these first five years?
All of which makes the book’s final chapter all the more tantalizing. Entitled “Where do we go from here?” Drezner repeats his main theme when he says that on policy grounds, both TARP (Troubled Asset Relief Program) and the related Federal Reserve programs were “huge successes” in how they “greatly eased the credit crunch faced by the banks.” This despite the fact TARP “has remained political poison.”
Well, the skeptical reader may say at this point, we may have survived the first five years but can we keep it up? Drezner concedes “there are valid reasons to be concerned about the future.” There is still much fragility in the global economy and the Eurozone “has still not found a viable way to fix the internal imbalances between Germany and southern Europe.” A global recession is quite possible, he admits, and “there are a lot of ways in which things could go wrong” but “given what has happened since 2008, it is safer to conclude that they won’t.”
A big part of his faith is based on what he terms “the enduring strengths of the United States.” These include healthy demographics, geographical security, a dynamic pop culture and excellence in higher education and innovation. Add to that lower oil costs and the fact he believes America will be “the world’s leading oil producer some time before 2020.”
Meanwhile its chief rival, China, is reforming its development model so that “its domestic economy more closely resembles that of the United States.”
Drezner closes with the admission that in the world of international affairs punditry, pessimism sells. Nevertheless, he closes with this:
“Pessimism has spread just as widely as financial contagion did in 2008. It is wrong and needs to be corrected … Going forward, a healthy dollop of optimism is in order.”
As anyone who believes in “Findependence” well knows, it’s best to torpedo debt as early in life as possible. This starts with student loans and high-interest credit-card debt and proceeds to home mortgages. As the book says more than once, “The foundation of financial independence is a paid-for home.”
This also applies to financing automobiles. I only ever bought a brand-new car once and that was a Dodge Shadow in 1989, purchased for around $10,000 or $12,000. If it was financed it wasn’t for long. Since then, it’s been slightly used cars bought with cash, including my current car, a late-model hybrid Camry that had only 12,000 clicks on it when I liquidated some tech stocks in the spring.
So I can’t speak with authority about the high cost of financing cars. But for those that want to go that route, read a piece in the Financial Post this weekend: The Great Car Bubble. In it, the Post’s resident cheapskate Garry Marr (@dustywallet on Twitter) and Barbara Schecter investigate the explosion in car loans and describe how car loans can soon end up ballooning into debt that exceeds the car’s value. The temptation is for consumers to be enticed by low interest rates and then compound the error by stretching out loan timelines. For example, it cites a case of paying out a total of $55,000 on a car that would cost just $35,000 if purchased for cash outright.
I don’t know about you but I could think of better uses for the $20,000.
Property Pals
While perusing the Post, hop on over to this Personal Finance piece by Melissa Leong about couples going halves to get a foot on the housing ladder. This is called “co-ownership.” You can also see Melissa Leong on video over at the Video Hub at sister site Findependence.TV.
2.) Longer life expectancy (See also the Hub’s Longevity & Aging section for more on this trend.) Go the full link at USA Today to click on its Life Expectancy Calculator.
3.) Social Security (or for Canadians, CPP/OAS/GIS. More on that in Monday’s Financial Post)
4.) Choices in the financial marketplace: stocks, bonds, insurance, annuities, mutual funds and ETFs, real estate, commodities, hedge funds


 Posted By