All posts by Jonathan Chevreau

Weekly wrap: Taxes on stock options, young Americans give up on getting rich, Tangerine credit card

jackmintz
Jack Mintz (YouTube.com)

Politics and stock options converged this week, as the Financial Post reported in a story headlined Liberal and NDP plans to boost tax on stock options could cost taxpayers money, study finds. The study, written by University of Calgary fellow and occasional FP columnist Jack Mintz, says the proposals from the two Opposition parties would cost Ottawa money. That’s because corporations would insist that fully taxed stock compensation should be 100% deductible for the corporation, as is the case for many other countries. The NDP would like to tax stock options at 100% rather than the current 50%, but wouldn’t apply to technology startups.  The Liberals would do the same but apply the tax only to option-based compensation exceeding $100,000.

Young Americans giving up on getting rich

Bloomberg BusinessWeek argues that Young Americans are giving up on getting rich. Why? Their collective rate of employment is weak and if they do have jobs, their incomes are probably depressed; so as a result their retirement nest eggs are “microscopic.” Continue Reading…
Video: Don’t assume investment outperformance is due to manager skill

weber_weber
Professor Martin Weber

FWB TV and Findependence.TV have just posted our second video,  Don’t assume Outperformance is down to Skill. The short (almost 4 minutes) video features Robin Powell interviewing University of Mannheim professor Martin Weber.

Referring to a 2014 academic paper he coauthored, titled Fooled by Randomness: Investor Perception of Fund Manager Skill, Weber explains that retail and even institutional managers often choose money managers on the basis of past investment performance. But he warns investors often confuse skill with luck.

It turns out that it’s very difficult to identify skillful managers in advance. Is it worth it if you can find one? Perhaps if the fees are low enough but generally, Weber says skillful managers turn out to be quite expensive.

Media, Advertising & Industry may have “active” bias

Continue Reading…

BMO will be first big bank to enter robo-adviser space

Profile picture_Mike Katchen
Wealthsimple CEO Michael Katchen: BMO emailed a headsup on its imminent robo adviser service

My latest “Young Money” column in the Financial Post looks at the probable entry of the Bank of Montreal into the domestic robo-adviser (or automated online advice) space.

Click on the headline to get to the full story: Why a Bank of Montreal foray into the robo-adviser market would benefit the industry and consumers.

As I say at the end, I think this is a great development both for consumers and the industry. Robo-advisers are particularly appropriate for young millennials just starting their investing careers but as we wrote last week in the Post, they will also raise the quality of financial advice in general: Robo-advisers will force the financial industry to up its game, survey suggests.

Remember, the big banks validated the mutual fund industry when it entered the no-load mutual fund business in the late 20th century. I expect Royal Bank and TD Bank to be the next big banks to validate this growing new segment of the investment business.

Weekly Wrap: Millennials and saving, optimizing CPP, new Investing videos

image1
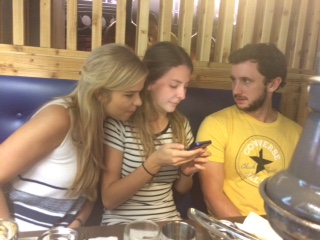
Millennial ESL teachers in Hong Kong: Tess from UK, Helen from Canada, Shane from USA (photo J.Chevreau)

A big furor over whether Millennials should enjoy their 20s and forget about saving money until later in life was tackled by the Motley Fool this week. You can find about ten links to the piece by clicking on my report Thursday for the Financial Post: Don’t bother saving in your 20s? Why millennials shouldn’t waste their gift of time.

The photo here by the way was taken by me recently in Hong Kong, and depicts three millennials who are posted there for a year under contracts to teach English as a Second Language. We won’t use their last names here but from left to right, they are from England, Canada and the United States. I think it’s safe to say that they’re enjoying themselves while they’re in their 20s, which is the point of the article being debated in the above link.

However, they are an example of balance that the Motley Fool’s Morgan Housel refers to in his article. In all cases, these young people are paying their own way: they’ve found a way to be paid while they travel and experience the world, not to mention make friends and lifetime contacts from around the world.  And unlike their parents when they travelled abroad before settling down, these kids have social media to keep them in touch for a lifetime.

Whether they also save a ton while doing so remains to be seen.

Optimizing CPP

Meanwhile, at the other end of the family spectrum, the parents of the millennials seem to have an insatiable interest in maximizing their income in retirement. The CPPOptimizer.com has attracted lots of attention Continue Reading…

What’s next for Fixed Income ETFs?

40ad22c655
iShares’ Warren Collier

Exchange-traded funds (ETFs) have revolutionized the way investors access the stock market. Since the global bond market is much larger than the equity market, it stands to reason that bond ETFs should experience equal popularity with retail and institutional investors.

Friday morning, BlackRock Canada held a briefing session on exactly this topic. Warren Collier, head of iShares Canada, likened the current juncture for bond ETFs to where equity ETFs were when he joined the firm in 1999.

“Before XIU [iShares i60s, one of the largest Canadian equity ETFs] TIPS [Toronto Index Participation Units] had been out for a few years; there was an understanding of what equity ETFs were but it was not very deep. They were used by insttitutional and direct retail investors and advisers were starting to ask questions about them. The conversations today about fixed-income ETFs reminds me of those conversations.”

Still, compared to equity ETF penetration globally, fixed-income ETF market penetration is still relatively low. Equity ETFs make up 3% of the global equity market. Even though the fixed-income market overall is larger, fixed-income ETFs make up only 0.4% of the global fixed-income market, Collier said.

“So globally we’re still very early. There’s an incredible amount of growth left for Fixed Income ETFs globally.”

Generally, iShares executives downplayed the risk to bond investors of interest rates going higher by the end of the year, which seems to be the consensus about when the Fed will finally start hiking rates.  Still, they agreed retail investors increasingly are looking for help in worrying about what fixed-income products are appropriate in this environment.

Moving from Building Blocks to Solutions

Continue Reading…