Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Greed, Fear and Amnesia: The importance of Cycles

Image courtesy Outcome and positivemoney.org.

By Noah Solomon

Special to the Financial Independence Hub

Investment guru Howard Marks is the founder and co-chairman of Oaktree Capital Management, the world’s largest investor in distressed securities. Since launching Oaktree in 1995, his funds have produced long-term annualized returns of 19%. According to Warren Buffett, “When I see memos from Howard Marks in my mail, they’re the first thing I open and read. I always learn something.”

As indicated by the title of his book, The Most Important Thing: Uncommon Sense for the Thoughtful Investor, Marks believes that “the most important thing is being attentive to cycles.” In particular, he discusses the importance of knowing where we stand in various cycles. He contends that most great investors have an exceptional sense for how cycles work and where in the cycle markets stand at any given time. Lastly, Marks insists that investors who disregard cycles are bound to suffer serious consequences.

We live in a World of Relativism

There is a great saying about being chased by a bear, which states “You don’t have to run faster than the bear to get away. You just have to run faster than the guy next to you.”

In the context of investing, outperformance does not necessitate perfection. Success doesn’t come from always being right, but rather from being right more often than others (or from being wrong less often). Whether picking individual stocks or tilting your portfolio more aggressively or defensively, you don’t need to be right 100% of the time; you just need to be right more than others, which by definition leads to outperformance over the long-term. To this end, we have outlined some of our favorite concepts and themes which serve as guideposts for achieving this goal.

It’s all about Fear and Greed: Valuation just goes along for the Ride

The factors that drive bull and bear markets, bubbles and busts are too plentiful to enumerate. The simple fact is that more than any other factor, it is the ups and downs of human psychology that are responsible for changes in the investment environment. Most excesses on the upside and the inevitable reactions to the downside are caused by exaggerated swings in psychology.

Many investors fail to reach appropriate conclusions due to their tendencies to assess the world with emotion rather than objectivity. Sometimes they only pay attention to positive events while ignoring negative ones, and sometimes the opposite is true. It is also common for investors to switch from viewing the very same events in a positive light to a negative one within the span of only a few days (or vice-versa). Perhaps most importantly, their perceptions are rarely balanced.

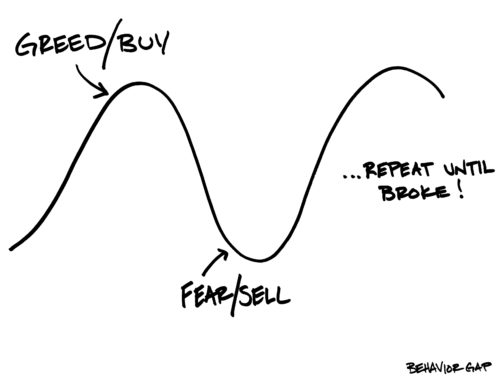
One of the most time-honored market adages states that markets fluctuate between greed and fear. Marks adds an important nuance to this notion, asserting that “It didn’t take long for me to realize that often the market is driven by greed or fear. Either the fearful or greedy predominate, and they move the market dramatically.” He adds:

Investor psychology seems to spend much more time at the extremes than it does at a happy medium. In the real world, things generally fluctuate between pretty good and not so hot. But in the world of investing, perception often swings from flawless to hopeless. In good times, we hear most people say, “Risk? What risk? I don’t see much that could go wrong: look how well things have been going. And anyway, risk is my friend – the more risk I take, the more money I’m likely to make.” Then, in bad times, they switch to something simpler: “I don’t care if I never make another penny in the market; I just don’t want to lose any more. Get me out!” Buy before you miss out gets replaced by sell before it goes to zero.

Without a doubt, valuations matter. Historically, when valuations have stood at nosebleed levels, it has been only a matter of time before misery ensued. Conversely, when assets have declined to the point where valuations were compelling, strong returns soon followed. But it is important to distinguish cause from effect. Extreme valuations (either cheap or rich) that portend bull and bear markets are themselves the result of extremes in investor psychology. Importantly, human emotions are both fickle and impossible to precisely measure. Noted physicist and Nobel Prize winner Richard Feynman articulately encapsulated this fact, stating “Imagine how much harder physics would be if electrons had feelings!”

Amnesia: The Great Enabler of Market Cycles

Another contributor to irrational investment decisions, and by extension market cycles, is the seemingly inevitable tendency of investors to engage in Groundhog Day-like behavior, forgetting the lessons of the past and suffering the inevitable consequences as a result. According to famed economist John Kenneth Galbraith, “Extreme brevity of financial memory” keeps market participants from recognizing the recurring nature of cycles, and thus their inevitability. In his book, A Short History of Financial Euphoria, he states:

When the same or closely similar circumstances occur again, sometimes in only a few years, they are hailed by a new, often youthful, and always supremely self-confident generation as a brilliantly innovative discovery in the financial and larger economic world. There can be few fields of human endeavor in which history counts for so little as the world of finance. Past experience, to the extent that it is part of memory at all, is dismissed as the primitive refuge of those who do not have the insight to appreciate the incredible wonders of the present.

Average and Normal: Not the same thing

In many ways markets resemble the swinging pendulum of a clock, which on average lies at its midpoint yet spends very little time there. Rather, it spends the vast majority of the time at varying distances to either the right or left of center. In a similar vein, most people would be surprised by both the frequency and magnitude by which stocks can deviate from their average performance, as indicated by the table below.
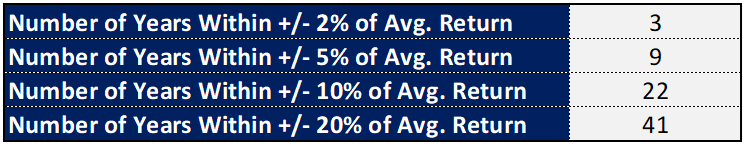
S&P 500 Index: Deviation from Long-Term Average (1972-2021)

Over the past 50 years, the average annual return of the S&P 500 Index has been 12.6%. The Index fell within +/- 2% of this number in only three of these years, within +/- 5% in only nine, and within +/- 10% in 22 (still less than half the time). Lastly, the index posted a calendar year return of +/- 20% of its long-term average return in nine of the past 50 years (18% of the time).

Also, when a pendulum swings back from the far left or right, it never stops at the midpoint, but continues to the opposite extreme.  Similarly, markets rarely shift from being either overpriced or underpriced to fairly priced. Instead, they typically touch equilibrium only briefly before snowballing sentiment and resulting momentum cause a progression to the opposite extreme. Continue Reading…
New Equity-linked GICs offer equity twist on humble GIC

By Rachel Megitt, Vice President,

Term Investments & Savings, RBC

(Sponsor Content)

If you’re looking to grow your money, the future looks a lot different than it did even a few months ago, given the current volatility in the markets and intensifying inflation.

We often hear the adage “big risk equals big reward,” but what if you want the reward but aren’t comfortable taking the risk? This is where a new twist on a traditional investment is proving to be a powerful option: equity-linked GICs (Guaranteed Investment Certificates).

In the summer of 2021, we shook up our product line-up and added two new equity-linked GICs that also represented RBC firsts and proudly shared the news, including in a Findependence blog.

New GICs with an equity twist

Within the first six months, we saw client enthusiasm about these two new “GICs with an equity twist” surge well beyond our expectations. Our clients have been clamouring for these GIC options and we believe this reflects the overall desire of Canadian investors to tap into what equity-linked GICs provide: the appealing combination of a guarantee for their initial investment, plus the higher return potential that comes with an equity investment.

While we knew we had created two truly compelling and competitive GICs, we never imagined how strongly these new GICs would resonate across the country. The buzz surrounding these equity-linked options is helping reshape investment conversations in Canada. These GICs offer investors who are reluctant to buy individual equities the opportunity to step into the world of equity investing at both a pace and level of risk they are comfortable with. Continue Reading…

Can you retire using just your TFSA?

Image Courtesy of Cashflows & Portfolios

By Mark and Joe

Special to the Financial Independence Hub

The opportunity for Canadians to save and invest tax-free over decades could be considered one of the greatest wonders of our modern financial world. This begs an important question:

If you start early enough – Can you retire using just your TFSA?

We believe so and in today’s post we’ll show you how!

Can you retire using just your TFSA? Why the TFSA is a gift for all Canadians!

Our Canadian government introduced TFSAs in 2009 as a way to encourage people to save money. Looking back, it was one of the best incentives ever created for Canadian savers …

Our Canada Revenue Agency has a HUGE library of TFSA links and resources to check out but we’ll help you cut to the chase along answering that leading question above:

Can you retire using just your TFSA?

Why the TFSA is just so good

Since the TFSA was introduced, adult Canadians have had a tremendous opportunity to save and grow their wealth tax-free like never before. While the TFSA is similar to a Registered Retirement Savings Plan (RRSP) there are some notable differences.

As with an RRSP, the TFSA is intended to help Canadians save money and plan for future expenses. The contributions you make to your TFSA are with after-tax dollars and withdrawals are tax-free. You can carry forward any unused contributions from year to year. There is no lifetime contribution limit.

For savvy investors who open and use a self-directed TFSA for their investments, these investors can realize significant gains within this account.  This means one of the best things about the TFSA is that there is no tax on investment income, including capital gains!

How good is that?!

Here is a summary of many great TFSA benefits:

  • Capital gains and other investment income earned inside a TFSA are not taxed.
  • Withdrawals from the account are tax-free.
  • Neither income earned within a TFSA nor withdrawals from it affect eligibility for federal income-tested benefits and credits (such as Old Age Security (OAS)). This is very important!!
  • Anything you withdraw from your TFSA can be re-contributed in the following year, in addition to that year’s contribution limit, although we don’t recommend that. More in a bit.
  • While you cannot contribute directly as you could with an RRSP, you can give your spouse or common-law partner money to put into their TFSA.
  • TFSA assets could be transferable to the TFSA of a spouse or common-law partner upon death. This makes the TFSA an outstanding estate management account – leaving TFSA assets “until the end” can be very tax-smart.

Since you paid tax on the money you put into your TFSA, you won’t have to pay anything when you take money out. This feature combined with the ability to compound money, tax-free, over decades, can make the TFSA one of the best ways to build wealth for retirement.

RRSP vs. TFSA – which one is better?

There is no shortage of blog posts that highlight this debate and one of our favourites is from My Own Advisor. You can check out his post here. 

Without stealing too much of his thunder, the RRSP vs. TFSA debate essentially comes down to this: managing the RRSP-generated refund.

Let’s dive deeper with a quick example.

Contributions to the RRSP are excellent because the contribution you make today lowers your taxable income – and you may get a tax refund because of it – a pretty nice formula. The problem is, some Canadians might spend the RRSP-generated refund from their contribution. You’ll see why this is a major problem.

Consider working in the higher 40% tax bracket whereby RRSP contributions to lower your taxable income make great sense:

  • If you put $300 per month into the RRSP for the year, that’s a nice $3,600 contribution.
  • You’ll get a $1,440 refund (40% of $3,600).

When your $1,440 RRSP-generated refund comes in, and now you decide to spend it on a new iPhone, just know that your RRSP refund is effectively borrowed government money. Yup, a long-term loan from the government they are going to come back for. If you always spend your refund you are undermining the effectiveness of RRSPs because you are giving up your government loan that would otherwise be used for tax-deferred growth.  A refund associated with your RRSP contribution should not be considered a financial windfall but the present value of future tax payment you must make.

If you typically spend the RRSP-generated refund in our example then we think some Canadians are FAR better off prioritizing your TFSA over your RRSP because of the known benefits of that present-day contribution.  

TFSAs offer tax-free growth for any income earner

At some point, the money that comes out of your RRSP (or Registered Retirement Income Fund (RRIF)) will be taxed.

With TFSAs, the government has eliminated the guesswork about taxation. Because the TFSA is like the RRSP, but in reverse (you don’t get any tax break on the TFSA contribution), TFSA withdrawals are tax-free.

For far more details including answering dozens of questions about this account, read on about our comprehensive TFSA post below:

If you haven’t contributed much towards your retirement and/or you can’t possibly save enough with so many competing financial priorities – that’s OK – striving to max out your TFSA contributions each year, every year, is still very valuable and admirable goal. In fact, focusing diligently on just maxing out your TFSA (and ignoring the RRSP account entirely) will still serve your retirement plan well.

Regardless of your income, any Canadian who is 18 years of age or older with a valid social insurance number (SIN) can open a TFSA. All you need to do is reach out to a financial institution, credit union or insurance company that offers TFSAs and open an account.

Whether you set up your automatic savings plan to your TFSA weekly, monthly, or other – striving to make the maximum contributions to this account can be a significant wealth-building tool as part of the Four Keys to Investing Success. 

Let’s use a case study to demonstrate just how good this account can be for you too – and why you can retire just using your TFSA!

Can you retire using just your TFSA – A Case Study

The big question in his article is – given enough time (ie. if you start young enough), can someone retire using only their TFSA?  The answer may surprise you, at least it surprised us!

To help accurately model this scenario to account for government benefits, inflation, taxes, tax credits, and optimized withdrawal schedules, we dove into the software that we are using to manage our own early retirement plans.

Here are the assumptions we made: Continue Reading…

A sensible RRSP vs. TFSA Comparison

A Sensible RRSP vs. TFSA Comparison

Should you contribute to your RRSP or your TFSA? It’s one of the most frequently asked questions here and on other financial forums, yet the answers couldn’t be more divided. Furthermore, there is a growing sentiment among Canadians that somehow RRSPs are a government scam because you’ll be forced to pay tax on any withdrawals in retirement. That leads many to (sometimes) incorrectly declare that a TFSA is the better savings vehicle for retirement due to the tax-free treatment of withdrawals.

Let’s start by clearing up one important fact in the RRSP vs TFSA debate: The accounts are mirror images of each other. When you put money in an RRSP and invest the tax refund, you’re using pre-tax dollars. The money grows inside a tax sheltered account and then you pay taxes on your withdrawals years later in retirement.

The opposite is true of a TFSA – you contribute with after-tax dollars but won’t have to pay taxes when you take money out. If you’re in the same tax bracket when you withdraw from your RRSP as you were when you made the contributions, the RRSP and TFSA work out to be exactly the same.

RRSP vs TFSA Comparison

Here’s a simple chart that David Chilton used in The Wealthy Barber Returns to help drive this point home:

TFSA RRSP
Pre-tax income $1,000 $1,000
Tax $400 n/a
Net contribution $600 $1,000
Value in 20 years @ 6% growth $1,924 $3,207
Tax upon withdrawal (40%) n/a $1,283
Net withdrawal $1,924 $1,924

Two important caveats to keep in mind:

  1. You need to invest the tax refund in order for RRSPs to work out as designed. Unfortunately, most Canadians spend their refund and so they don’t end up with as much money in their retirement account.
  2. A TFSA is flexible in that you can take out money at any time without penalty. For Canadians who use a TFSA as their primary retirement savings vehicle that means resisting the temptation to raid the account whenever “something” comes up. You should also replace the ‘S’ in TFSA with an ‘I’ and make sure to invest that money for the long-term. Continue Reading…

Rethinking the 4% Safe Withdrawal Rate


By Fritz Gilbert, TheRetirementManifesto

Special to the Financial Independence Hub

The 4% safe withdrawal rule is a well-known “rule of thumb” for those planning for retirement.

One thing it has going for it is that it’s simple to apply.

If you have $1 Million, the 4% safe withdrawal rule says you can spend $40,000 (4% of $1M) in year one of retirement, increase your spending by the rate of inflation each year, and you’ll never run out of money.

Simple, indeed.

But, I’d argue that simplicity comes at a potentially very serious cost.  Like, potentially running out of money in retirement.

Today, I’ll present my argument against the 4% safe withdrawal rule given our current economic situation, and propose 3 modifications I’d recommend as you determine how much you can safely spend in retirement.

Rethinking the 4% Safe Withdrawal Rule

I read a lot of information on retirement planning, and lately, I’ve been seeing more content challenging the 4% safe withdrawal rule.  I agree with those concerns and felt a post outlining my position was warranted.

As a brief background, the 4% Safe Withdrawal Rule is based on the “Trinity Study,” which appeared in this original article by William Bergen in the February 1998 issue of the Journal of the American Association of Individual Investors.  For further background, here’s an article that Wade Pfau published on the study.  I’ll save you the details, you can study them for yourself at the links provided.

The conclusion, based on the study, is summarized below:

“Assuming a minimum requirement of 30 years of
portfolio longevity, a first-year withdrawal of 4 percent,
followed by inflation-adjusted withdrawals in
subsequent years, should be safe.”


My Concerns With The 4% Safe Withdrawal Rule

In short, some key factors about the study are relevant, especially as we “Rethink The 4% Safe Withdrawal Rule”

  • It’s based on historical market performance from 1926 – 1992.  

My Concern:  Relying on past performance to predict future returns can mislead the investor, especially given the unique valuations in today’s markets (more on that below).  This point is driven home by this recent Vanguard article that projects future returns based on current market valuations:

4% safe withdrawal rule assumptions

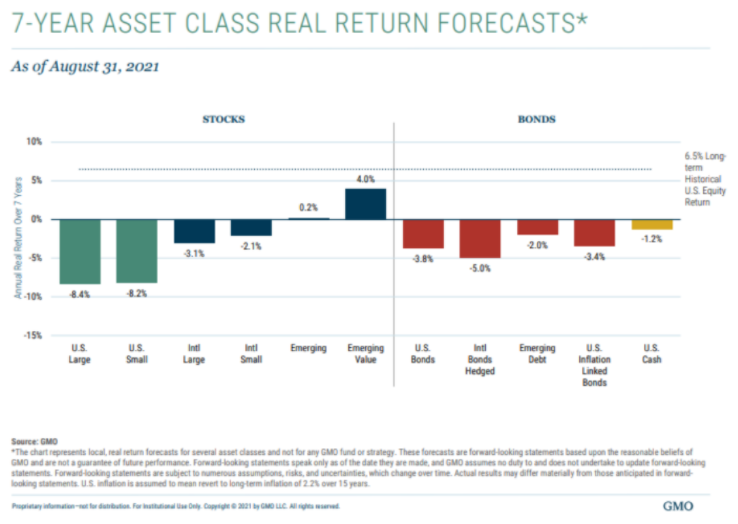
If you think the Vanguard outlook is depressing, check out this forecast from GMO as presented in this Wealth of Common Sense article titled “The Worst Stock and Bond Returns Ever”:

stock and bond forecast

  • Note the VG forecast is nominal (before inflation) whereas the GMO is real (after inflation).

Why Are Future Returns Expected to Be Below Average?

The biggest driver for the projected below-average returns is the high valuation in today’s equity market (particularly in the USA), and the fact that interest rate increases would negatively impact bond yield.  In my view the CAPE Ratio is one of the best indicators of market valuations.  Below is the current CAPE ratio as I write this post on November 16, 2021:

CAPE Ratio

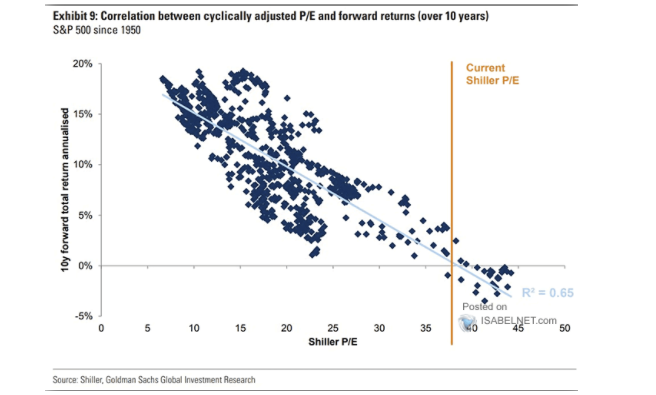
The reason current valuations matter is the fact that they’re highly correlated to future returns, as indicated from this concerning chart that I saw last weekend on cupthecrapinvesting:

CAPE ratio correlation to future returns

Based on today’s CAPE ratio, the historical correlation suggests the forward total returns over the next 10 years could be close to 0%.  Scary stuff for someone who’s planning on equity growth to pay for their retirement expenses.  Scary stuff for someone who’s committed to the 4% safe withdrawal rule.


In addition to the bearish outlook for US equities, bonds could be negatively impacted if when interest rates increase.  To get a sense of how low the US 10-year Treasury yields are now compared to long-term averages, below is the current chart of 10-year yields from CNBC:

4% safe withdrawal rate rule - bond impact

Bond prices are inversely related to interest rates, so as rates go up, bond prices go down.  So, if you’re holding 60% stocks and 40% bonds, it’s possible that you could see decreases in both asset classes.

As cited in this Marketwatch article, The Fed has begun signaling that interest rates are “on the table” for 2022, especially if the current bout of inflation proves to be less than a transitory event (for the record, I suspect it will be more than transitory, but what do I know?).

This brings us to the next concern …


My Other Big Concern With The 4% Safe Withdrawal Rule:

In addition to my concern above (the risk of an extended period of below-average market returns), I don’t like the part of the rule which states you should “increase your spending the following year based on the rate of inflation.”  As most of you know, inflation has been on a bit of a tear lately, as demonstrated in this chart from usinflationcalculator.com:

Based on the 4% Safe Withdrawal Rule, you would be increasing spending next year based on the higher inflation rate, which could well be the same time you’re seeing lower than expected returns.

I don’t know about you, but that doesn’t sit well with me.


Suggested Modifications to the 4% Safe Withdrawal Rule

It wouldn’t be fair to cite my concerns with the 4% Safe Withdrawal Rule without suggesting an alternative. Following are the 3 modifications I’d suggest for your consideration.  I’m applying all 3 of these modifications in our personal retirement strategy. Continue Reading…