General

Can you Invest solely in ETFs?

 Special to the Financial Independence Hub

As regular readers of MillionDollarJourney know, we are big fans of Exchange Traded Funds (ETFs) which are one of the fastest growing products in the market.

Were it not for the fact that financial firms and advisors have less incentives to sell ETFs than other investments such as mutual funds (that provide them with annual fees), the growth would probably be even more spectacular.

Having said that, ETFs don’t always have the best performance, and are sometimes outperformed significantly by other investment options. This also means that over years, the standard composition of most ETFs has shifted – with fixed income, commodities and FX now representing a much larger piece of the pie.

For most investors, ETFs represent the easiest and cheapest way to gain exposure in a variety of different sectors or asset classes. Investing in currencies or commodities was done by pension funds or hedge funds only a few years ago but it is now just as easy to do so for individual investors.

It might not be 100%, but a very large majority of individuals and professionals believe that portfolio diversification represents an important way to gain the same return but with lower risk. 20 years ago that meant buying bonds, private investments, etc. The major problem with that strategy is illiquid investments are often very expensive if you are not pouring a major amount of capital.

A prime example is looking at the prices of a bond when you are buying $50,000 worth. It is understandable of course that sellers will give better prices to buyers of millions of dollars as it is an easier trade for them. Take a few percentage points here and there and you will see just how much of an impact it can have over a life of savings and investing.

Investing in ETFs – Pros and Cons

So, should you invest mostly (or only) in ETFs? Here are some of the common pros and cons to help you decide:

ETF Investing Advantages

  • Most diversified
  • More tax efficient (read our article on capital gains in Canada)
  • Easiest and quickest way to invest

ETF Investing Disadvantges

  • Costs can be high, depending on the broker you use
  • Still has some investing risks

Should Canadians invest only in ETFs?

In many ways, ETFs provide a viable alternative as they offer the opportunity to get broad (corporate bonds) or specific (1-3 year treasuries) positions that will not cost you much in terms of commission.  Furthermore, ETFs will get you much better pricing and potentially much improved returns over the long term. Continue Reading…

Despite inflation, Canadians still prioritizing retirement and contributing to RRSPs and TFSAs

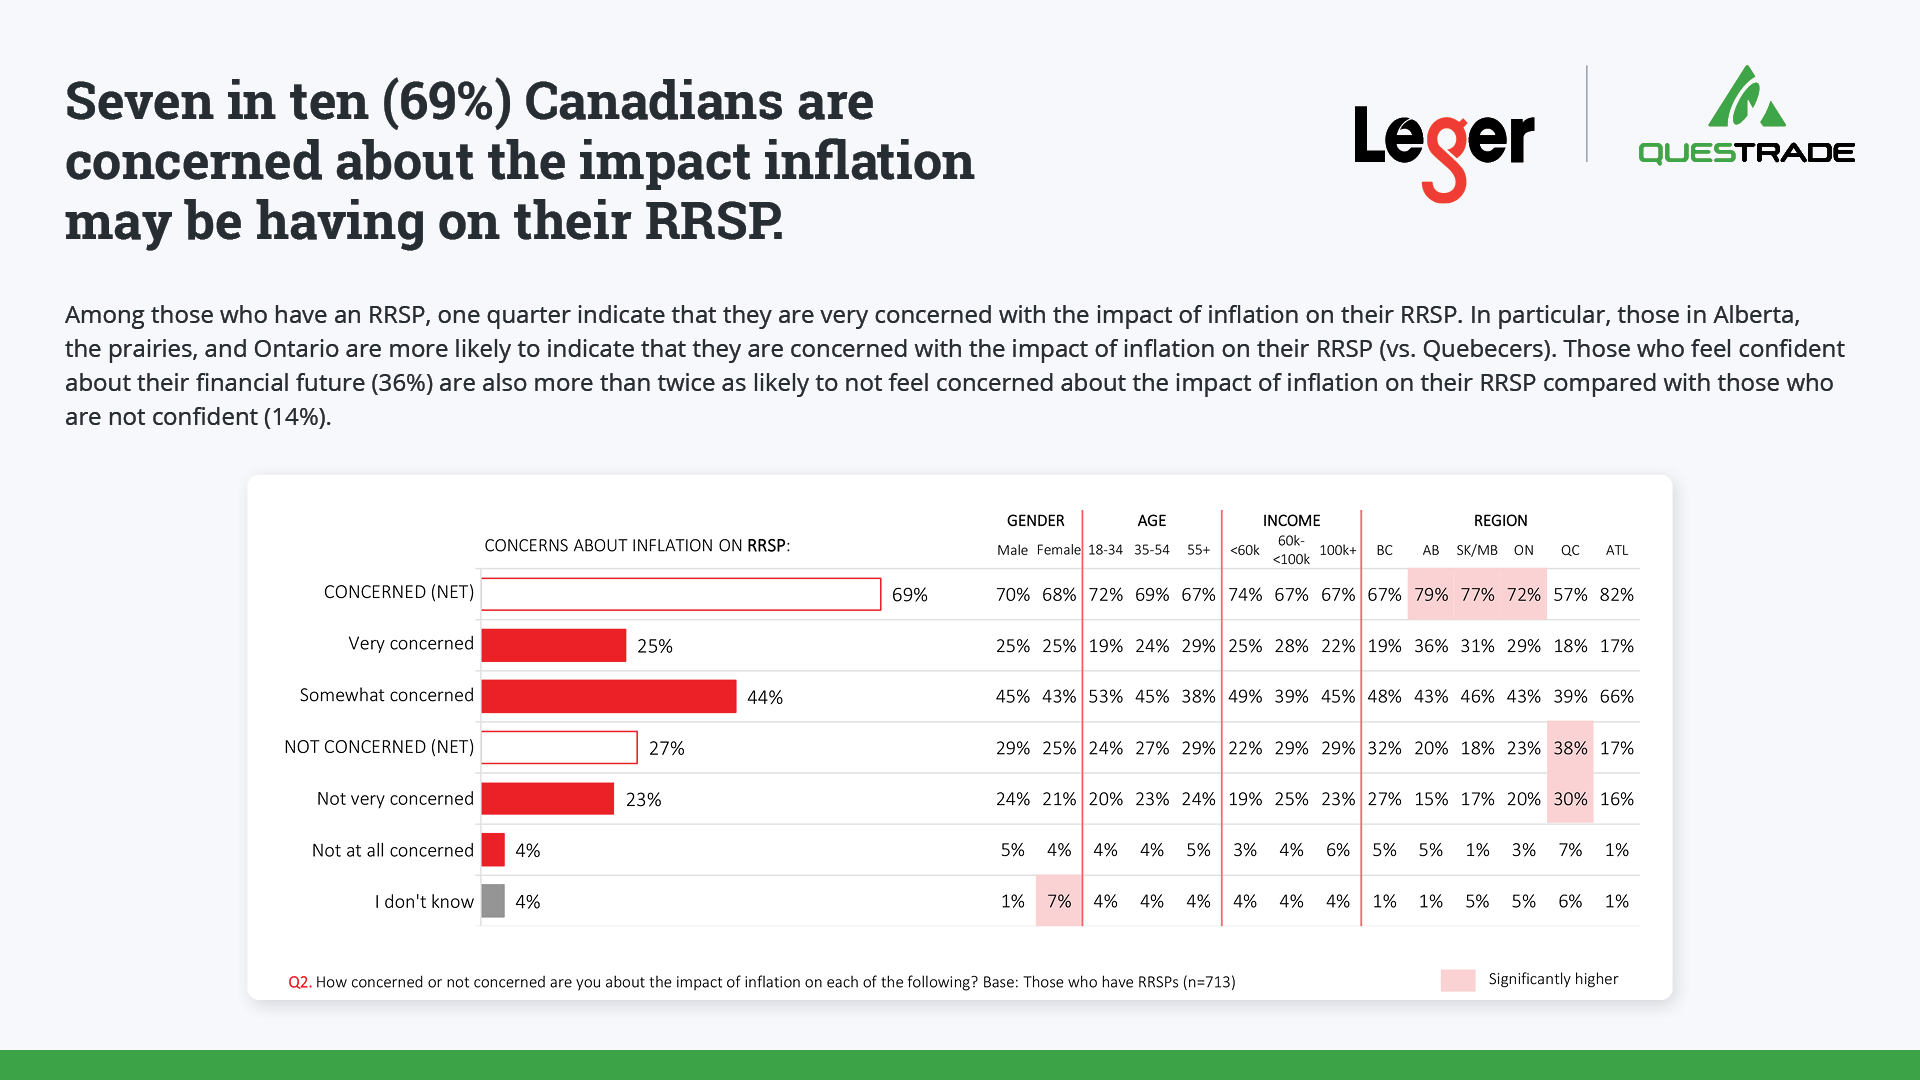
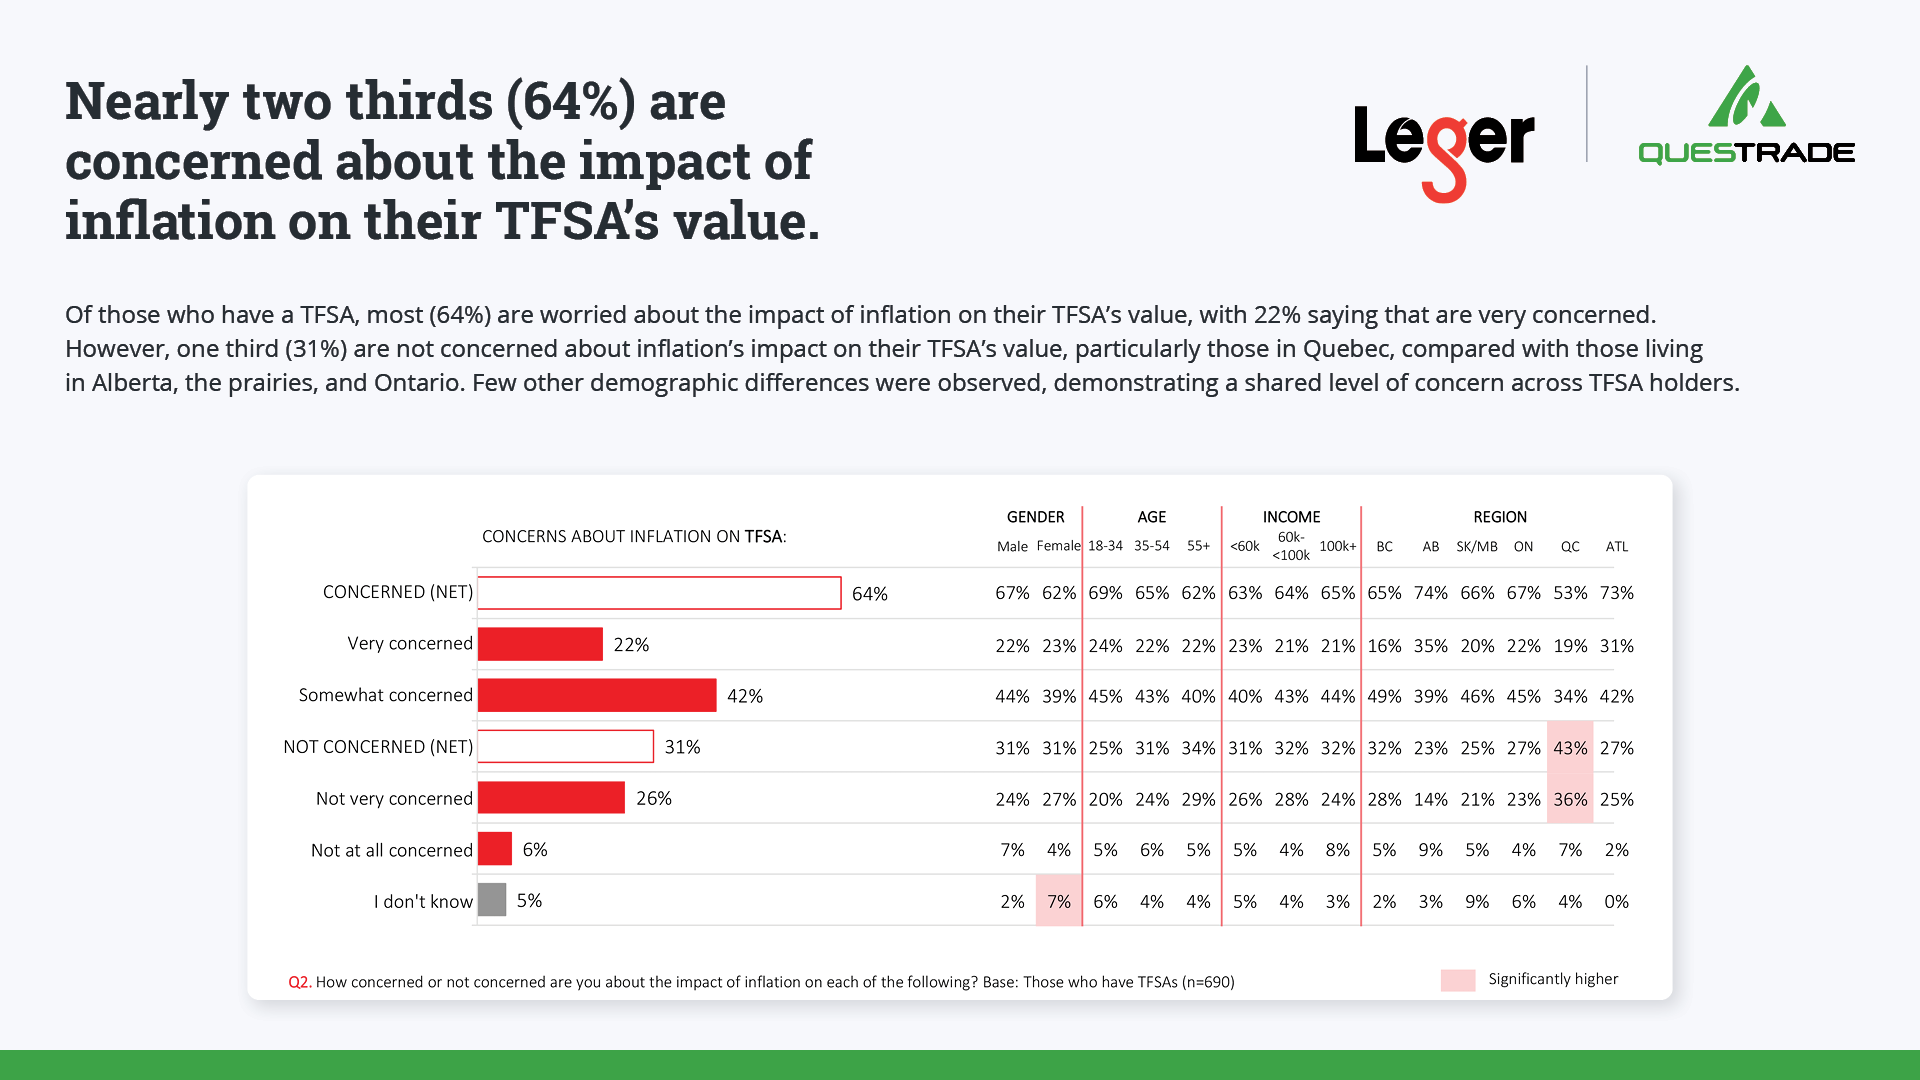
While the vast majority (87%) of Canadians are worried about rising costs from Inflation, Questrade Leger’s 2023 RRSP Omni report finds that 73% of RRSP owners plan to contribute again this year, and 79% of TFSA holders plan to recontribute. That’s despite the fact 69% fret that inflation will impact their RRSP’s value and 64% worry about the impact on their TFSA’s value.

“The number of Canadians who are saving for retirement remains consistent with previous years,” the report says. “Among those who are saving for retirement, about three-in-five (58%) say they are very worried compared to Canadians who are not saving for retirement. Women are also more likely to be very worried about the costs associated with rising inflation.”

Seven in ten respondents who have RRSPs told the panel they are concerned about the rising costs associated with inflation and a possible recession: 25% indicate that they are very concerned. “A similar trend is observed among those who hold TFSAs for retirement purposes, with almost two-thirds (64%) indicating that they are concerned.”


Worries about inflation and recession “raise questions about the ability of Canadians to control their financial future, especially when it comes to retirement,” the report says. These concerns are most acute for those with an annual income of less than $100,000: “These Canadians are also more likely to agree that they will have to draw upon their savings or investments to cover their expenses in the coming year.”

Less than half are confident about their financial future

Less than half feel they are confident when it comes to their financial future: “Only those making over $60K have confidence in their own financial future despite the current state of the economy.”

The survey seems to imply that Canadians value TFSAs a bit more than RRSPs, based on willingness to max out contribution room of each vehicle. Of course, annual TFSA room only this year moved up to $6500 per person per year, less than a quarter of the maximum RRSP room of $30,780 in 2023, for those with maximum earned income.

Only 29% of RRSP holders plan to maximize their RRSP contribution room in 2023, compared to almost half (46%) who plan to max out their TFSAs. The most enthusiastic TFSA contributors are males and those aged 55 or older.

Given economy, most worry about rising cost of food and everyday items  

Day-to-day living expenses continue to be a concern in the face of rising inflation: 79% worry about rising food prices and 77% rising everyday items. The third major concern (for 45%) is inflation’s impact on savings/investments and fourth (at 30%) is rising mortgage costs. Depending on annual incomes, worry over inflation can centre either on investments or on debt:  those in the middle to upper income brackets ($60K or more) “are much more likely to find the impact on savings / investments and increasing mortgage concerns more worrisome than compared to those who make less than $60K.”

Ability to save impacted by inflation

Three in four (74%) agree that inflation has impacted their ability to save, at least somewhat. And half (47%) have had to draw upon their savings or investments to cover expenses due to rising costs, especially those under 55 and those who are not currently saving for retirement. Many Canadians also agree they will have to draw upon their savings/investments to cover expenses in the coming year (43%). Continue Reading…

How to navigate a coming Worldwide recession

Source: myownadvisor and https://www.thecanadianencyclopedia.ca/en/article/recession

By Mark Seed, myownadvisor

Special to Financial Independence Hub

According to the largest asset manager firm in the world (BlackRock), policymakers will no longer be able to support markets as much as they did during past recessions – so we have been warned – a team of BlackRock strategists led by vice chairman Philipp Hildebrand wrote in a report titled 2023 Global Outlook.

“Recession is foretold as central banks race to try to tame inflation. It’s the opposite of past recessions,” they said. “Central bankers won’t ride to the rescue when growth slows in this new regime, contrary to what investors have come to expect. Equity valuations don’t yet reflect the damage ahead.”

The report went on to say “The old playbook of simply ‘buying the dip’ doesn’t apply in this regime of sharper trade-offs and greater macro volatility. We don’t see a return to conditions that will sustain a joint bull market in stocks and bonds of the kind we experienced in the prior decade.”

I reflected on this report recently. How is an investor to cope?

Well, I think the “old playbook” is actually something I’ve already started to think about for the “new playbook” and maybe you have as well …

  1. Directionally, i.e., longer-term than one year or so, stay with equities. Lots of them. In fact, to be specific, consider infrastructure stocks in particular. BlackRock: “We see some opportunities in infrastructure. From roads to airports and energy infrastructure, these assets are essential to industry and households alike. Infrastructure has the potential to benefit from increased demand for capital over the long term, powered by structural trends such as the energy crunch and digitalization.”
  2. Tactically, i.e., within the next year, if you need that money balance, consider bonds. Yes, consider fixed income again. According to BlackRock: “In fixed income, the return of income and carry has boosted the allure of certain bonds, especially short term. We don’t think leaning into broad indexes or asset allocation blocks is the correct approach. We stay underweight long-term nominal bonds as we see term premium returning due to persistent inflation, high debt loads and thinning market liquidity.” Meaning, if you are going to own some bonds, stay short and own short-duration bonds.

I come back to Ben Carlson’s thesis (that I agree with) after reading this recent BlackRock global outlook report when it comes to bonds. There are absolutely good reasons to own bonds, but it’s more for the near-term variety:

  1. Bonds can help your investing behaviour – helping you ride out stock market volatility – including being strategic to buy more stocks soon.
  2. Bonds can be used to rebalance your portfolio – helping you keep your portfolio aligned to your investing risk tolerance and therefore asset allocation (mix of stocks and bonds).
  3. Bonds can be used for spending purposes – where some fixed income is “king” for major, upcoming, near-term spending.

The main reason I would keep any bonds (and I still don’t have any right now) is if I was saving for a major purchase in a few years (e.g., secondary residence?). Then, I would like rely on some form of fixed income between now and then to help secure that purchase. Otherwise, an interest savings account in the short-term will do that and/or some 1 or 2-year GICs are a great consideration as well as part of any bucket strategy.

Personally, I believe the main role of fixed income in your portfolio is essentially safety – not the investment returns and not the cash flow needs. In other words, if all else fails per se, if/when stocks crash, then bonds should historically speaking offer a flight to safety for preserving principal.

So, they are there for diversification purposes.

As Andrew Hallam, a Millionaire Teacher has so kindly put it over the years: when stocks fall hard, bonds act like parachutes for your portfolio. Bonds might not always rise when the equity markets drop. But broad bond market indexes don’t crash like stocks do.

Is that enough to own bonds in your portfolio? Maybe.

For now, I’m going to continue living with stocks: a mix of dividend-paying stocks (including infrastructure stocks that BlackRock likes for the year or so ahead) AND owning low-cost equity ETFs for growth.

I will also grow my cash wedge to my desired safety net by the end of 2023 too. That’s one year’s worth of spending/expenses held in cash that will form Bucket 1 below. That first bucket is an insulator from my dividend and growth equities.

Your mileage may vary. Continue Reading…

Building the big Dividend Retirement Portfolio with defensive Canadian ETFs


By Dale Roberts, Cutthecrapinvesting

Special to the Financial Independence Hub

There are a few reasons to play defense. A retiree or near retiree can benefit from less volatility and a lesser drawdown in a bear market. If your portfolio goes down less than market, and there is a greater underlying yield, that lessens the sequence of returns risk. You have the need to sell fewer shares to create income. For those in the accumulation stage it may be easier to stay the course and manage your portfolio if it is less volatile. You can build your portfolio around defensive Canadian ETFs.

For a defensive core, investors can build around utilities (including the modern utilities of telcos and pipelines), plus consumer staples and healthcare stocks. My research and posts have shown that defensive sectors and stocks are 35% or more “better” than market for retirement funding.

I outlined that approach in – building the retirement stock portfolio.

We can use certain types of stocks to help build the all-weather portfolio. That means we are better prepared for a change in economic conditions, as we are experiencing in 2022.

Building around high-dividend Canadian ETFs

While I am a total return guy at heart, I will also acknowledge the benefit of the Canadian high-dividend space. These big dividend payers outperform to a very large degree thanks to the wide moats and profitability. Those wide moats create that defensive stance or defensive wall to be more graphic. And of course, you’re offered very generous dividends for your risk tolerance level troubles.

Canadian investors love their banks, telcos, utilities and pipelines. The ETF that does a very good job of covering that high-dividend space is Vanguard’s High Dividend ETF – VDY. The ‘problem’ with that ETF is that it is heavily concentrated in financials – banks and insurance companies.

Vanguard VDY ETF as of November 2022.

Sector Fund Benchmark +/- Weight
Financials 55.4% 55.4% 0.0%
Energy 26.3% 26.2% 0.1%
Telecommunications 9.0% 9.0% 0.0%
Utilities 6.2% 6.2% 0.0%
Consumer Discretionary 1.9% 1.9% 0.0%
Basic Materials 0.6% 0.6% 0.0%
Industrials 0.4% 0.4% 0.0%
Real Estate 0.2% 0.2% 0.0%
Total 100.0% 100.0%

VDY is light on the defensive utilities and telcos. The fund also has a sizable allocation to energy that is split between oil and gas producers and pipelines. The oil and gas producers will also be more sensitive to economic conditions and recessions.

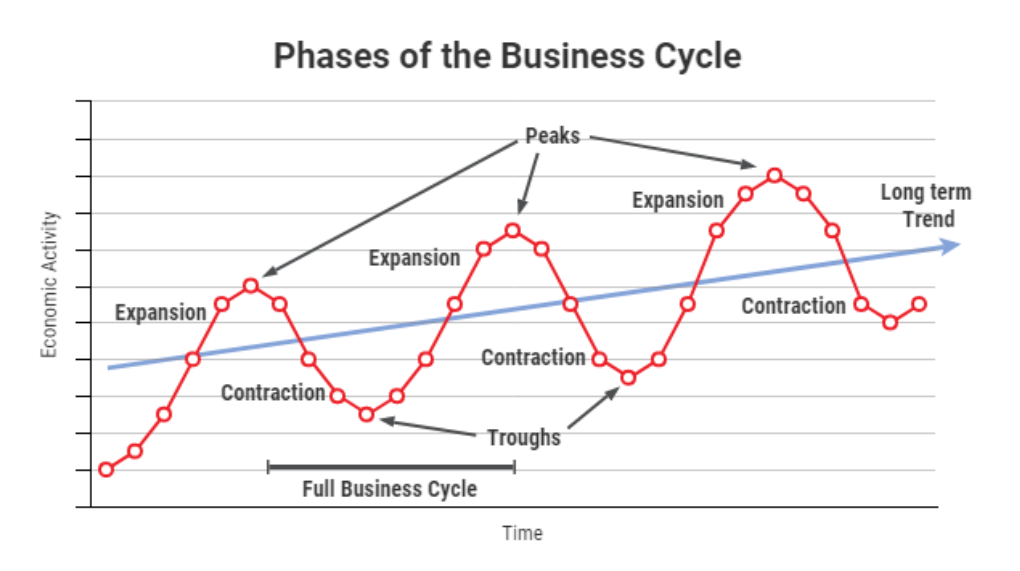
Greater volatility can go along for the ride in VDY as it is financial-heavy. And those are largely cyclical. They do well or better in positive economic conditions. But they can struggle during time of economic softness or recessions. Hence, we build up more of a defensive wall.

Building a wall around VDY

We can add more of the defensive sectors with one click of that buy button. Investors might look to Hamilton’s Enhanced Utility ETF – HUTS. The ETF offers …

█  Pipelines 26.8%

█  Telecommunication Services 23.5%

█  Utilities 49.6%

The current yield is a generous 6.5%. Keep in mind that the ETF does use a modest amount of leverage. Here are the stocks in HUTS – aka the usual suspects in the space.

BMO also offers an equal weight utilities ETF – ZUT .

And here’s the combined asset allocation if you were to use 50% Vanguard VDY and 50% Hamilton HUTS.

  • Financials 26.7%
  • Utilities 24.9%
  • Energy 26.5%
  • Telecom 16.2%

Energy includes pipelines and oil and gas producers. And while the energy producers can certainly offer more price volatility, there is no greater source of free cashflow and hence dividend growth (in 2021 and 2022). In a recent Making Sense of the Markets for MoneySense Kyle offered … Continue Reading…

TFSA contribution is Job One in 2023 and other inflation-related tax changes to consider


A belated Happy New Year to readers. Today I wanted to start with a reminder that your first Financial New Year’s Resolution should always be to top up your TFSA contribution to your TFSA (Tax-free savings account), which because of inflation has been bumped to $6,500 for 2023. I’ll also link to two useful columns by a financial blogger and prominent media tax expert.

A must read is Jamie Golombek’s article in Saturday’s Financial Post (Dec. 31/2022), titled 11 tax changes and new rules that will affect your finances in 2023. Golombek is of course the managing director, Tax & Estate planning for CIBC Private Wealth.

He doesn’t lead with the TFSA but does note that the cumulative TFSA limit is now $88,000 for someone who has never contributed to a TFSA. On Twitter there is a community of Canadian financial bloggers who often reveal their personal TFSA portfolios, which tend to be mostly high-yielding Canadian dividend-paying stocks. In some cases, their TFSA portfolios are spinning out as much as $1,000 a month in tax-free income.

On a personal note, my own TFSA was doing nicely until 2022, when it got dragged down a bit by US tech stocks and a token amount of cryptocurrency. Seeing as I turn 70 this year, I’ll be a lot more cautious going forward. I’ll let the existing stock positions run and hopefully recover but my new contribution yesterday was entirely in a 5-year GIC, even though I could find none paying more than 4.31% at RBC Direct, where our TFSAs are housed. (I’d been under the illusion they would by now be paying 5%. I believe it’s still possible to get 5% at independents like Oaken and EQ Bank.)

At my stage of life, TFSA space is too valuable to squander on speculative stocks, IPOs, SPACs or crypto currencies. Yes, if you knew for sure such flyers would yield a quick double or triple, it would be a nice play to “sell half on the double,” but it’s better to place such speculations in non-registered accounts, where you can at least offset capital gains with tax-loss selling. So for me and I’d suggest others in the Retirement Risk Zone, it’s interest income and Canadian dividend income in a TFSA and nothing else.

Inflation and Tax Brackets

Back to Golombek and inflation. Golombek notes that in November 2022, the Canada Revenue Agency said the the inflation rate for indexing 2023 tax brackets and amounts would be 6.3%:

“The new federal brackets are: zero to $53,359 (15 per cent); more than $53,359 to $106,717 (20.5 per cent); more than $106,717 to $165,430 (26 per cent); more than $165,430 to $235,675 (29 per cent); and anything above that is taxed at 33 per cent.”

Basic Personal Amount

The Basic Personal Amount (BPA) — which is the ‘tax-free’ zone that can be earned free of any federal tax — rises to $15,000 in 2023, as legislated in late 2019. Note Golombek’s caveat that higher-income earners may not get the full, increased BPA but will still get the “old” BPA, indexed to inflation, of $13,521 for 2023.

RRSP limit: The RRSP dollar limit for 2023 is $30,790, up from $29,210 in 2022.

OAS: Golombek notes that the Old Age Security threshold for 2023 is $86,912, beyond which it begins to get clawed back.

First Home Savings Accounts (FHSA). Golombek says legislation to create the new tax-free FHSA was recently passed, and it could be launched as soon as April 1, 2023. This new registered plan lets first-time homebuyers save $40,000 towards th purchase of a first home in Canada: contributions are tax deductible, like an RRSP. And it can be used in conjunction with the older Home Buyers’ Plan.

3 investing headlines to ignore this year

Meanwhile in the blogosphere, I enjoyed Robb Engen’s piece at Boomer & Echo, which ran on January 1st: 3 Investing Headlines To Ignore This Year. Continue Reading…