Canadians face a lot of headwinds in this volatile investing year, including high inflation, rising interest rates, slower economic activity and geopolitical shocks. In this turbulent environment, an actively managed income strategy can help steer the way through uncertainty. Volatile markets call for a strategy that can adjust client portfolios in a timely, tactical way as market conditions shift.
Active investment management can play a key role in offering a compelling risk-reward option for investors who are looking for income, growth and overall portfolio diversification. The strategy that underlies the Franklin U.S. Monthly Income Fund is an example of an approach to seeks to give investors stability amid volatility.
“The fund has a portfolio that can make adjustments in a timely manner on your behalf,” said Rob Rocoff, Vice President, Regional Sales with Franklin Templeton Canada in Toronto. “It’s a fund that uses a flexible, balanced strategy that is capital structure agnostic and has a track record in the U.S. of over 70 years of being able to tactically adjust to volatile market conditions.”
The Franklin U.S. Monthly Income strategy aims to generate income by investing in stocks, bonds and hybrid securities, such as equity-linked notes (hybrid securities have characteristics of both stocks and bonds). The strategy’s flexible asset allocation allows it to adjust across different market cycles, including moments of high pressure, to find the most attractive investment opportunities.
The Franklin U.S. Monthly Income strategy looks throughout the capital structure for securities that offer attractive income and long-term growth potential. Top-down insights inform the investment team’s view on asset allocation, while the security selection process is driven by rigorous bottom-up fundamental research. The team focuses on investment opportunities where their fundamental views may differ from the market consensus, especially with investments in large companies.
Seeking Yield from multiple sources
As a result, the fund’s portfolio includes equities (common or preferred stocks), fixed income assets (e.g., investment grade bonds, Treasuries) or hybrids (e.g., equity-linked notes and convertibles). This mix seeks yield from multiple sources and allows for dynamic asset allocation, depending on market conditions. Continue Reading…
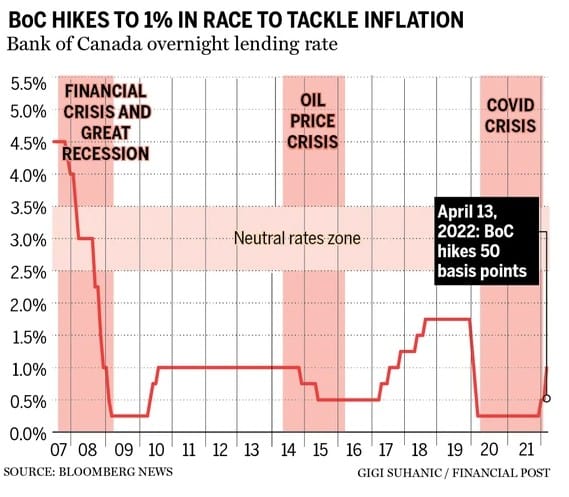
Lately, the talk of the town seems to be rising interest rates. In April, the Bank of Canada raised the benchmark interest rate by a whopping 0.5% to 1%, making it the biggest rate hike since 2000. Given the high inflation rate, it is almost a given that these rate hikes will continue throughout 2022 and beyond. [On July 13, 2022, the BOC hiked a further 1%: editor.]
But before you freak out, let’s step back and look at the big picture. At 1%, the benchmark interest rate is still relatively low compared to the past interest rates.
I still remember years ago before the financial crisis, being able to get GIC rates at around 5%. And some people may remember +10% interest rates in the 80s or early 90s. Back then, interest rates were much much higher than measly below 1% rates we’ve been seeing the last decade.
Historical BoC overnight rates
What’s going to happen to the stock market? Well the general rule is that when Bank of Canada or the Federal Reserve cuts interest rates, the stock market goes up. When Bank of Canada or the Federal Reserve raises interest rates, the stock market goes down.
It’s been awhile since I reviewed any political books here on the Hub. The last time was this time a year ago when I surveyed what were then the latest books on the Trump presidency (at one point in 2021, 3 of the top 6 New York Times bestselling books were on Trump: see here).
I occasionally wade in on this topic on the grounds that investors need to be on top of this seemingly unique political situation. That’s despite the fact that when Trump first won his shock victory in 2016, markets briefly cratered, only to quickly recover.
The particular pair of mini-reviews below has no real financial angle but you can see I explicitly covered that a few years ago in a MoneySense column that evaluated the implications of the Trump presidency for the Boomers’ collective retirements: see here.
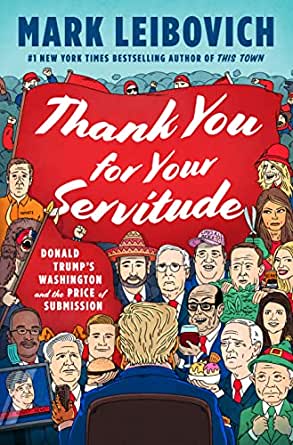
Over the long weekend, I finished reading two recently published books that some may find of interest, whose covers are illustrated on this blog. One is Thank You for Your Servitude, Mark Leibovich’s entertaining summary of all the Republican enablers who made the Trump presidency possible in the first place, and may yet facilitate a dreaded second term. The other is This Will Not Pass [Simon & Schuster) by Jonathan Martin and Alexander Burns, subtitled Trump, Biden, and the Battle for America’s Future. The co-authors are both New York Times writers and CNN political analysts, neither known as MAGA-friendly outlets.
Save your money and borrow these from the library
I might add that, despite being an author myself, I generally refuse to buy any of these US political books: I either read ebooks from the Toronto Library’s excellent Libby app, or download ebooks or audio books from the paid SCRIBD service. Libby often involves waiting a few weeks or months for popular bestsellers; however, if you can read quickly, you may be able to luck into the occasional Skip the Line service, which lasts only a single week. SCRIBD sometimes has books not yet on Libby, often in audio format, and unlike the library, you can keep them beyond the normal three-week limit.
There’s been a fair bit of press and YouTube clips on both these books. Formerly with the New York Times, Leibovich is perhaps best known for his bestselling This Town, about 21st century Washington. Thank You for Your Servitude [Penguin Press, New York, 2022] is subtitled Donald Trump’s Washington and the Price of Submission. While the author admits that many of the anecdotes will be all too familiar to anyone following the daily press, he manages to provide a fresh perspective on them while simultaneously apologizing for making readers relive the worst of these moments. Many of them center around Trump’s Washington-based Trump Hotel, which is where the book begins and ends. There you meet such familiar characters as Rudy Giuliani, Reince Priebus, Kevin McCarthy, Mitch O’Connell, William Barr, Jeff Sessions, Lindsay Graham, Marjorie Taylor Greene, Kellyanne Conway and the whole sordid collection of Trump toadies and sycophants, or the so-called MAGAts.
One early chapter is entitled “The Joke,” which apparently is how even how Trump’s closest enablers seem to view his rise to the top of the political pyramid:
It would be risky, obviously, for a Republican member of Congress to declare, explicitly, that “Donald Trump is a complete ignoramus,” even though that’s what they really believed. But none of this had to be spoken because the truth of this scam, or “joke,” was fully evident inside the club …. Everyone … got the joke.
Covers Ukraine invasion but not January 6th hearings
The book is recent enough that it includes an epilogue about the Russian invasion of Ukraine in February. The book ends on a despairing note of pessimism about the prospects of anyone stopping Trump in 2024. Of course, it was published months before this summer’s high-profile January 6th hearings, nor does he spend much time addressing any of the other multiple investigations into Trump’s businesses and political shenanigans.
The following telling snippet is one of many that may not be widely known. I was struck by the revelation in the epilogue that within a day of Trump’s “Be there, will be wild” tweet promoting the January 6 rally, the cheapest room in the Trump Hotel immediately jumped from US$476 to US$1,999.
Donald Trump didn’t just inspire the Jan. 6 riot … He seems to have made money off it.
That pretty much says it all. Leibovich ends with an ominous foreshadowing of Trump’s possible triumphant return in 2024. His final sentence is “And who’s going to stop him?” A few sentences earlier, he quotes a former Republican congressman who confessed that the party’s only real plan for dealing with Trump in 2024 involved a darkly divine intervention: “We’re just waiting for him to die .. That was it, that was the plan. He was 100 percent serious.”
Can Joe Biden extract the US from its “political emergency?”
Simon & Schuster
Those who are thoroughly sick of Trump — as I am — may find This Will Not Pass more to their liking, as roughly half the content is devoted to Trump’s successor, Joe Biden. The focus is what it describes as the “political emergency in the United States: the story of how the country reached and survived a moment when carrying out the basic process of certifying an election became a mortally dangerous task.”
It recounts how the country “sort of” survived but like Leibovich, leaves readers pretty nervous about what may yet occur in the 2022 mid terms this fall and ultimately in 2024. As Martin and Burns remind us (as if we needed it!):
Donald Trump has not been banished from national life, but instead remains the dominant force in his party and is bent on purging those few Republicans who won’t bow to him … The former president’s delusions about a stolen election … have lingered with corrosive force, warping his own party and catalyzing a wave of red-state voting restrictions aimed at cracking down on election fraud that did not happen. The fantasies of a Trump restoration have only deepened since his departure from the White House.
The book is arranged in three parts: the year before the 2020 election and Trump’s mismanagement of Covid; the tumultuous months between the contested 2020 election and Inauguration Day, and everything that has transpired since:
… As President Biden attempted an acrobatic feat of leadership: pushing a liberal policy agenda of titanic ambition with the thinnest of majorities … Far from quickly erasing the Trump era, leaders in both parties have found the shadow of the last presidency has been longer and darker than they anticipated, colouring every major political decision and legislative negotiation of the Biden administration and shaping even the perceptions of American democracy overseas.
Ambitious, yes: One chapter nicely summarizes the dominant question before Biden as “How Big Can We Go?”
Unlike Servitude, This Will Not Pass was published too soon to cover much of the events of 2022. Oddly, for an American book, it closes with an observation by a Canadian, Bob Rae (at one point Canada’s ambassador to the United Nations.) He calls Trump an “authoritarian … I don’t believe the Republican Party believes in democracy.” And he warned that the threat to American democracy was far from defeated: “America,” he said, “is a very important battleground.”
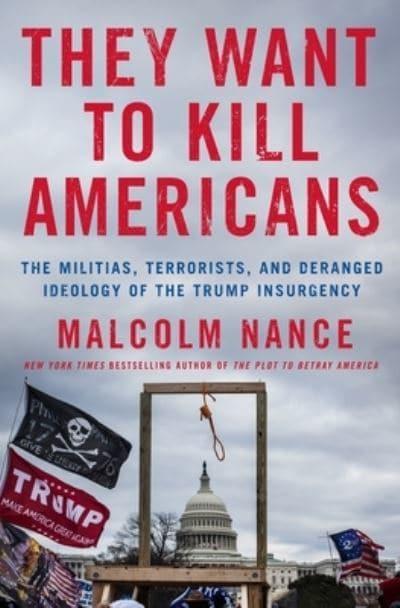
They Want to Kill Americans
(Added subsequently). There’s a third and even scarier book that I only began to read the day this blog initially was published. They Want to Kill Americans by Malcolm Nance, describes Trump’s brownshirts and the ongoing assault on American democracies by Americans. Here’s a link to Goodreads’ entry on it. And here’s a Kirkus review.
Jonathan Chevreau is Chief Financial Officer of the Financial Independence Hub, author of the financial novel, Findependence Day, co-author of the non-fiction Victory Lap Retirement, and columnist and Investing Editor at Large for MoneySense.ca.
“the financial press has gone on a feeding frenzy in response, serving up heaping helpings of negativity upon negativity.”
Everyone loves a Perma-Bear
Whether by traditional channels or social media streams, amplifying extreme news is in large part what the popular financial press does.
They’re not entirely to blame; we consumers tend to gobble it up with a spoon. That’s thanks to a behavioural bias known as loss aversion, which causes the average investor to dislike losing money approximately twice as much as they enjoy gaining it. Our “fight or flight” instincts basically prime us remain on constant high-alert when it comes to protecting our life’s savings.
Media outlets know that, and routinely round up a stable of talking heads to scratch that behavioural itch. Their “regulars” even earn catchy nicknames:
Perma-bear
Back in 2012, economist David Rosenberg put together a presentation called 51 Signs the Economy Is a Total Disaster. (What, only 51?) We know that reality begged to differ. He tried again in 2019, when he declared: “We’re going into a recession … I think it will be this coming year.” It didn’t happen.
Dr. Doom
Whenever the press needs a fresh Armageddon forecast, they know they can call on “Dr. Doom” economist Nouriel Roubini. It doesn’t seem to matter that he’s been mostly wrong far more often than not. As recently as early July, Roubini was predicting a 50% freefall in the stock market. So far, not so much (thankfully).
“The tweets that get shared and liked the most are the ones that fit with how we feel the most … Twitter is an enormous mirror.”
If you look closer, you might spot a card hiding up these soothsayers’ sleeves: with a large, random group of “experts” loudly predicting doom and gloom nearly all the time, basic statistics informs us: a few of them are going to be right every so often, with seemingly uncanny accuracy. Their fortuitous timing makes them look super smart, which earns them even more fame. The cycle continues.
Going on a Financial Media Diet
On many fronts, times are indeed disheartening, and we’re as worn out as you are by the weight of the world. That said, there are already way too many outlets cramming worst-case scenarios down our throats and crushing investment resolve. To offset a bitter pill overdose, following are a few more nutritious news sources to reinforce why we remain confident that capital markets will continue to prevail over time, and that long-term investors should just stick to their plan.
Stock Markets Grow
The following chart is one of our favorites, as it shows at a glance that which the bad news bears routinely disregard: Stock markets have gone up nicely, and far more frequently than they’ve gone down. We have no reason to believe current trends are going to alter this uplifting, nearly century-long reality.¹ Continue Reading…
Thinking about buying a home? As of late 2021, there were 646,053 active home listings, according to Rocket Mortgage. More homes are likely to come on the market in spring and summer, which are hot selling seasons. Investing in a home purchase can afford buyers an asset that, ideally, should maintain or, hopefully, increase in value. Some buyers simply want a place to hang their hat and call their own. Whether you’re raising a family, need space for your dogs, or are ready to tackle the responsibilities of maintaining a house, you can rely on this guide to provide you with the essential information you need to know before you buy one.
Are you ready to buy a House?
Buying a house is a big commitment — living in a specific location, paying a mortgage for decades, and maintaining a property (in order to preserve its value). Many people either aren’t ready to settle down into a home of their own or simply prefer to rent, leaving property maintenance to property owners. You’re likely ready to buy if you:
Are annoyed or tired of renting: typically, renting involves loads of rules stipulated by landlords, annual rent increases, and a lack of privacy (mainly if you live in an apartment complex).
Want to invest in real estate: investing in real estate is a common reason why people buy houses. Unlike rent, which is gone once you pay it, your mortgage payments are applied to the home’s purchase. In typical cases, you’ll retain that money in the form of your asset or recoup it when you sell the house.
Have a family and want more room: if you have a family, you may wish to purchase a home that offers space for each member of your household as well as a backyard that provides outdoor living space.
Pre-purchase Considerations
Before buying a house, there are various factors to consider before you sign on the dotted line of a purchase contract. A home tends to be a long-term investment. To make the most of it, it’s essential to understand the challenges associated with the buying process and the obligations related to property ownership. By exploring the personal and financial areas of your life, you can arrive at the right decision for you.
Personal Considerations
Ask yourself if you are ready to commit to living in a specific area. A mortgage is generally a 30-year commitment (unless you choose to sell the property). What are your plans for the future? Do you expect to relocate soon for your job? Do you wish to have children or to expand your family? These considerations may impact your decision to buy as well as the type of home to buy.
Remember, everything regarding the care of the home will rest on you: and your partner if you are purchasing together. Not only is there the monthly mortgage to cover, but there are also the inevitable home maintenance and repair costs that come into the bargain. In short, understand the financial obligation before you as you contemplate your decision.
Financial Considerations
There are other financial factors to reflect upon too. To qualify for a mortgage, you will need a good credit score as well as a down payment. As banks consider your loan request, they will examine your debt. Do you have existing debt, and is it enough to impede your home buying plan? Also, banks will evaluate whether your income is enough to pay the monthly mortgage payment. Look closely at your financial picture because, rest assured, any lender you choose will definitely examine your finances closely.
The Psychology of Buying a Home
You might not realize it, but engaging in the home buying process can be an emotional roller coaster. It’s easy to get your hopes up that a seller will accept your bid. You might fall in love with the perfect house only to realize that the seller accepted another buyer’s bid. You might also find a home with great potential only to find that it has severe flaws like a cracked foundation. It’s important to keep your emotions in check to make a sound investment decision.
There are other psychological aspects of buying a house that you might not have thought about before. For instance, some people bring cultural superstitions to the process and don’t want to live in a house with specific numbers in the address or are opposed to a particular street name.
Other people might struggle with the perceived value of a home, believing that interior wall colors will substantially affect its worth. The reality is that cosmetic changes are easy and often inexpensive to fix in cases like this.
If you find yourself contending with psychological factors like these, take a step back and think them through. If they’re going to impede your long-time enjoyment of the home, you may want to keep house hunting. If, however, you think you can spend a decade of your life on “Elm Street,” you may be glad that you didn’t allow a horror movie from the 1980s to sabotage the purchase of your dream home.
Searching for a Home
Speaking of needs, you’ll need to consider them closely so that you can confine your search to homes that satisfy them. Before you begin your house hunting adventure, you should consider:
House size: how much square footage will suit you/your household?
House exterior: what architectural styles appeal to you? Bungalow, cape cod, modern?
Bedrooms: what’s the minimum number of bedrooms you need?
Bathrooms: how many bathrooms do you prefer your home to have?
Heating and cooling systems: how efficient are these systems? Will they need to be replaced soon after you buy the house?
Basement: do you want a home with a basement or cellar?
Attic: do you want to purchase a home with a finished attic that offers usable living space?
Garage: how much space do you want your garage to have?
How to Choose the Right Neighborhood
The neighborhood of your home is also an important consideration. A great home in a community that you don’t find agreeable can make for an unhappy situation. When you choose a neighborhood to shop for a home, you should consider:
Safety: investigate the area’s crime rates, affecting property values.
Community services: do you require public transportation? Do you want to live near shopping centers, medical facilities, or parks?
Public schools: be sure to assess the quality of area schools if you have school-age children.
Amenities: what are some local amenities in the area? Is there a local swimming pool, forest preserves, entertainment venues like theaters? What about restaurants?
Top Home Buying mistakes
Many buyers have stumbled into pitfalls when shopping for and buying a house. Try to learn from their mistakes. Here are some of the most common home-buying mistakes to watch out for:
Partnering with a real estate agent who doesn’t “get” your needs and preferences.
Failing to get pre-approved for a mortgage.
Making an offer on the first house you visit.
Getting only one rate quote from one lender instead of shopping for a more competitive lender.
Buying a house that is more than you can afford.
Using all of your savings as a down payment.
Not investigating the HOA if the area has one.
Failing to look into first-time homebuyer programs.
Not researching the community extensively.
Waiving a home inspection.
Special terms for New Home buyers
Is this your first time buying a house? In that case, you’ll undoubtedly want to find out about first-time homebuyer programs and special incentives that can alleviate some of the financial stress associated with buying a home. You may also qualify for programs based on your income or veteran status. An experienced real estate agent will be able to inform you about any programs or incentives that you might qualify for. As a first-time homebuyer, some of the special terms you may be eligible for include: Continue Reading…


 Posted By

 Posted By