Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

12 creative ways to earn money Post Retirement

What is one creative way to earn money post-retirement? 

To help retirees find creative ways to earn money, we asked business consultants and entrepreneurs this question for their best tips. From offering peer-to-peer storage to substitute teaching, there are several creative ways that may help you earn money and stay active post-retirement.

Here are 12 creative ways to earn money post retirement: 

  • Peer-to-Peer Storage
  • Lease a Car On Turo
  • Become a Movie Extra
  • Get a Part-time Audio Transcription Job
  • Freelance Writing
  • Consider Airbnb
  • Rent Out Property
  • Try Driving
  • Affiliate Marketing 
  • Blogging
  • Become a Consultant 
  • Become a Substitute Teacher

Peer-to-Peer Storage

During retirement, many folks seek out sources of passive income like renting, yet often want to avoid the responsibilities and potential problems associated with landlordship. Peer-to-peer storage is a creative compromise. Instead of renting out living space, owners can rent out storage space, such as garages, spare rooms, and closets. These arrangements tend to be easier to end if necessary than tenancies, and involve much less interaction with renters. Retirees are likely to have some extra space in their houses, and putting these rooms to work is a great way to generate extra revenue. — Michael Alexis, TeamBuilding

Lease a Car on Turo

Services like Turo allow customers to borrow someone else’s car for a set period of time. Why not lease out your car to them? Yes, if you’ve got a car, or multiple cars, then you’re ready to become a car-sharing entrepreneur. Some people can earn $10,000 or more by sharing their cars on Turo. The more cars you offer, the more you can earn! — Brian Greenberg, Insurist

Become a Movie Extra

Although it is usually not a very profitable venture, it can become a lifestyle for many. Playing a small part or a background role in TV or cinema productions can be very enjoyable and allow to meet interesting people and even see famous actors. After establishing relationships with casting agencies, it is relatively easy to find some gigs regularly. That’s especially the case for productions recorded during working hours when most professionals are busy with their 9-5s. — Michael Sena, SENACEA

Get a Part-time Audio Transcription Job

Audio transcription is the process of typing out recorded audio, such as podcasts, business meetings, and qualitative research interviews. Transcription agencies regularly hire typists to work 100% remotely as independent contractors. The work is often flexible and can be done on your own schedule. When applying for a transcription job, you’ll usually required to complete an aptitude test that involves transcribing some sample audio. — Chloe Brittain, Opal Transcription Services

Freelance Writing

A great backup plan or extra income is freelance writing. There are so many writing opportunities and contracts for part-time work or a side hustle. Fiverr is an easy place to find extra writing work on the side, you can create your own profile and upload previous work for companies to find and hire you. Plus, you can work from home with freelance writing. — Michael Jankie, Natural Patch

Consider Airbnb

If you have an extra room or an extra property you only make use of seasonally, you may want to consider listing it on Airbnb. Hotels are often too expensive or inconvenient for some travelers, making Airbnb an attractive alternative. You can be as involved in running your Airbnb as you want, or take a largely hands-off approach to making money post-retirement. — Lily Yu, Oak Springs Realty

Rent out Property

One popular option for retirees and senior citizens with extra space or multiple properties is to rent out their spare rooms and suites to people looking for short-term housing options. This can be especially beneficial if you own a vacation property that you only use sparingly but would like to earn an extra income. Many websites allow people to find renters quickly, so take some time to research which ones are best suited to your needs. — Chris Thompson, Backdoor Survival

Uber or Lyft Driving

The best Uber and Lyft drivers I’ve encountered have been retirees. They’re working because they want to, not because they have to. They’re upbeat, conversational, and usually know the geography of the area like the back of their hand.

If you’re retired and don’t like sitting around the house all day, why not carve out a few hours of your afternoon giving people a lift (no pun intended)? If you live in proximity to the airport, most of your customers will be people from out of town that you will enjoy conversing with. It’s an easy way for retirees to earn extra spending money and passengers generally enjoy their company. — Jon Carder, Vessel Health

Affiliate Marketing

Affiliate marketing is one of the most effective strategies to boost retirement income. Once set up, it will continue to generate income pretty much without any intervention. And there lies the appeal, it can be completely passive or operated with just a few hours a week and the help of a virtual assistant, or a younger family member. Continue Reading…
How to correct a Business Deficit

Image via Pexels

By Jim McKinley

Special to the Financial Independence Hub

You want your business to succeed and generate a profit; however, an unexpected expense or change in the economic climate can lead to a deficit.

In fact, an estimated 70% of small businesses have outstanding debt, and businesses in Toronto, Canada, are no exception. While it may cause you to worry about your business’s future, you can proactively take steps to get your business out of debt.

Small Business Grants

Search for grants for small businesses, which provide money you won’t need to repay. The process of finding the right grant, especially one that you qualify for, may seem tedious, but you can find them.

Before beginning the grant application process, you should have created a business plan. Make sure it includes a detailed description of your business with clear objectives. You can use this plan to show you’re serious about your business. Besides applying for grants, you can use your plan to intrigue prospective investors.

As you’re searching for grants, look for ones specific to your business type. Some examples of grants for Canadians include the Amber Grant and Cartier Women’s Initiative Award.

After finding grants that you qualify for, you’ll need to complete an application that highlights the business’s best attributes and usually include your comprehensive business plan.

Small Business Loans

If you’re merely going through a hard time at the moment, consider a small business loan. In most cases, lenders only extend these loans to companies that have been in business for at least two years.

You’ll also need to have a decent credit score to qualify. Additionally, the lender will want to see your personal and business income taxes as well as income and balance statements. The lender may also ask to see your business plan.

Carefully analyze your Budget

Know your company’s finances. Review where your major spending is and determine if you could reduce or eliminate any of it. Continue Reading…

Risk Management: A Four-Letter Word?

By Noah Solomon

Special to the Financial Independence Hub

Since the global financial crisis of 2008, markets have for the most part been a one-way train. Even the precipitous decline of the Covid-crash of early 2020 was erased so quickly that several months later it seemed like little more than a bad dream.

In such a favourable and long-lasting environment, risk management has increasingly become regarded as a four-letter word. Any attempt to mitigate risk and protect investors from large losses has been a money losing proposition. It has been a drag on returns and has done little to reduce volatility. Simply stated, risk management isn’t of much use when there has been no risk to manage.

Defining a Bubble: Like Catching Water in a Net

There is no universally accepted definition of a bubble. Identifying one is part art and part science and can only be done with certainty in hindsight once a bubble has become a matter of record.

Parabolic gains in markets in and of themselves may or may not signal a bubble. Similarly, situations where valuations stand significantly higher than their long-term historical averages cannot be conclusively classified as bubbles.

Further complicating matters, bubbles tend to be accompanied (if not caused) by a broad-based mindset among investors, which by definition is difficult, if not impossible to measure or define.

Behavioral Characteristics of Bubbles: Zero Fear & Speculative Frenzy

One of the most common and powerful characteristics of bubbles is a widespread belief that stocks can only go up. Aided and abetted by historical precedent, many investors have become emboldened by growing faith in a perpetual Fed “put,” whereby the central bank will move aggressively to support (and even reverse) any significant decline in markets.

Relatedly, this complacency has led to a surge in speculative madness during which a growing number of investors have piled into riskier assets, causing parabolic gains. One does not have to look far to see several signs of such behaviour, including:

  • Meme stock madness: GameStop and AMC, two companies in declining industries which respectively rocketed up 120x and 38x from their post-pandemic lows to their 2021 highs.
  • Crypto craziness: Dogecoin, which was originally conceived as a parody, went up nearly 300x to a market cap of $90 billion, spurred by tweets from Elon Musk.
  • Electric vehicle ecstasy: Hertz’s stock surged by simply announcing that it would purchase a fleet of Teslas. Similarly, Avis tripled in a day based on the mere suggestion that it might follow suit!

The Daunting and Consistent Math of Bubbles: It’s A Long Way Down

In the world of statistics, a 2 sigma event refers to something that occurs only 5% of the time. Using this framework, a market that is 2 sigmas above its long-term trend can be considered to be in bubble territory (or at the very least quite frothy). Using the same logic, a market that stands at 2 sigmas below its long-term trajectory can be thought of as mouth-wateringly cheap (or at least as somewhat of a bargain).

Founded in 1977, Boston-based Grantham Mayo Van Otterloo (GMO) is an investment management firm with roughly $75 billion in assets under management. It is well-known for its strong track record of asset allocation. The firm successfully identified and navigated both the tech bubble of the late 1990s and the real estate/financial bubble of 2006-7.

GMO analyzed the available data over financial history across all asset classes and identified more than 300 2 sigma observations. In developed equity markets, every single one of these observations over the past 100 years has fully deflated with prices falling back to their long-term trends. This pattern strongly suggests that:

  1. The higher markets go, the lower their expected future returns.
  2. The higher markets go, the longer and greater pain investors will have to endure to get back to trend.

Importantly, if you think that the recent decline in stock prices presents a golden opportunity to scoop up cheap assets, the fact that the S&P 500 currently stands about 40% above its long-term trend should be cause for sober second thought. This prospective downside is corroborated by Warren Buffett’s favourite valuation gauge, otherwise known as the Buffett Indicator, which is the ratio of the total value of the U.S. stock market to GDP. The indicator currently stands at 193%, which is approximately 50% above its historical average.

Make Mine a Triple

Using the 2 sigma definition of a bubble, in early 2021 it looked as if we might have a standard bubble. However, as the year progressed, the 2 sigma deviation progressed into an even rarer 3 sigma anomaly, which comes with an associated increase in potential pain.

Adding to concerns, real estate assets have arguably joined the bubble-party in stocks. Houses in the U.S. stand at the highest multiple of family incomes ever: even ahead of levels that prevailed prior to the housing bubble of 2006-2007. Alarmingly, this lofty multiple is lower than the corresponding level in other countries (Australia, the UK, China, and our very own Canada). Continue Reading…

Get started on your investing journey

RBC/Getty Images

By Michael Walker,

Vice-President & Head, Mutual Funds Distribution & RBC Financial Planning, RBC

 (Sponsor Content)

Whether you’re investing to build up a nest egg for retirement, to buy your first home or for a special vacation, finding the right investing solutions can play a big role in helping you achieve your financial goals.

If you’re just starting on your investing journey, however, I know that taking that first step can feel overwhelming.

To help get you started, I’ve responded below to four of the most common questions I hear about investing:

  • Do I have enough money to get started?

You don’t need to have a lot of money to start investing. It’s important to start early, however, as even small amounts of money can grow into big investments with the power of compounding.

As a simple way to think of this, compounding enables your investment to generate earnings and then those earnings are reinvested. In other words, compounding helps you grow earnings on your earnings.

The basic idea is to start investing with an amount you’re comfortable with and increase that amount over time. Once you’ve decided how much you can invest, consider setting up an auto-deposit that automatically moves that money from your chequing account into your investment account on a regular basis. This could be weekly, bi-weekly, monthly: whatever works for you and your finances. Then, as your available funds increase, you can increase the amount you deposit.

In this way, you’re benefiting from paying yourself first and the money you’re depositing will be in your investment account before you can even miss it.  

  • How do I decide which investing options are right for me?

Finding the right investing solutions starts with understanding your investing style. Here are some questions you can ask yourself, to help determine that style:

  • Why do I want to invest? How does this fit into my overall financial goals?
  • Do I want to make my own investing decisions and do I have the time to manage my own investments?
  • Am I comfortable with virtual investing, knowing there are professionals managing my investments in the background?
  • Do I want advice and support from an advisor, and if so, how much?
  • Do I want to combine doing some investing on my own with working with an advisor?  

Once you understand your investing style it will be much easier to determine the investing options that suit you best. Continue Reading…

New Harvest Monthly Income ETF aims to beat inflation by combining 5 different “Best Ideas”

Canadian retirees and would-be retirees who feel starved of high monthly income and are pressed by surging inflation may find relief in a unique new “Best Ideas” fund-of-funds Income ETF that began trading on Feb. 16th.

Harvest Portfolios Group Inc. announced on Wednesday the completion of the initial offering of Class A Units of the Harvest Diversified Monthly Income ETF, which is now trading under the ticker symbol HDIF [TSX.]

In a press release, Harvest president and CEO Michael Kovacs said the new ETF targets a high initial annual yield of 8.5% by accessing “five proven Harvest Equity Income ETFs efficiently in one single ETF.”  In a backgrounder  on its website, Harvest noted the inflation-busting 8.5% compares to a 4.5% Canadian inflation rate that ended 2021, and to the TSX’s 2.6% annual yield and S&P500’s 1.5%.

As outlined in a prospectus filed Feb. 4th with all provincial securities regulatory authorities in all Canadian provinces and territories, the innovative new ETF brings together five different Harvest “Best Ideas” in generating income, and is designed to provide Canadian investors access to a core diversified monthly income solution.

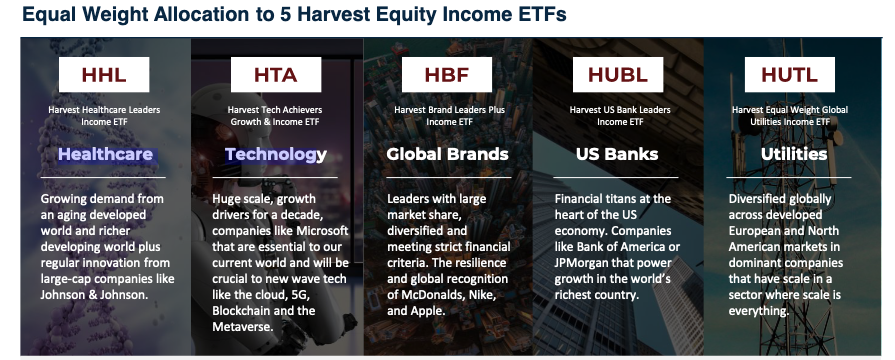
The portfolio is comprised of more than 90 large global companies diversified across these 5 equally weighted sectors: Healthcare, Technology, Global Brands, Utilities, and US Banks. The five underlying ETFs are illustrated below: There is no additional management fee apart from the MERs of the underlying Harvest ETFs. Because it’s a new fund and because of the leverage component, there is not yet an estimate of what the final MER might be. But it should be  in the ballpark of some blend of the MERs of the underlying funds: Referring to the tickers below, here are the Management Fees and MERs of the component Harvest ETFs, as of June 30, 2021:

HHL 0.85%/0.99%

HTA 0.85%/0.99%

HBF 0.75%/0.96%

HUBL 0.75%/0.99%

HUTL 0.50%/0.79%


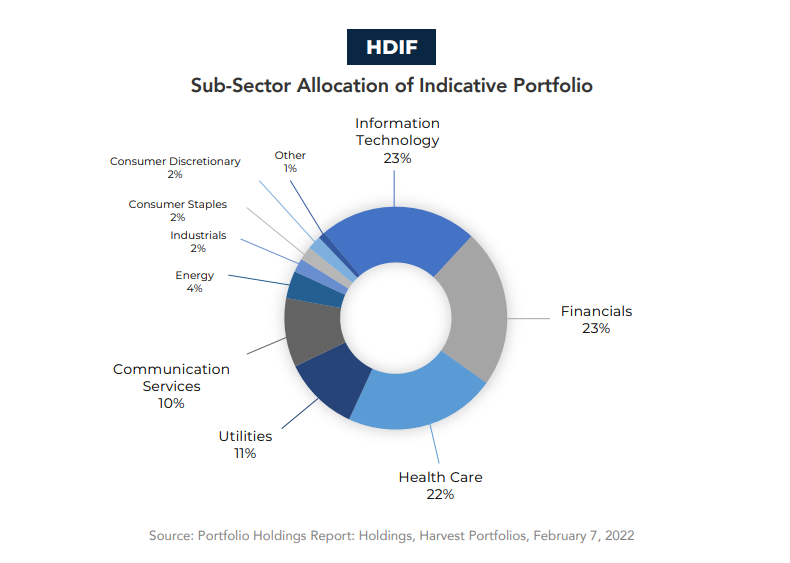
The net result is a collection of global stocks that are allocated in the following sectors (a comparable geographical breakout is not yet available):


In addition to high monthly cash distributions the fund provides the opportunity for capital appreciation by investing, on a levered basis, in a portfolio of ETFs that engage in covered call strategies.  Harvest says the maximum aggregate exposure of the ETF to cash borrowing will not generally exceed approximately 33% of the ETF’s net asset value.

For additional information, visit www.harvestportfolios.com