Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

3 tips to House Flipping success for Seniors


By Jim McKinley

Special to the Financial Independence Hub

If you’ve been looking forward to trying something new in retirement, flipping houses might be the ticket. If you want to be a successful house flipper, follow these steps from Financial Independence Hub to get your business off on the right foot.

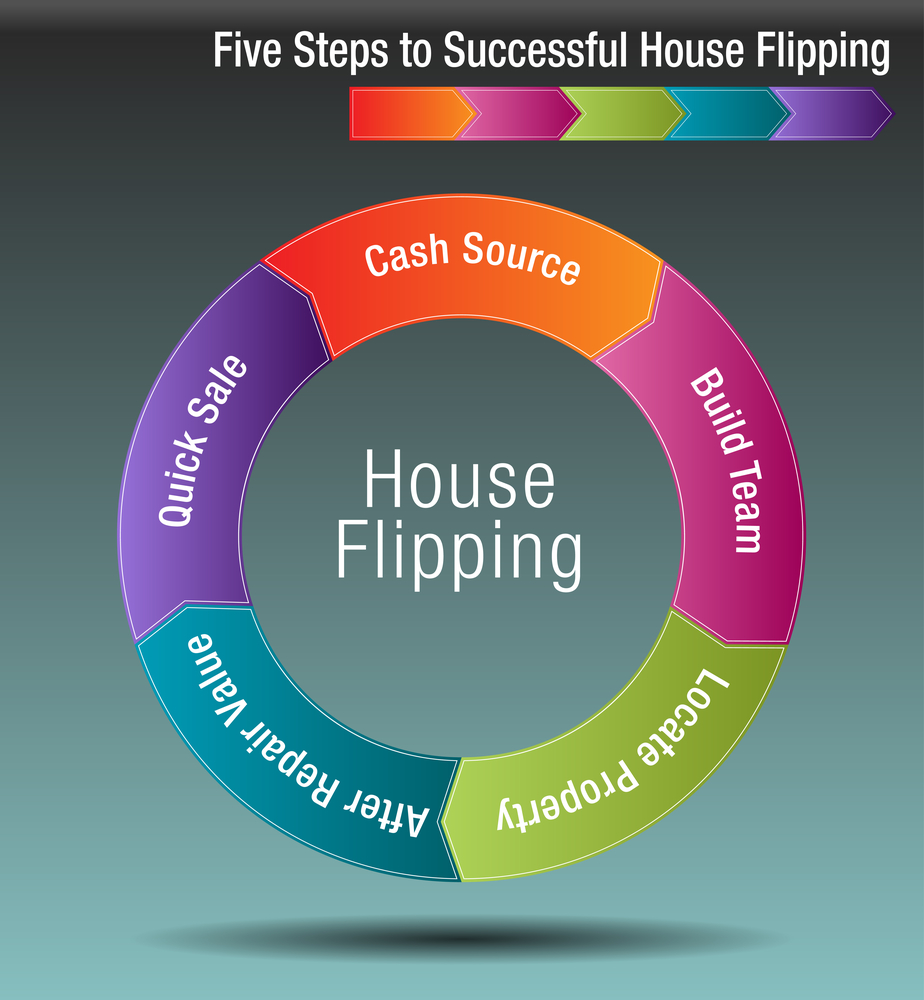
1.) Figure out Funding

Funding for house flipping generally comes from two places: investors or hard money loans. Each way has its benefits and drawbacks.

Investors can be a great option because you are bringing someone into the business who wants it to succeed. The money investors give you can also be used more freely than funds from a loan. Auctions, for instance, are an excellent place to pick up homes for cheap, but they often require cash. Most loans won’t cover auction purchases, so investors are an excellent way to open up the world of foreclosed auction homes for you.

The downside to investors is that because they also have an investment in the business, you might have less freedom than you would if you were on your own. Their opinions become as weighty as yours, and you may have to bend to their will when your opinions differ on what to do because they have the money.

Hard money loans are another option for business financing. Instead of basing their approval on you, lenders consider the potential value of the house after repair, called the ARV. If approved, they’ll give you not just the purchase money for the house but what you’ll need to flip it, too, and if the loan goes south, they can get their money back by selling the property. The main drawback to these loans is steep interest.

2.) Know what to look for

The ideal house for flipping is located in an up-and-coming neighborhood, meaning young families and professionals are looking to buy there. It’s located on a good street with low crime and is near nice schools.

According to HGTV, the best houses have areas that can be improved immensely simply by painting. They have solid builds with an attractive layout and unique pieces that give them character. Although it can be tempting to choose homes that could use extreme renovations, those kinds of fixes can take significant time. It’s important to remember that every month you spend working on the house is time that you’re losing money through your loan or paying bills to keep the house up and running. Continue Reading…

Tax rates likely to rise: what to do about it


By Eva Khabas

Special to the Financial Independence Hub 

The Covid pandemic has led to unprecedented government spending with a deficit that has reached record heights.

Sooner or later someone has to pay for this and that usually means the taxpayer. Don’t look now but when you start your tax planning it’s probably best to assume that tax rates are going up in Canada.

However, even before Covid the federal government was talking about increasing the capital gains tax.

Capital gains inclusion rate could go back up to 75%

Currently, only 50% of capital gains are, in fact, taxable but this was not always the case. In fact, from 1990 to 1999 75% of capital gains were subject to tax! It’s logical to assume that tax revenues will be increased through a higher capital gains portion that is taxable, since capital gains are perceived as ‘passive’ income from investments. In theory, this means taxes should be generated by wealthier taxpayers.

Loss of Principal Residence exemption?

Also, the big fear of every Canadian is that government will remove the principal-residency exemption. Currently, taxpayers can sell their primary residence at a gain and not pay any taxes.  Many taxpayers rely on the appreciation in value of their homes as their main source of retirement income. The impact of making gains on principal residency taxable would be devastating to many, if not most, Canadians.

Before discussing what to do about all this, let’s make sure we understand what capital gains are, how they are different from your other income, and when these gains become taxable.

So, what exactly is capital gain? In a nutshell it’s the growth in the value of an asset being held for investment purposes, so that asset is not for resale. A long-term holding period would indicate that the gain is capital. Currently, only half of the capital gain is taxable, while most other income is fully taxed.

In most cases the capital gain is subject to tax when the asset is sold, but there are also times when you may have to report capital gains without an actual sale occurring. For example, at the time of death there is the deemed or assumed sale of all assets, with any capital gains included in the tax return of the deceased. This would, of course, affect beneficiaries.

It’s important to note that increases in personal tax rates will also result in you paying more tax on capital gains. This is because the tax rate on capital gains is applied at the same tax rates in Canada as on employment and other income. In addition, reporting a higher overall total income would also result in more tax because a higher income puts you in the top tax bracket.

Defence # 1: Timing

So, now we see that many tax-reducing strategies primarily revolve around two things – 1) timing, and 2) reducing your taxable income. First, let’s look at timing.

If you have higher overall income from various sources in 2021, and expect lower taxable income for 2022, consider disposing of the asset(s) in 2022 wherever possible so the gain attracts a lower marginal tax rate for you.

You can also use time to advantage by deferring the cash outflow – the tax you pay to the government – and disposing the assets early in the year. Your tax bill is due April 30th of the following year, so if you sell the capital asset in January of 2022 you still have 15 months until tax must be paid on that.

Staggering gains over multiple years

Now, let’s assume you have a large capital gain. How can you stagger that gain over several years? One strategy is to defer cash receipts from the sale over multiple years. The Canadian Income Tax Act allows you to spread that gain over five years (and in some cases over ten years), provided you receive proceeds from the sale over a number of years. For example, if you receive 20% of the proceeds in 2021, you only need to include 20% of the gain in your taxable income as it can be spread over five years.

RRSPs and TFSAs

All these strategies are of a short-term nature. If the assets are disposed of in the long term, consider holding them inside your RRSP. You don’t have to declare those assets as income until you make a withdrawal. Likewise, you can use your TFSA so some of the gains are not subject to tax at all. Either way, your tax advisor can help determine if assets can be transferred to your RRSP or TFSA. Continue Reading…

8 Small Business investing options


What is one investment option that a small business should consider? Why?

To help your small business take on different investment options, we asked financial experts and small business leaders this question for their best investment ideas. From consulting a tax expert to getting into stocks and shares, there are several smart investment tips that may help your small business.

Here are eight investment options that small businesses should consider:

  • Learn About Objectives & Preferences
  • Consult an International Tax Expert
  • Invest in Your People
  • Help Fund Your Home Base
  • Find Companies That Improve Lives
  • Build Wealth with Index Funds
  • Think About Retirement Early
  • Get into Stocks and Shares

Learn About Objectives & Preferences

As any sound advisor will say, the best investment options for a small business truly are based on a personal situation. Some small businesses want more flexibility and control with their savings. Others are looking for less risk and fees. Before looking at investment options, small business owners should learn about their objectives and preferences. Then, they can see how investment options like life insurance or annuities can improve their financial position by safely growing their money while protecting it from tax and market risks. —Chris Abrams, Marcan Insurance

Consult an International Tax Expert

Investment options depend on a small business owner’s situation. Small business owners located overseas must understand that tax laws can differ considerably from country to country and impact their assets, financial accounts, and investments. That’s why consulting with an international tax attorney on issues like cross-border tax structuring, and compliance needs to be a part of the process. Investments aren’t just about the return; they’re also about the tax ramifications and savings by making the right choices. — Jason Kovan, International Tax Attorney

Invest in your People

Some of the most successful businesses tend to have a people-first mentality. An investment in people, whether that is putting in the time to make your customers happy or providing the resources necessary for happier employees, is an investment in your business’ success. If your customers are happy, they will recommend your business to their family and friends. If your employees are happy, they will be more willing to invest their time and efforts into the company’s goals and vision for the long term. — Brianna Vaughan, LendThrive

Help fund your Home Base

Invest in municipal bonds to help fund and develop your home base where most of your customers are located. These types of bonds offer a way to build interest while preserving your capital. They also have some tax benefits. Many municipal bonds are exempt from federal income tax as well as state and local taxes. — Rronniba Pemberton, Markitors

Find companies that Improve Lives

Investing in tech companies and products like ours helps to advance the industry and improve our daily lives. Predictive text and real-time spelling correction capabilities help to open doors for more opportunities not only for your business, but also your customers and employees who struggle with text. It also helps to improve overall productivity to maximize daily efforts. Continue Reading…

Wake up excited about your Future with these Financial Planning strategies

LowrieFinancial.com

By Steve Lowrie, CFA

Special to the Financial Independence Hub

When people ask me what I do for a living, I sometimes say financial planning. Or investment advice. Or, “I’m a personal financial advisor.”
But none of these descriptors is spot on. As my website says, what I really do is help people wake up excited about life, not worried about money. A key element to this higher calling is to deploy the secrets of simple investing.

Simple investing sounds like a good idea, right? It’s important whether you’re mid-career and all-business, or you’re approaching retirement, with leisure time on your mind. It applies whether you live in bustling Toronto, my hometown of Barrie, or anywhere else in the world. It’s also a familiar theme on my blog, from “Why simplicity beats complexity,” to “Simple investing isn’t easy,” to “Simple Investing Strategies to Take Away from 2018.”

Still, the secrets of simple investing never grow old and always bear repeating, lest we forget: Your long-term financial goals should drive your financial planning strategies, which should guide your investment portfolio … not the other way around. Or, even more succinctly:

Investment Success = Goals + Planning + Building & Maintaining

This basic equation explains why trend-hungry traders chasing after the latest SPACs, NFTs, etc. are going about it all wrong.

Today, let’s unpack this wise, but simple investing advice.

Simple Investing Step 1: Setting Goals

For most of us, the ability to wake up excited about life, not worried about money means having satisfying goals ahead, and realistic plans for achieving them. No wonder a significant part of what I do as a personal financial advisor is to walk people through the emotional and financial elements of goal-setting.

To achieve your personal short- and long-term financial goals, first, you must have them. And yet, I often see busy families rushing right past this critical first step.

I see it when I ask a 50-something couple about their retirement goals. As each partner shares their ideas, differences often emerge. One may be imagining action-packed days, filled with family gatherings and community service. The other might be dreaming of downsizing to a peaceful country cottage and enjoying more quiet time. Who knew?

I see it in younger families too, as they wrestle with life’s tradeoffs: kids, careers, friends, personal interests, neighborhood organizations, soccer league … How do you do it all without going crazy, broke, or both?

I’ve also seen how the pandemic has put many families’ once-solid long term financial goals into a tailspin, creating a challenge and opportunity to revisit their assumptions. Now what?

Fortunately, the steps to setting long term financial goals successfully are simple enough:

Define and Describe: First, take the time to record your current goals. Go beyond “I want to be rich and famous,” to large and small, near- and long-term specifics. Chances are, you’ll have more goals than time and money to achieve them all. So, estimate the costs involved, assign priorities, and establish approximate timelines for each:

When we retire in 2028, we would like to buy a family cottage near Georgian Bay. But most of all, we’d like to spend more time with the grandkids.

I would like to finish my master’s degree next year. Either way, I really want to be self-employed with my own business by 2025.

Communicate: Talk about your goals as a couple, to discover common ground as well as where you may differ. Identify where and how you might need to find good compromises.

Maintain: Life changes. You change. Periodically revisit your goals and adjust them as needed.

Simple Investing Step 2: Making Plans

With your short- and long- term financial goals in sight, you’re better positioned to wake up enthused about life’s possibilities. The next step is to reduce the worrying. That’s where planning comes in. Clearly, life doesn’t always go as expected! But we must plan anyway, because …

Your plans become your most dependable touchstones against which to adjust your course as needed.

Robust financial planning should embody your personal goals and financial realities. As a personal financial advisor, my aim is to tend to both, so my clients can:

  • Live comfortably, but within their means, by spending less than they make today
  • Invest what they don’t spend today wisely, to fund tomorrow’s dreams
  • Protect what they’ve achieved so far, by insuring against the great unknowns

Admittedly financial planning can be gnarly. Unless you’re a personal financial advisor too, you probably don’t wake up feeling excited about the chance to balance your budget, invest your reserves, select sensible insurance coverage, and figure out how to draw on your reserves once you retire.

In the spirit of simplicity, let’s revisit the point of these tasks:

Financial planning helps you make the most of your money today AND tomorrow.

In other words, by having personalized, practical plans in place, it becomes much easier to know where you stand today, whether you’re on track for tomorrow, and whether you’re as ready as you can be for whatever might happen along the way.

Which brings me to my final simple investing step:

You don’t just need a financial plan. You need ongoing financial planning.

Simple Investing Step 3: Building and Maintaining

Here’s a simple truth: Whether you manage your own money, or you have a personal financial advisor to assist you, a lot can happen between “now” and “then.”

In Your Life: Relationships, careers, interests, and ambitions evolve. Financial windfalls may propel you forward; emergency spending might set you back. Even if you’ve carefully prepared for a big event like retirement, it may not be quite what you imagined once it arrives.

In the Market: Over time, you can expect to build significant wealth by participating in a market’s long-term growth. But in ever-volatile financial markets, you never know what’s going to happen next, or whether the next few months or years will delight or disappoint.

In the World: You don’t need me to inform you that the world never stops spinning. From Toronto to Beijing, for better and worse, breaking news from near and far can wreak havoc on even the most ironclad plans you’ve made for you and your family. Continue Reading…


Invesco Canada launches two new Thematic Technology ETFs focused on Nasdaq

After the huge success of Cathie Woods and the ARK ETFs in 2020, rival investment managers have been quick to characterize technology funds as “Innovation” or “Disruption” products.

Such was the case on Thursday,  as Invesco Canada Ltd.  announced the launch of two new exchange-traded funds (ETFs) offering Canadian investors exposure to several relevant technology themes. This follows the February announcement from Franklin Templeton of the Franklin Innovation Fund (FINO), which appeared on the Hub under the headline Invest in Innovation, a Driver of Wealth Creation.

Both the words “Innovative” and “Disruptive” appear in the top of the press release for the debut of the Invesco NASDAQ Next Gen 100 Index ETF (QQJR and QQJR.F) and the Invesco NASDAQ 100 Equal Weight Index ETF (QQEQ and QQEQ.F. As the release says, these funds “build on the innovative solutions offered by Invesco and Nasdaq, allowing clients several distinctive entry points to own the disruptive companies listed on The Nasdaq Stock Market.”

Invesco also announced the launch of CAD Units of Invesco NASDAQ 100 Index ETF (QQC).

The Invesco innovation suite was launched in October 2020 and is just now expanding to Canada, with  the following TSX-listed ETFs that started trading on the TSX today (Thursday, May 27). Of the three below, I find the equal weight Nasdaq 100 offering the most interesting:

  • Invesco NASDAQ Next Gen 100 Index ETF (QQJR and QQJR.F)
  • Invesco NASDAQ 100 Equal Weight Index ETF (QQEQ and QQEQ.F).
  • Invesco NASDAQ 100 Index ETF (QQC and QQC.F)
Pat Chiefalo

The innovation play was also highlighted in the following quote attributed to Pat Chiefalo, Head of Canada, Invesco ETFs & Indexed Strategies: “The launch of two new Invesco Nasdaq ETFs reaffirms the commitment of Invesco’s Canadian ETF business to providing our clients with products that access the themes and companies at the forefront of innovation … Now Canadian investors can choose several unique ways to gain exposure to the category-defining companies listed on The Nasdaq Stock Market.”

There are of course several existing rival plays on the top 100 Nasdaq companies apart from Invesco’s famous QQQs. Incidentally, Invesco says it recently changed the name of the Invesco QQQ Index ETF to the Invesco NASDAQ 100 Index ETF, dropping the management fee to 0.20% of NAV to “make it the most cost-effective ETF in Canada tracking the Nasdaq 100 Index.”

By contrast, the new QQJR and QQJR.F are relatively unique: it tracks the Nasdaq Next Generation 100 Index, which includes the “next 100” non-financial companies listed on The Nasdaq Stock Market, outside of the Nasdaq 100 Index, in a mid-cap ETF. Continue Reading…