Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Equal Weight Indexing during Economic Recovery


By Hussein Rashid, Invesco Canada

Special to the Financial Independence Hub

2020 was a year for the history books: especially from a finance perspective. With COVID-19 ripping throughout the globe, we saw equity markets decline rapidly as several countries closed their borders.

At the same time, however, we saw some companies flourish as people spent more time at home. Companies like Apple, Microsoft, and Google1 shined brightly and became larger than ever before. Central banks globally introduced measures that aided this appreciation by reducing rates to record lows, fueling most growth-oriented stocks upward at a rapid pace.

However, over three months into 2021, we are now seeing signs of recovery towards normalcy, with continued supportive measures by many central banks and governments, along with a growing number of people being vaccinated.

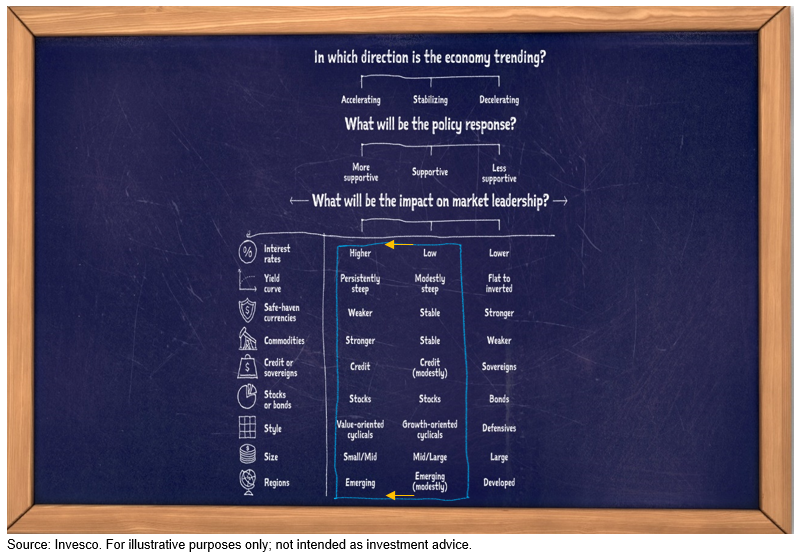
So, what does that look like from a market leadership perspective? As the recovery unfolds and economic activity accelerates, we would expect market leadership to align with that of the left column of the chart above.

We have already seen a steepening yield curve with longer-dated bond rates rising:  this could temper the strong run up in growth-oriented stocks. Near the end of last year, the move from growth stocks to more value-oriented cyclical stocks, and the move from large-cap stocks to small/mid-cap stocks started to occur. Many of these stocks, especially names in the S&P 500®, will tend to benefit more from the economy and society reopening. Continue Reading…
Projected Inflation and investment returns

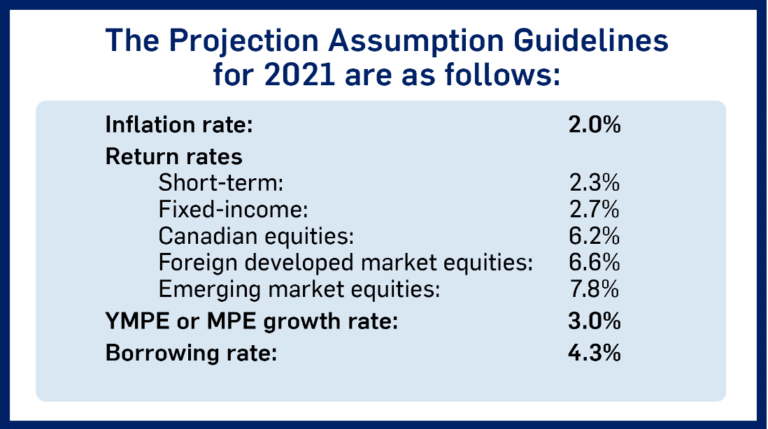
FP Canada issues guidelines every year to help financial planners make long-term financial projections for their clients that are objective and unbiased. The guidelines include assumptions to use for projected inflation and investment returns, wage growth, and borrowing rates. It also includes “probability of survival” tables that show the life expectancy at various ages.

The 2021 Projection Assumption Guidelines were of particular interest because, well, a lot has happened since the 2020 guidelines were published last spring. How should we project inflation and investment returns as we get to the other side of the pandemic and economies start opening up again?

Will we see sustained higher inflation? Should we expect any returns at all from bonds or cash? Should we lower our expectations for future stock market returns?

Remember, these are long-term projections (10+ years). That’s very different than guessing the direction of the stock market for 2021, or predicting whether we’ll see a short burst of inflation in late 2021, early 2022.

The inflation assumption of 2.0% was made by combining the assumptions from the following sources (each weighted at 25%):

  • the average of the inflation assumptions for 30 years (2019 to 2048) used in the most recent QPP actuarial report
  • the average of the inflation assumptions for 30 years (2019 to 2048) used in the most recent CPP actuarial report
  • results of the 2020 FP Canada/IQPF survey. The reduced average was used where the highest and lowest value were removed
  • current Bank of Canada target inflation rate

The result of this calculation is rounded to the nearest 0.10%

Projections for equity returns were set by combining assumptions from the following sources:

  • the average of the assumptions for 30 years (2019 to 2048) used in the most recent QPP actuarial report
  • the average of the assumptions for 30 years (2019 to 2048) used in the most recent CPP actuarial report
  • results of the 2020 FP Canada/IQPF survey. The reduced average was used where the highest and lowest value were removed
  • historic returns over the 50 years ending the previous December 31st (adjusted for inflation).

Equity return assumptions do not include fees.

Unlikely that bonds can replicate their projections of last 50 years

Projections for short-term investments and Canadian fixed-income returns included the assumptions from QPP and CPP, the results of the 2020 FP Canada/IQPF survey, but the 50-year historical average rate was removed in 2020 as a data source. This makes sense given that interest rates were significantly higher than they are now and so it would be impossible for bonds to replicate the performance of the last 50 years. Continue Reading…

The Bubble blowing contest

Wellington-altus.ca/standupadvisors

By John De Goey, CFP, CIM

Special to the Financial Independence Hub

One element of Bullshift that I cannot help but notice is how the finance business has selective and self-serving definitions and explanations that abound when explaining the business to the public.

We’ve already discussed how a 10% move downward is called a “correction”,  but there is no term for a 10% move upward.  Is that an “incorrection”?  Who decides what is correct or not, anyway?

The related term that I often find a bit amusing is the word “bubble.”  Before reading further, take a moment to reflect on what you believe the word means when used in an economic context.  Have you got it?  Don’t read further until you have a firm definition and / or example of ‘bubble’ in your mind.

According to Wikipedia:

An economic bubble or asset bubble (sometimes also referred to as a speculative bubble, a market bubble, a price bubble, a financial bubble, a speculative mania, or a balloon) is a situation in which asset prices appear to be based on implausible or inconsistent views about the future.

Advisors usually acknowledge bubbles after they burst

In my experience, advisors generally only acknowledge bubbles after they burst.  Here’s a fictional story to illustrate that conditional acknowledgement.  Let’s pretend a pair of 12-year-old boys are in the world championships of bubblegum blowing.  The one with the biggest bubble wins, provided the bubble is generally accepted by judges without bursting first.

Three esteemed economists have been hired as judges in the contest. The boys get their gum, chew it and begin to blow their bubbles.  In short order, the bubbles become remarkably large.  Unbelievably large.  And identical in size …. there’s nothing to choose between them!  The judges can’t decide which of the bubbles is bigger … and yet they get bigger still.  Eventually, one of the identical bubbles bursts and the kid with the unburst bubble holds his position for a couple of seconds for the judges to acknowledge that his remains intact: and then inhales the gum back into his mouth, thinking he has won. Continue Reading…

The Dividend Aristocrats fight back


By Dale Roberts, cutthecrapinvesting

Special to the Financial Independence Hub

The Dividend Aristocrats are S&P 500 companies that have increased their dividends each year, for at least 25 years running. That is an exclusive group. Companies that have increased their dividends for 50 years or more are dividend royalty – they are dividend kings. The Aristocrats have underperformed over the last year and more. You won’t find an Apple, or Amazon or Alphabet (Google) or Tesla in that index. That made it more than difficult to keep up with the market. But those high quality Aristocrats are fighting back as value takes over from growth in 2021. With few dramatic high flyers, that might be its greatest strength in 2021 and beyond.

There is a US listed ETF for the dividend aristocrats ProShares NOBL. Here’s an overview from their landing page.

Here’s my previous post on the US and Canadian Dividend Aristocrats.

Rising dividends and equal weight magic

The Dividend Aristocrats offer a very simple one-two punch. We have that meaningful dividend growth history and the equal weighting of the index constituents. That compensates for a few of the key weaknesses of the S&P 500 cap weighted index. That is the most replicated index on earth, of course. A cap weighted index will follow the momentum of the market as more investors flow into the most popular stocks.

That can create a bubble based on enthusiasm over fundamentals.

Yes, you’ll find those cap weighted ETFs at work in the ETF Portfolio page. The methodology can work wonderfully until it doesn’t, such as in the dot-com crash of the early 2000’s. US stock markets and Canadian stock markets were crushed thanks largely to the over concentration in very popular tech stocks. Most of the US tech stocks had no earnings or very poor earnings. Of course, Canada went over the ledge thanks to Nortel. You can throw in the odd JDS Uniphase and a few other names as well.

You have a choice

None of the those tech stocks would have qualified as a dividend aristocrat in the year 1999 or 2000. The index side stepped much of the carnage. The dividend aristocrats greatly outperformed the S&P 500 through the dot-com crash and well beyond. It is an investment approach that beats the market with less volatility.

The first column is year, then Aristocrats, S&P 500, and then differential.

Incredibly, we see the Aristocrats offer positive returns in 2000 and 2001 while the cap weighted S&P 500 is two years into its three year venture of delivering negative returns. That began the lost decade for US stocks.

Are we about to enter another lost decade?

Many or most market commentators will offer that US stocks are in a bubble, again. The PE ratios, CAPE ratio and Buffett indicator all place today’s US stock market in dot-com crash territory. Continue Reading…

How to raise money-smart kids

Shutterstock

By Gaurav Kapoor, Founder, Mydoh

(Sponsor content)

Financial literacy isn’t an innate skill. Like most skills in life, financial literacy must be learned – the problem is who teaches it? Parents know they play a part, but they may lack the confidence, or the knowledge.

Helping your children develop good money habits as they enter their teen years is a great place to start their financial literacy journey. Teenagers are eagerly seeking out financial independence and may be earning money through an allowance or an after-school job.

As they look to spend their hard-earned money, it’s crucial to set them up for success. After all, money isn’t just about dollars and cents, it’s about the choices we make with it. Parents want to teach their children to be money-smart – to have skills to earn, budget and spend, but they also want to share the value, emotions and experiences that come with money.

This notion of early financial literacy is what motivated me to create Mydoh, the Smart Card for kids.

Check out my best tips below for raising money-smart kids with the help of Mydoh:

Leverage technology that helps your kids learn how to save, and spend, their money

Kids today are more tuned in to technology than ever before – so why not use tech to teach them financial literacy?

Mydoh is a Smart Card for kids that comes with a money management mobile app, available on iOS and coming soon to Android. Kids gain financial skills by earning money through tasks and an allowance (set up by their parents) and by making their own purchases (wherever Visa is accepted) using their Smart Card issued by RBC through the app, with a physical card coming soon. This gives kids the autonomy, competency, and confidence to make their own earning and spending decisions – learning values that help build a strong foundation for the future.

Through the app, kids can manage their own money in the real world, making decisions to spend and earn, while parents get visibility to their spending and can have better money conversations. Continue Reading…