If you’ve been reading this web site since its launch five weeks ago, you’ll know that Findependence, or Financial Independence, is quite a bit different than the traditional “full-stop” retirement depicted in many advertisements from the financial industry.
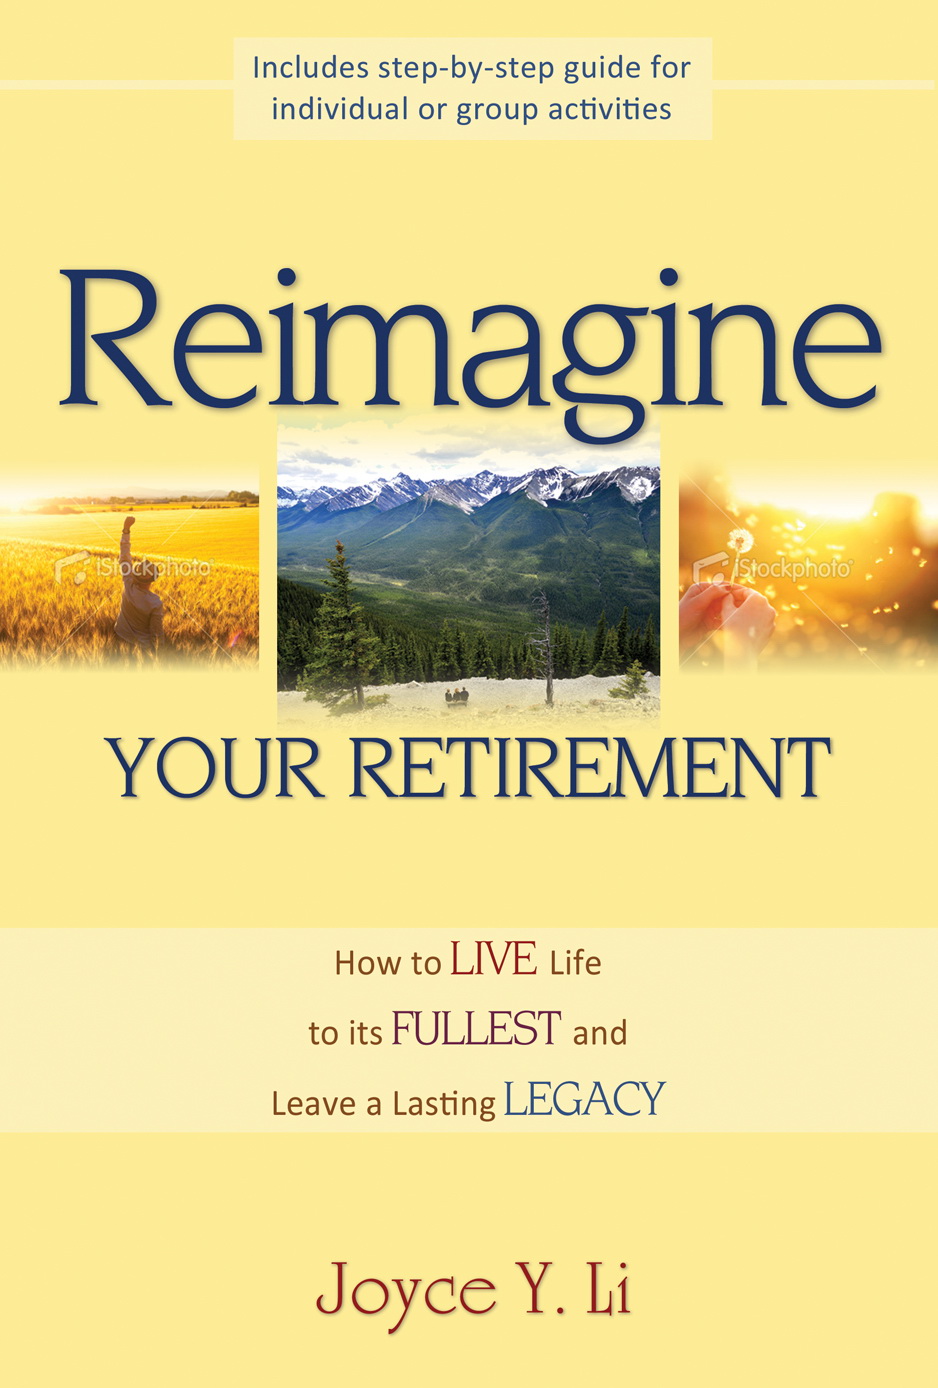
I like the perspective of the author of the book pictured to the right, who “reimagines” retirement to be a sort of spiritual/vocational half-way house between the decades of full-time work and career and the “eternity” that awaits us all at the end of life’s journey.
Joyce Li is a project manager and motivational speaker, originally from Hong Kong, now living with her family in Brampton, Ont.
Many consider defined benefit pension plans the gold standard of retirement plans. Through the ups and downs of the markets, defined benefit (DB) pension plans remain the one thing that employees can count on in their golden years. DB plans offer employees some much-needed stability in retirement. For those without the luxury of an employer-provided pension plan, the alternative is RRSPs. With RRSPs, you contribute throughout your career and hope that your investments perform well enough so you can enjoy a comfortable lifestyle in retirement.
Defined Benefit Plans Disappearing
While workplace DB plans used to be widespread in the private sector, they’ve been disappearing at an alarming rate over the last couple of decades. Now only a third of employees have any kind of pension plan at work, let alone a DB pension plan. The dot com bubble in 2001 and the financial crisis in 2007 only sped up the pace at which employers are looking to “de-risk.” De-risking comes in many forms, but the most prevalent is switching from a DB plan to a defined contribution (DC) plan or group RRSP.
Defined Benefits vs. Defined Contribution
With a DB plan the employer bears most of the investment risk. If investments underperform, it’s up to the employer to make up any shortfall. However, with a DC plan or group RRSP, employees bear the brunt of the risk. If their investments don’t pan out, they’ll have to make tough decisions like scaling back their lifestyle in retirement or working longer (if they’re physically able to).
Having worked as a pension analyst at a global pension and benefits consulting firm for nearly five years, I have a unique perspective on what’s been unfolding in the realm of pensions. I’ve watched as pension plans on which I work have closed DB pension plans to new entrants, forcing new hires to enroll in DC plans. Although I still have a DB plan at work, even my own plan has been scaled back in recent years.
How do DB Plans Fit into My Findependence?
That brings me to the main point of this article: are DB plans part of my own Findependent plans, or I am so much into self-employment and Internet businesses that I feel they’re okay for really conservative members of my generation, but perhaps not for myself? Despite working as a financial journalist to supplement my income, I still see DB plans as an integral part of my Findependent plans.
Even though I don’t plan to retire until at least age 55, it’s still nice to know I have a guaranteed DB plan waiting for me when I do decide to call it a career. A DB plan will provide a large chunk of my money in retirement. Because of that, I’ve been able to invest more heavily in equities in my RRSPs.
I’m a big fan of the Canadian Couch Potato investment philosophy. I chose the TD e-Series funds because of their great track record and low fees. I’m invested heavily in equities – I have 30% invested evenly in Canadian, U.S. and International equities, with only 10% in bonds. I wouldn’t have been able to take this position without a rock-solid DB plan waiting for me.
What About Everyone Else?
If you’re a younger worker in an industry where you plan to change jobs every few years, a DB plan probably doesn’t make much sense. But if you’re someone like me who’s willing to spend their entire career at a company once they find a job they love, a DB plan can be a great way to build up your retirement income as a reward for your years of service.
Some people refer to DB pension plans as pyramid schemes without getting the facts straight. For the most part your company pension plan is safe. Workers in Ontario have added protection – up to $1,000 of your monthly protection is guaranteed by the government.
Would I ever consider trading in my DB plan? Not a chance. I see my DB plan as an important part of my journey towards Findependence. I know I can count on it when it matters most.
Sean Cooper is a Personal Finance Expert and Financial Journalist. He is a first-time homebuyer and landlord who aspires to reach findependence by age 31. Follow him on Twitter @SeanCooperWrite and read his blogs and request his writing services on his website: http://www.seancooperwriter.com/
Overspending is a common problem for many people; it creates debt, anxiety and relationship problems, even among high income earners. All too often, people’s spending habits seem to rise to meet – and exceed – their incomes.
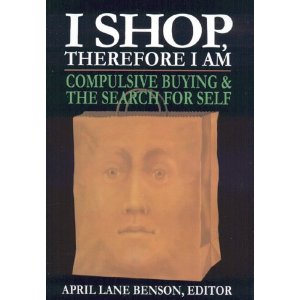
So why does this happen? What compels people to overspend when they already have the items they truly need? The answer lies deep within each person’s spending personality. Recently, I read Dr. April Benson’s book I Shop Therefore I Am, and was fascinated by what the contributing authors uncover about the emotional and psychological factors influencing our buying habits.
I thought it would interesting, and beneficial, to touch on the six key spending personalities they explore: image spenders, bargain hunters, collectors, compulsive shoppers, co-dependent spenders (a.k.a. gift-givers) and bulimic spenders. Continue Reading…
Based on a survey released this year by the TransAmerica Center for Retirement Studies, it appears that the majority of Millennials and Gen Xers believe Social Security will no longer exist by the time they are ready to retire. It’s time to set the record straight about what Americans can realistically expect from Social Security in the coming decades and what they can do to secure their own financial future.
The Truth about Social Security
The truth is Social Security is in need of a fix. Social Security trustees believe the program will still be financially solvent through to 2019. However, if no changes are introduced by 2033, the trust fund will be exhausted. Based on the latest Social Security Trustees’ report, money generated from current payroll taxes at that point are estimated to be enough to support only 77% of promised benefits until the year 2088.
Changes to the Social Security program are required at a congressional level and with the current stalemate in Congress over other political agendas, Social Security has apparently taken a backseat. Congress hasn’t passed any significant ratification to the program since the last reform of 1983.
A public opinion poll sponsored by Voice of the People in February 2014 suggests Americans are willing to make some tough concessions. A representative majority of the public supports measures such as raising the payroll tax rate and the annual cap on income, reducing benefits for top income earners and increasing the full retirement age to 68 or more.
Count Social Security as a Bonus
It’s important to note Social Security was never intended to serve as a full pension but rather as a supplemental retirement and disability insurance program. The reality is that many Americans rely solely on Social Security payments during the course of their retirement years. Suffice it to say, extreme financial hardships along with poor financial planning are often cited as reasons why some retirees end up with little to no personal savings and investments.
Even though many Americans overwhelmingly disapprove of any potential cuts to Social Security, according to recent Gallop polls, over 69% of those surveyed don’t expect to rely heavily or at all on Social Security payments. These findings mirror my own view in that my plans and calculations for achieving financial independence do not consider Social Security payouts as part of the equation.
As taxpayers, Americans have the right to expect their fair share from Social Security during their golden years but considering that the average Social Security monthly payment is $1,192.21, this amount is likely far from being enough for the vast majority.
Achieve Financial Independence without Social Security
Whether the intent is to leave the workforce earlier than 55 or continue to work well into your golden years for the sheer joy of it, focusing on achieving financial independence is truly a wise option. By saving and investing as much as possible, ideally well above the suggested rate of 10% to 15% of earned income, keeping consumer debt out of the picture while paying off any mortgage debt, spending consciously and living frugally, financial independence is well within reach.
In striving for financial freedom, your future and financial security will never be limited by how much Social Security can afford to pay you. In the event Social Security reforms are enacted and in place by the time you’re eligible to file, you could easily decide to defer filing your claim until 70 years of age, in order to reap even higher benefits.
As the saying goes “Never keep all your [financial] eggs in one basket.”
Kassandra Dasent is a freelance writer, business consultant, wife and step-mom. She is the founder of More Than Just Money, where she discusses a variety of topics and personal experiences that intersect with money. Her articles have been featured on several sites, including US News & World Report, The Globe & Mail and Brighter Life.
Dealing with Longevity Risk is a “hot topic,” according to someone who’s an expert on the topic. Read this “as told to” interview with Moshe Milevsky, the prolific financial author and finance professor at the Schulich School of Business.
The risk is that as people go from savers (Wealth Accumulation) to relying on retirement income (Decumulation), there’s always the danger of running out of money before you run out of life.
There is of course a solution called annuities but for some reason both investors and their advisors aren’t yet flocking to them. This may be because it involves losing control over your capital to an insurance company and is an irrevocable decision, at least for the portion of your capital being annuitized. Another reason is it often means that capital won’t be available to one’s heirs, depending on the options chosen.
Interest rates low, but mortality credits on annuities become important as you age
Even so, Milevsky tells the site that “single premium income annuities are often under-rated as a retirement planning tool.” Yes, interest rates are low but Milevsky argues that as you get older, mortality credits become relatively more important. In the end, it’s all about peace of mind.
In any case, no one ever said you have to annuitize ALL your capital. Read Milevsky’s piece and you may conclude that at least some of your capital might be annuitized at some point.
 Posted By
 By Jonathan Chevreau