Tag Archives: Financial Independence

Merely leaving the nest does NOT constitute true Financial Independence

Depositphotos_13980277_xs
Is the little birdie kicked out of the nest truly “Findependent?”

My latest MoneySense blog posted today carries the curious headline that most Millennials expect to achieve “financial independence” by age 27. I put “air quotes” around the phrase financial independence because of course it’s nonsense that merely leaving the nest and putting fewer demands on the Bank of Mum and Dad constitutes true financial independence.

Keep in mind that the research firm cited in the piece seems to use quite a different definition of Financial Independence than the one used at this site or as formally defined at Wikipedia. For research firm yconic, it seems financial independence means merely leaving the nest and landing a job that pays at least the monthly rent: they are merely “financially independent” of mum and dad.

Even with that loose definition, only 56% of older millennials (aged 30 to 33) say they have “achieved financial independence.”

With these savings rates, true Findependence for many millennials is a pipe dream

It’s just as well they’re using such a loose definition because the way the younger generation spends, it’s going to be a long long time before they achieve the kind of financial independence this blog describes.

To sum up the difference, I’d say “our kind” of Financial Independence is being able to stay afloat financially without the traditional source of single income known as “a job” or full-time employment. It’s quite a leap to go from moving out of the parental nest to being able to survive with neither parents nor an employer to keep those regular financial injections flowing into your bank account.

Far from being findependent, almost half the millennials surveyed (46%) admitted “saving money is a struggle” even if they are able to afford to pay the bills. A third say they are living paycheque to paycheque and are barely making ends meet. Fully 43% still rely on their parents for financial assistance, including 37% who look for help paying their student loans off. Does that sound like “our” kind of financial independence?

Non-saving millennials should find a Government job with a DB pension and stay there

I hate to break it to the non-savers but if they don’t start saving soon, they’ll never be able to achieve true financial independence. They had better be prepared to work until age 67 and be able to live on Social Security (in the US) or on the Canada Pension Plan, Old Age Security and possibly the Guaranteed Income Supplement (GIS), or find a good Defined Benefit pension plan somewhere and hang on to the job for three or four decades. (may as well try the Government first: their DB plans are most likely indexed to inflation and ultimately backstopped by taxpayers).

If there’s hope for them, it’s in the finding that most millennials hope to buy a home at some point. I like that because I always say the foundation of financial independence (our kind, that is) is a paid-for home. But even among those who already own a home, 32% got parental help rustling up the down payment. Among those who don’t, a quarter of them (24%) expect their parents to help them with the down payment.

Some millennials do have their act together

I don’t mean to disparage millennials’ aspirations for Financial Independence altogether. Read elsewhere on this site how two millennials aim to be mortgage and debt free in their early 30s. Both of them know all about frugality, saving and deferring instant gratification. Of course they both read the book featured on our sister site!

I also suggest reading a guest blog posted on this site earlier this week on why millennials should be planning NOT for retirement, but for Financial Independence. The true kind, that is!

Some book suggestions
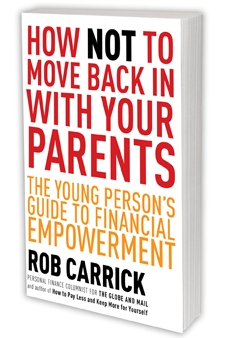
rob_carrickparents12Parents who have yet to kick the little birdies out of the nest might consider giving them a hint about what true Financial Independence entails by investing US$2.99 or C$3.37 in either of these e-books featured elsewhere on this site. Might make a great stocking stuffer! (Just gift the e-book via Amazon and maybe insert in the stocking a card telling them to check their Kindle).

I also suggest that millennials or their parents get a copy of Rob Carrick’s book, How Not to Move Back In With Your Parents.

As we speak, my own daughter is reading it.
Why Millennials should plan for Financial Independence, NOT retirement!

alan_moore
Alan Moore, XY Planning Network

 By Alan Moore

Special to the Financial Independence Hub

Two major issues make the concept of retirement planning difficult to grasp for many members of Generation Y. This group, also known as the millennials, ranges in age from the young twenties to the mid thirties. At this age, they have anywhere from 30 to 40 years (or more) of a working career ahead of them.

That makes the concept of retirement pretty abstract. It’s difficult to envision something more years into the future than years you’ve been alive!

The other issue that complicates matters is the fact the average American is living longer than ever before. Gen Y isn’t likely to retire at 63 and expire a decade later. Their retirement savings will likely need to last more than 20 or 30 years if they don’t want to outlive their nest eggs.

These two factors – the fact that retirement is decades in the future, and the fact that retirement itself may last decades – makes it hard for Gen Yers to get excited about the concept of retirement planning. It’s overwhelming to think of putting away your hard-earned money today for a time in life you can’t even imagine, and it’s overwhelming when you think of the lump sum of money you’d need to save to rely on for more than 30 years in your old age.

Making the Shift from Retirement Planning to the Idea of Financial Independence

The idea of a “retirement” wasn’t originally designed for what millennials will likely face in the future. The economy, job market, and corporate culture has changed (read: no more pensions, no more life-time job with a single company). It’s unlikely that younger generations will reach a certain age and simply stop working – and reasons why they shouldn’t keep piling up.

It seems that avoiding work that leaves you unfulfilled or stressed, and taking occasional breaks from hard work, is rewarding and good for us. But putting a complete stop to work? That leads to boredom and other problems for retirees.

Ultimately, research suggests we need to have purpose at all stages of life. So instead of putting the focus on retiring from work at some distant, fuzzy point in the future and being inactive until our lives come to an end, we need to focus on building a great life right now while making progress toward financial independence.

What Is Financial Independence, and Why Is It Better for Gen Y?

Financial independence means developing enough income to pay all expenses indefinitely, without needing to work full-time to bring in that money.

Why is the concept of financial independence something easier for Gen Y to grasp than the concept of retirement? Because it completely changes the goal and makes it much more realistic and attainable.

You’ve probably heard of the 4% rule, which says that you can take 4% out of an account on an ongoing basis. According to this, a nest egg of $1,000,000 will produce around $40,000 per year. The flip side is by creating an income stream of $3,333/month, it is equivalent to having saved one million dollars! For many people, it’s much easier to create a passive income stream of a few thousand dollars per month than it is to save up a lump sum of a million dollars.

And for most people who are financially independent, they use this freedom from an obligatory job to pursue (paying) work they feel passionately about. So they don’t feel the need to just stop working, and view financial independence as an opportunity to pursue activities they enjoy without having to stress about the amount of money they generate.

How You Can Get Started Now

In addition to what you save and invest from your full-time job, you can get started on financial independence by creating additional income streams on the side. The goal is to make these streams as passive as possible, to create cash flow that funds your freedom.

It’s important to start now because very few streams of income are 100% passive – and almost none are passive when you begin to establish them. To get you going, consider these ideas that you could take to build a small stream of passive income:


  • Real estate: When you’re ready to move out of your starter home, don’t sell the property. Rent it out and let it become an income source for you instead. Note that this path is not for everyone; being a landlord can be tough and expensive if you want to go 100% passive (by hiring a management company to handle your tenants for you).
  • Building a side business: Your own business can become passive with time – but it takes a tremendous amount of work to grow it to that point. So start now! Create a side hustle or side business that you can work on and grow in your free time. This generates more income for you to invest now, and can provide an income stream in the future when you’re ready to scale back on your working hours.
  • Monetize a hobby: You can always take something you already enjoy and monetize it. If you work with something tangible (like creating art or other products), start selling what you make. If your hobby is something like an activity you do (think running or golfing), share your expertise and start teaching others.
  • Leverage your current assets: Wisely investing your current assets is another way to create passive income (via dividends, for example). This is another path that won’t be for everyone, but it is an option that’s available.

There’s no limit to what kind of small income streams you can create, especially if you’re willing to work hard and establish them now. Financial independence is within reach, and much more so than any fuzzy concepts about a far-off retirement that sees you generating zero income, forcing you to live off a massive amount that you had to first save.

So forget about trying to plan for retirement. Work to reach financial independence instead. You’ll get there sooner and have more fun doing it.

XYPlanningAlan Moore, MS, CFP® is the co-founder of the XY Planning Network and president of Serenity Financial Consulting, a fee-only RIA and location-independent financial planning firm. He is passionate about helping financial planners start and grow their own fee-only firms to serve Gen X & Gen Y clients largely ignored by traditional firms. Alan has been recognized by Investment News as a top “40 Under 40″ in financial planning, and by Wealth Management as one of “The 10 to Watch in 2015.”  He frequently speaks on topics related to technology, marketing, and business coaching, and has been quoted in publications including The Wall Street Journal, Forbes and The New York Times. He lives in Bozeman, MT so he can hit the slopes on powder days.

Extreme Early Retirement? I call it Extreme Early Findependence!

Savings Thermometer Measuring Money Nestegg IncreaseBy Jonathan Chevreau

MoneySense.ca today is running my column on Extreme Early Retirement from the November issue. It looks at the phenomenon championed by super-frugal savers like Mr. Money Moustache and Jacob Lund Fisker of so-called Extreme Early Retirement.

The idea is to be self-sufficient, do without, live in a small home, eliminate frivolous purchases like cars or furniture and save like crazy for five or ten years: and we’re not talking the typical savings rates of 10 or 15% of a paycheque: more like 50% or more.

Frugality to a Fault?

Continue Reading…

The Women’s Guide to Financial Independence

Female hand holding up the number 5Hub Staff

From Sarah Ban and Michael Gordon at TheSimpleDollar.com, a well-researched and fact-based guide specifically for women. This 5-step post is designed to help women arm themselves with the information that many of them may not have, to help them secure their own financial futures free from outside influence (spouses, parents etc).  The steps are as follows:

Step 1: Understand Your Cash Flow

Or: make sure you know where your money is coming from, and going to. The article suggests using financial app Mint to keep track of your expenses. Click the above link to complete a specifically tailored exercise to find out your monthly cash flow.

Step 2: Determine Your Goals and Set Your Budget

Whether it be paying off your various debts or saving to buy your first home, figure out what your goals are and how long it should take to achieve them. The article also has some handy tips to help you cut those costs, many of which are discussed here as well!

Step 3: Eradicate Debt

Remember to prioritize your debt. Paying down that high-interest credit card should take precedence over your low-interest student loan debts.

Step 4: Save!

Packed with more staggering statistics about American women’s financial education, step 4 dives into what women really need to do to prepare themselves for retirement including opting in to your company’s 401 (k) plan. There is also vital information on American healthcare costs, emergency savings, housing and car savings, and different savings vehicles to help you get the most from your hard-earned money.

Step 5: Protect Yourself 

After following steps 1-4, you will no doubt be financially secure and confident, however there are always unforeseen circumstances that come out of left field, and it is important to be aware of those circumstances and have a plan in place to help you stay afloat in even the worst of times. By nurturing your credit score, staying on top of housing, and being aware of your marital status’ possibility to change, your ability to adapt to changing financial situations will be greatly strengthened.

Click through for a much more in-depth guide that covers just about everything American women need to know to make themselves Findependent.

The 1,000 buck-a-month rule: You can retire sooner than you think

wesmoss
wesmoss.com

By Jonathan Chevreau

Here’s a blog I wrote for MoneySense.ca before the Hub launched, housed in what it now terms the MoneySense Findependence Archives. It seemed to resonate so I’ve repurposed it here, adding the cover shot of the book from which it’s drawn: You Can Retire Sooner Than You Think.

It deals with an interesting rule of thumb that most retirees and would-be retirees would do well to adopt. Developed by U.S. financial planner Wes Moss, it’s called the 1,000-Bucks-a-Month Rule. It means that for every thousand dollars in monthly income you want in retirement, you need to have saved $240,000. Continue Reading…