Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Buying Stocks without a Broker: Here’s how to pick the best investments on your own

A growing number of  Investors like buying Stocks without a Broker because they’re able to  avoid possible Conflicts of Interest and Save on Broker Fees. However, it’s especially important to know what to Buy if you’re not using a Broker

Many investors assume their broker is honest and has their best interests at heart; if this proves to be untrue, they will shop for better stock trading advice from a new broker. Of course, many investors decide on buying stocks without a broker. That can be a successful strategy if you choose the best options for your investment temperament—using our Successful Investor approach.

Buying stocks without a broker: Why it might be a smart move for some investors

As any good stock broker or experienced investor can tell you, bad brokers are all too common. By “bad brokers,” we mean those who put their own interests above that of their clients. Keep in mind, however, that most bad brokers do this in a perfectly legal fashion, by catering to their clients’ whims and weaknesses.

Here are three main practices that bad stock brokers often practice:

  • Aiming for stability rather than growth
  • Double dipping
  • Stressing low-risk, low-return, high-fee structured products in client accounts

Additionally, you may have noticed that your broker sometimes uses unfamiliar words and phrases to describe investment concepts. Some of this stock broker jargon is simply shorthand that brokers use among themselves, to refer to familiar situations without having to go into any detail on the underlying concept. However, the concepts that these “broker-ese” words and phrases represent also serve to further the goals of the brokerage business.

If you find yourself thinking in broker-ese, you’ll naturally make assumptions that are in tune with the goals of your broker. They may be out of tune with yours.

Here’s one example: from time to time, your broker may advise you to sell a particular stock you own because it represents “dead money.” This doesn’t mean there’s anything wrong with the stock, or the company. Instead, your broker simply thinks the stock may only go sideways for a period of months or longer, producing no capital gains for you. So they naturally feel you should sell it and buy something with better short-term capital-gains potential. Continue Reading…

An Income Strategy for Adjusting to Uncertain Markets

Franklin Templeton/Adobe Stock image

By Franklin Templeton Canada

(Sponsor Content)

Canadians face a lot of headwinds in this volatile investing year, including high inflation, rising interest rates, slower economic activity and geopolitical shocks. In this turbulent environment, an actively managed income strategy can help steer the way through uncertainty. Volatile markets call for a strategy that can adjust client portfolios in a timely, tactical way as market conditions shift.

Active investment management can play a key role in offering a compelling risk-reward option for investors who are looking for income, growth and overall portfolio diversification. The strategy that underlies the Franklin U.S. Monthly Income Fund is an example of an approach to seeks to give investors stability amid volatility.

“The fund has a portfolio that can make adjustments in a timely manner on your behalf,” said Rob Rocoff, Vice President, Regional Sales with Franklin Templeton Canada in Toronto. “It’s a fund that uses a flexible, balanced strategy that is capital structure agnostic and has a track record in the U.S. of over 70 years of being able to tactically adjust to volatile market conditions.”

The Franklin U.S. Monthly Income strategy aims to generate income by investing in stocks, bonds and hybrid securities, such as equity-linked notes (hybrid securities have characteristics of both stocks and bonds). The strategy’s flexible asset allocation allows it to adjust across different market cycles, including moments of high pressure, to find the most attractive investment opportunities.

The Franklin U.S. Monthly Income strategy looks throughout the capital structure for securities that offer attractive income and long-term growth potential. Top-down insights inform the investment team’s view on asset allocation, while the security selection process is driven by rigorous bottom-up fundamental research. The team focuses on investment opportunities where their fundamental views may differ from the market consensus, especially with investments in large companies.

Seeking Yield from multiple sources

As a result, the fund’s portfolio includes equities (common or preferred stocks), fixed income assets (e.g., investment grade bonds, Treasuries) or hybrids (e.g., equity-linked notes and convertibles). This mix seeks yield from multiple sources and allows for dynamic asset allocation, depending on market conditions. Continue Reading…

How to take advantage of rising interest rates

By Bob Lai, Tawcan

Special to the Findependence Hub

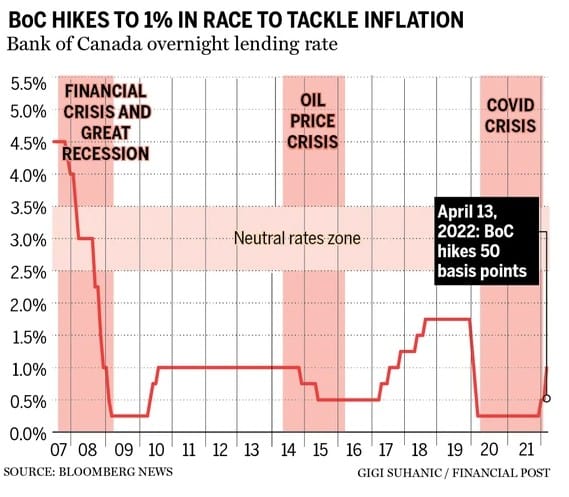
Lately, the talk of the town seems to be rising interest rates. In April, the Bank of Canada raised the benchmark interest rate by a whopping 0.5% to 1%, making it the biggest rate hike since 2000. Given the high inflation rate, it is almost a given that these rate hikes will continue throughout 2022 and beyond. [On July 13, 2022, the BOC hiked a further 1%: editor.]

But before you freak out, let’s step back and look at the big picture. At 1%, the benchmark interest rate is still relatively low compared to the past interest rates.

I still remember years ago before the financial crisis, being able to get GIC rates at around 5%. And some people may remember +10% interest rates in the 80s or early 90s. Back then, interest rates were much much higher than measly below 1% rates we’ve been seeing the last decade.

Historical BoC overnight rates
What’s going to happen to the stock market? Well the general rule is that when Bank of Canada or the Federal Reserve cuts interest rates, the stock market goes up. When Bank of Canada or the Federal Reserve raises interest rates, the stock market goes down.

Continue Reading…

Time to go on a Financial Media Diet

LowrieFinancial.com: Canva custom creation

By Steve Lowrie, CFA

Special to the Financial Independence Hub

In my recent mid-year letter to clients, I decided we’d best just call a spade a spade, so I began as follows:

“Let’s not sugarcoat this: 2022 has challenged investors on nearly every financial front imaginable so far this year.”

Stock and bond markets plummeting in tandem, the war in the Ukraine, rises in interest rates, threats of a looming recession … You’re probably already well aware of the volume of news wearing us down. As I wrote to my clients:

“the financial press has gone on a feeding frenzy in response, serving up heaping helpings of negativity upon negativity.”

Everyone loves a Perma-Bear

Whether by traditional channels or social media streams, amplifying extreme news is in large part what the popular financial press does.

They’re not entirely to blame; we consumers tend to gobble it up with a spoon. That’s thanks to a behavioural bias known as loss aversion, which causes the average investor to dislike losing money approximately twice as much as they enjoy gaining it. Our “fight or flight” instincts basically prime us remain on constant high-alert when it comes to protecting our life’s savings.

Media outlets know that, and routinely round up a stable of talking heads to scratch that behavioural itch. Their “regulars” even earn catchy nicknames:

Perma-bear

Back in 2012, economist David Rosenberg put together a presentation called 51 Signs the Economy Is a Total Disaster. (What, only 51?) We know that reality begged to differ. He tried again in 2019, when he declared: “We’re going into a recession … I think it will be this coming year.” It didn’t happen.

Dr. Doom

Whenever the press needs a fresh Armageddon forecast, they know they can call on “Dr. Doom” economist Nouriel Roubini. It doesn’t seem to matter that he’s been mostly wrong far more often than not. As recently as early July, Roubini was predicting a 50% freefall in the stock market. So far, not so much (thankfully).

Recession Man

As reported in ‘Recession Man’: Burry’s Tweets Resonate With Traders Worried About A Downturn, hedge fund manager Michael Burry built his fame from correctly calling the 2007 U.S. subprime mortgage crash. Lately, he’s been posting cryptic tweets to his nearly 1 million followers that “reflect increasing fears of an economic downturn.” As academic Peter Atwater explains of Burry’s popularity:

“The tweets that get shared and liked the most are the ones that fit with how we feel the most … Twitter is an enormous mirror.”

If you look closer, you might spot a card hiding up these soothsayers’ sleeves: with a large, random group of “experts” loudly predicting doom and gloom nearly all the time, basic statistics informs us: a few of them are going to be right every so often, with seemingly uncanny accuracy. Their fortuitous timing makes them look super smart, which earns them even more fame. The cycle continues.

Going on a Financial Media Diet

On many fronts, times are indeed disheartening, and we’re as worn out as you are by the weight of the world. That said, there are already way too many outlets cramming worst-case scenarios down our throats and crushing investment resolve. To offset a bitter pill overdose, following are a few more nutritious news sources to reinforce why we remain confident that capital markets will continue to prevail over time, and that long-term investors should just stick to their plan.

Stock Markets Grow

The following chart is one of our favorites, as it shows at a glance that which the bad news bears routinely disregard: Stock markets have gone up nicely, and far more frequently than they’ve gone down. We have no reason to believe current trends are going to alter this uplifting, nearly century-long reality.¹ Continue Reading…

A Comprehensive Guide to Buying your First Home

By Mario Pineda

Special to the Findependence Hub

Thinking about buying a home? As of late 2021, there were 646,053 active home listings, according to Rocket Mortgage. More homes are likely to come on the market in spring and summer, which are hot selling seasons. Investing in a home purchase can afford buyers an asset that, ideally, should maintain or, hopefully, increase in value. Some buyers simply want a place to hang their hat and call their own. Whether you’re raising a family, need space for your dogs, or are ready to tackle the responsibilities of maintaining a house, you can rely on this guide to provide you with the essential information you need to know before you buy one.

 Are you ready to buy a House?

Buying a house is a big commitment — living in a specific location, paying a mortgage for decades, and maintaining a property (in order to preserve its value). Many people either aren’t ready to settle down into a home of their own or simply prefer to rent, leaving property maintenance to property owners. You’re likely ready to buy if you:
  • Are annoyed or tired of renting: typically, renting involves loads of rules stipulated by landlords, annual rent increases, and a lack of privacy (mainly if you live in an apartment complex).
  • Want to invest in real estate: investing in real estate is a common reason why people buy houses. Unlike rent, which is gone once you pay it, your mortgage payments are applied to the home’s purchase. In typical cases, you’ll retain that money in the form of your asset or recoup it when you sell the house.
  • Have a family and want more room: if you have a family, you may wish to purchase a home that offers space for each member of your household as well as a backyard that provides outdoor living space. 

Pre-purchase Considerations

Before buying a house, there are various factors to consider before you sign on the dotted line of a purchase contract. A home tends to be a long-term investment. To make the most of it, it’s essential to understand the challenges associated with the buying process and the obligations related to property ownership. By exploring the personal and financial areas of your life, you can arrive at the right decision for you. 

Personal Considerations

Ask yourself if you are ready to commit to living in a specific area. A mortgage is generally a 30-year commitment (unless you choose to sell the property). What are your plans for the future? Do you expect to relocate soon for your job? Do you wish to have children or to expand your family? These considerations may impact your decision to buy as well as the type of home to buy.
Remember, everything regarding the care of the home will rest on you: and your partner if you are purchasing together. Not only is there the monthly mortgage to cover, but there are also the inevitable home maintenance and repair costs that come into the bargain. In short, understand the financial obligation before you as you contemplate your decision.

Financial Considerations

There are other financial factors to reflect upon too. To qualify for a mortgage, you will need a good credit score as well as a down payment. As banks consider your loan request, they will examine your debt. Do you have existing debt, and is it enough to impede your home buying plan? Also, banks will evaluate whether your income is enough to pay the monthly mortgage payment. Look closely at your financial picture because, rest assured, any lender you choose will definitely examine your finances closely.

The Psychology of Buying a Home

You might not realize it, but engaging in the home buying process can be an emotional roller coaster. It’s easy to get your hopes up that a seller will accept your bid. You might fall in love with the perfect house only to realize that the seller accepted another buyer’s bid. You might also find a home with great potential only to find that it has severe flaws like a cracked foundation. It’s important to keep your emotions in check to make a sound investment decision. 

There are other psychological aspects of buying a house that you might not have thought about before. For instance, some people bring cultural superstitions to the process and don’t want to live in a house with specific numbers in the address or are opposed to a particular street name. 

Other people might struggle with the perceived value of a home, believing that interior wall colors will substantially affect its worth. The reality is that cosmetic changes are easy and often inexpensive to fix in cases like this.

If you find yourself contending with psychological factors like these, take a step back and think them through. If they’re going to impede your long-time enjoyment of the home, you may want to keep house hunting. If, however, you think you can spend a decade of your life on “Elm Street,” you may be glad that you didn’t allow a horror movie from the 1980s to sabotage the purchase of your dream home.

Searching for a Home

Speaking of needs, you’ll need to consider them closely so that you can confine your search to homes that satisfy them. Before you begin your house hunting adventure, you should consider:

  • House size: how much square footage will suit you/your household?
  • House exterior: what architectural styles appeal to you? Bungalow, cape cod, modern?
  • Bedrooms: what’s the minimum number of bedrooms you need?
  • Bathrooms: how many bathrooms do you prefer your home to have?
  • Heating and cooling systems: how efficient are these systems? Will they need to be replaced soon after you buy the house?
  • Basement: do you want a home with a basement or cellar?
  • Attic: do you want to purchase a home with a finished attic that offers usable living space?
  • Garage: how much space do you want your garage to have?

How to Choose the Right Neighborhood

The neighborhood of your home is also an important consideration. A great home in a community that you don’t find agreeable can make for an unhappy situation. When you choose a neighborhood to shop for a home, you should consider:
  • Safety: investigate the area’s crime rates, affecting property values.
  • Community services: do you require public transportation? Do you want to live near shopping centers, medical facilities, or parks?
  • Public schools: be sure to assess the quality of area schools if you have school-age children. 
  • Amenities: what are some local amenities in the area? Is there a local swimming pool, forest preserves, entertainment venues like theaters? What about restaurants? 

Top Home Buying mistakes

Many buyers have stumbled into pitfalls when shopping for and buying a house. Try to learn from their mistakes. Here are some of the most common home-buying mistakes to watch out for:

  • Partnering with a real estate agent who doesn’t “get” your needs and preferences.
  • Failing to get pre-approved for a mortgage.
  • Making an offer on the first house you visit.
  • Getting only one rate quote from one lender instead of shopping for a more competitive lender.
  • Buying a house that is more than you can afford.
  • Using all of your savings as a down payment.
  • Not investigating the HOA if the area has one. 
  • Failing to look into first-time homebuyer programs.
  • Not researching the community extensively.
  • Waiving a home inspection.

Special terms for New Home buyers

Is this your first time buying a house? In that case, you’ll undoubtedly want to find out about first-time homebuyer programs and special incentives that can alleviate some of the financial stress associated with buying a home. You may also qualify for programs based on your income or veteran status. An experienced real estate agent will be able to inform you about any programs or incentives that you might qualify for. As a first-time homebuyer, some of the special terms you may be eligible for include: Continue Reading…